I was born on 6 August 1956 in San Francisco, California to Janet and (the late) Richard Hovis.
I grew up in Santa Monica, California where I attended elementary, junior high school, and high school (graduating in 1974), in addition to involvement in sports and recreation (Little League +, the Boy’s Club ++). Further, it was in elementary school – St. Augustine’s By-the -Sea Parish School that I found, and made the choice to truly journey with God.
I attended Arizona State University from 1974 to 1977 – seeking to become an architect, however, I was not accepted, and, as such, I graduated with a Liberal Arts degree.
Upon graduation from Arizona State University, I attended Cal Poly San Luis Obispo and studied City and Regional Planning at the Master’s level. I successfully completed one (1) year in a two (2) year program – I did not complete the Master’s degree in City and Regional Planning – due to personal reasons.
I returned to Santa Monica where I started (October 1979) my career as graphic designer with Exxon Company, USA. I spent five years with Exxon Company, USA.
While working with Exxon Company, USA I was accepted into architectural school – Sci-Arc in Southern California, however, I did not attend preferring to stay with Exxon..
In 1982 I married Laura Flosi and in April 1983 we had our one and only child – Lauren Alain Hovis – a gift from God.
We moved to Phoenix, Arizona in 1984 from Los Angeles, where I went to work as a graphic designer with Kitchell CEM (from 1985 -1987).
From 1987 – 1995 I was an independent contractor, and a registered representative in mortgage finance, financial management, graphic design, and drafting.
Further, I attended the University of Phoenix and successfully obtained a Master’s in Business Administration (MBA) in 1982.
I was also a member of the Scottsdale Jaycees, where I became very involved in community events and projects.
In 1994, I accepted a cartography position with the Defense Mapping Agency in Reston, Virginia. As such, I relocated from Phoenix to Reston.
In 1998, I was accepted and worked as a Visual Information Officer with the Central Intelligence Agency. In 2002, I worked as a Support Officer until my retirement (due to a need for shoulder surgery) in September 2018.
Away from my Federal Government service, I have been involved in various organizations and activities in Northern Virginia.
In November of 2011, I married Rebecca Ouellette in Santa Monica, California. I reside in San Tan Valley, AZ with my two hamster - Jess and Timothy, our fish, our lizard - RJ Lizard., and our cats - Pearl and Grey.
As to hobbies, I enjoy playing sports, attending sporting events, mentoring individuals from financial management to hamsters, building models, photography, travel, multimedia design, managing partner for RJ Hamster, and jazz – smooth jazz to a samba or a bossa nova.
Love and God Bless,
Peter – aka RJ Hamster Jo hi
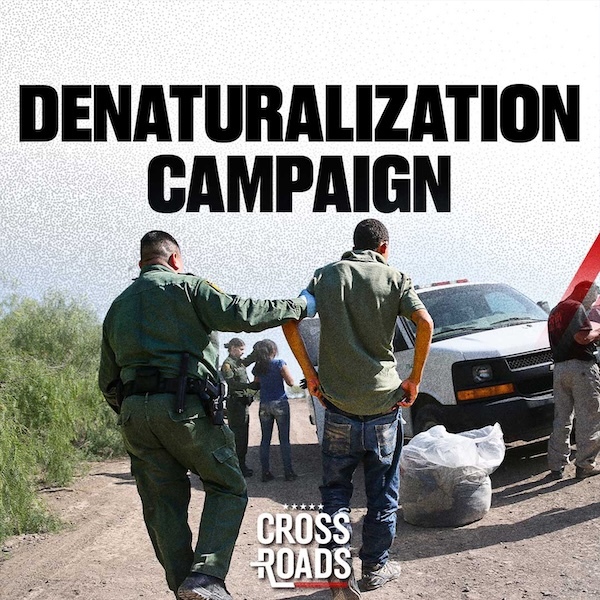
A new campaign aims to strip naturalized Americans of their citizenship, and the criteria of who will be targeted are now being announced. The Trump administration says it will expand its use of denaturalization, which until now was a rarely used power. 🎧 Listen →
Just as the hantavirus situation was resolved aboard the MV Hondius, another cruise liner was hit with a massive viral outbreak. The silver lining here, though, is that the virus in question isn’t as bad as hantavirus, which has a mortality rate of 30–50 percent. 🎧 Listen →
Thanks for tuning in!
Today’s newsletter was put together by Ivan Pentchoukov, Lina Skorbach and Kenzi Li. Send them your feedback at podcasts@epochtimes.us.
Our mailing address is: The Epoch Times, 129 West 29th Street, Fl 8, New York, NY 10001 | Contact Us
The Audio Room newsletter is one of the best ways to receive the most up-to-date information. Manage your email preferences here or unsubscribe from The Audio Room here.
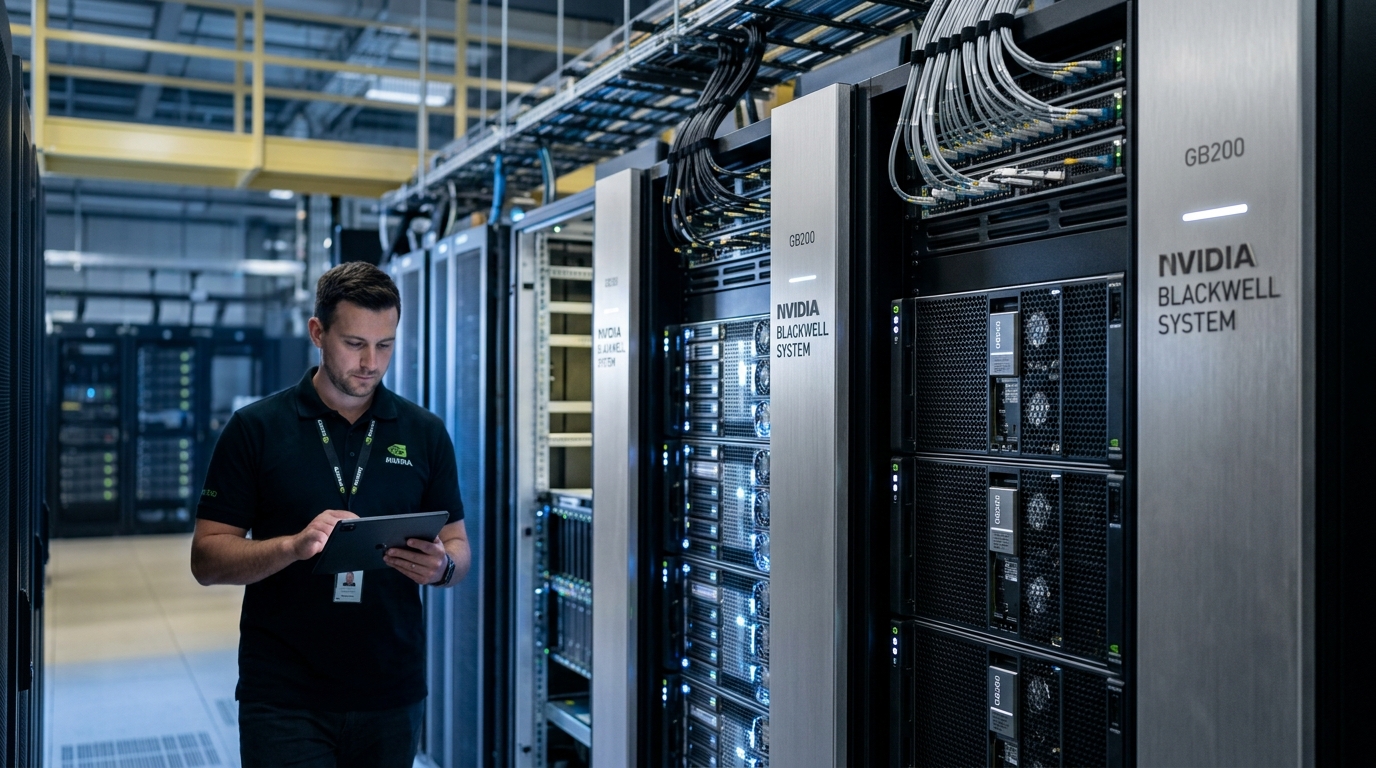
One of the most closely watched earnings reports of the year is coming up. Nvidia closes the books on fiscal Q1 2027 after the bell on May 20th and if the external data building around it is any guide, the company has not slowed down.
What happened in fiscal 2026 is worth stating plainly: $215.9 billion in total revenue, up 65% year over year. Data center alone hit $197.3 billion — more than double the $115.2 billion it posted the year prior. Q4 FY2026 came in at $68.1 billion, clearing the $66.2 billion Wall Street estimate, with GAAP gross margins at 75%. Management then guided Q1 FY2027 at $78 billion, a number that itself arrived above what analysts had penciled in. That’s the baseline.
The harder question isn’t whether Nvidia is executing. It clearly is. The harder question is whether May 20 delivers anything the market doesn’t already know.
A Quick Company Snapshot
Nvidia holds over 90% market share in data center GPUs. That number gets cited constantly, but the more durable moat is CUDA — the software platform Nvidia introduced in 2006 that became the default language of AI development. Over 4 million developers build on CUDA. Every major AI framework, including PyTorch and TensorFlow, runs on it. You don’t walk away from two decades of tooling investment just because a competitor ships a faster chip.
Revenue now breaks across four segments: Data Center at over 91% of total sales, Gaming, Professional Visualization, and Automotive. Gaming still matters at the margin. Data center is the whole business.
Consensus sits at approximately $78.8 billion in revenue and $1.78 EPS for Q1 FY2027. A few estimates have quietly drifted higher — ChartMill’s aggregated consensus is now at $80.1 billion in revenue and $1.79 EPS. That divergence matters. If the effective bar heading into May 20 is closer to $79–80 billion, hitting the company’s own $78 billion guidance target may not generate much of a reaction in either direction.
The specific metrics worth tracking:
Data center revenue: Q4 FY2026 was $62.3 billion, up 75% year over year. Q1 FY2026 data center was $39.1 billion — the year-over-year comparison is favorable and the trajectory is expected to hold
Gross margin: Management guided GAAP gross margins of ~74.9% and non-GAAP at ~75.0% for Q1. Full-year FY2026 came in at 71.1% GAAP and 71.3% non-GAAP — the sequential improvement is the story here
EPS: Consensus range is $1.74–$1.79. Full-year FY2026 non-GAAP EPS was $4.77; FY2027 consensus is $8.34, which would represent a near-doubling in a single year
Q2 FY2027 guidance: Consensus is around $86.6 billion, representing roughly 85% year-over-year growth. This number — not the Q1 result — will drive the post-earnings reaction
Free cash flow and balance sheet: Nvidia generated $97 billion in free cash flow in fiscal 2026, returned $41 billion to shareholders, and enters Q1 with $51.1 billion in net cash
One accounting change to flag. Starting in Q1 FY2027, Nvidia will include stock-based compensation in its non-GAAP financial measures. That adds roughly $1.9 billion to non-GAAP operating expenses and compresses non-GAAP gross margin by approximately 0.1%. Year-over-year EPS comparisons will not be clean without adjusting for this shift.
What Analysts Are Actually Saying
Goldman Sachs — Buy, $250 price target. Internal estimates run 14–34% above broader Wall Street consensus through FY2027
Susquehanna (Christopher Rolland) — Buy, target raised to $275 from $250. Cites surging hyperscaler capex and combined Blackwell/Rubin revenue that could exceed $1 trillion through 2027
38+ firm consensus — Strong Buy. Median 12-month price target near $265–$267, implying roughly 20–24% upside from current levels near $220
Price target range — Tigress Financial high at $360; consensus low at $210
Why Forward Estimates May Still Be Too Low
The hyperscaler capex figures that have been filed and reported over the last several months are, frankly, larger than most analysts were modeling at the start of 2026. Microsoft announced $190 billion in planned AI capex for the calendar year — well above the $154 billion Wall Street had been using. Meta raised its ceiling to $145 billion. Alphabet’s guidance reached up to $190 billion. Amazon committed $200 billion. Morgan Stanley’s latest forecast puts combined capex among the five largest hyperscalers at approximately $805 billion in 2026, representing nearly 80% growth year over year, followed by an additional 39% increase to $1.1 trillion in 2027.
You don’t build $800 billion worth of AI infrastructure without GPUs. And at this scale, there is no GPU supplier that can absorb that demand except Nvidia.
Slight tangent, but it matters: the valuation here is not as stretched as it looks on the surface. Nvidia’s non-GAAP EPS for FY2026 was $4.77, implying a forward P/E of approximately 40.5 on those earnings. On FY2027 consensus EPS of $8.34, the forward multiple drops to roughly 23.8x — actually the lowest next-twelve-month P/E among its closest peers. Broadcom trades at 31.3x. ASML at 36.1x. High-growth business, lower forward multiple. That’s the part people skip.
Sponsored
In at 9:35 AM. Out by 10.
I call it the “Opening Bell Breakout.” It’s the same setup I used to catch moves like 113% on GOOGL and 240% on META. I trade one simple 15-minute window each morning – and I’m usually done by 10 AM.
Blackwell Ultra is the dominant shipping architecture right now, with prior-generation Blackwell still seeing active demand. CFO Colette Kress confirmed on the Q4 call that Nvidia shipped first Vera Rubin samples to customers in late February 2026 and remains on track for full production in the second half of this year.
The Rubin platform is a meaningful performance step forward. Key numbers versus Blackwell:
Up to 10x reduction in inference token cost
4x fewer GPUs required to train mixture-of-experts models
Up to 18x faster rack assembly and servicing via modular, cable-free tray design
First Nvidia platform to offer Confidential Computing at rack scale
Spectrum-X Photonics switch systems delivering 5x improved power efficiency
Early adopters confirmed for H2 2026 deployment include AWS, Google Cloud, Microsoft Azure, and Oracle Cloud Infrastructure, alongside cloud partners CoreWeave, Lambda, Nebius, and Nscale. OpenAI, Anthropic, Meta, and xAI have all committed to Rubin for training larger models and running long-context multimodal systems.
One wrinkle: TrendForce estimates Rubin’s share of Nvidia’s overall 2026 shipments will land around 22%, below earlier projections of 29%, due to challenges with HBM4 memory validation, cooling optimization, and interconnect transitions. Blackwell is expected to hold over 70% of shipments. Analysts characterize any deferral as a timing issue rather than a demand problem — but that’s a distinction worth pressing on during the May 20 earnings call.
China: The Wildcard in the Guidance
Nvidia’s Q1 FY2027 guidance assumes zero China data center compute revenue. That has been the working assumption since the U.S. government required export licenses for H20 shipments to China in April 2025 — a restriction that triggered a $4.5 billion inventory charge in Q1 FY2026, the single largest export-related write-down in the company’s history.
The situation has partially shifted. Jensen Huang confirmed at GTC 2026 that Nvidia received purchase orders for H200 chips from ByteDance, Alibaba, and Tencent — over 400,000 units combined — following clearances from both U.S. and Chinese authorities. A 15% fee on those China sales, paid to the Department of Commerce, was implemented as a condition of the export license. Analysts estimate that a reopened China market represents a $5–10 billion annual revenue opportunity. None of that is reflected in current guidance. If any of it shows up in Q1 actuals or Q2 guidance language, it is pure upside to published estimates.
Three Ways This Quarter Plays Out
Bull case: Q1 revenue clears $80 billion. Q2 guidance lands at $88–90 billion or above. Management provides updated language on demand visibility into H2 2026 and beyond. Any positive China data center commentary adds further. Gross margins hold at 74–75% non-GAAP, confirming the Blackwell ramp is not compressing profitability. In this scenario, FY2027 EPS estimates move higher and the valuation re-rates from current levels.
Base case: Q1 revenue lands in the $78–80 billion range. Q2 guidance meets consensus near $86–87 billion. Gross margins hold. The stock drifts — the result is solid but investors had already expected solid. This is the scenario where the stock’s 15% year-to-date gain and high pre-earnings positioning work against a meaningful move in either direction.
Bear case: Q1 revenue hits management’s $78 billion guidance but falls short of the $79–80 billion the market has quietly priced in. Q2 guidance comes in below $86 billion. Gross margins disappoint at the low end of the guided range. Negative commentary on Rubin timing, hyperscaler capex durability, or China export complications amplifies the downside. Worth noting: post-earnings declines in Nvidia are not unusual even on beat quarters. The Q4 FY2026 report saw the stock rally initially and then give back most of those gains despite beating both the top and bottom line.
Five Things to Watch on the Call
Q2 revenue guidance vs. $86.6B consensus — this is the single number that determines the reaction, full stop
Rubin production timeline — any update on the H2 2026 schedule and early customer demand signals
China commentary — whether H200 revenue appears in Q1 actuals or gets incorporated into Q2 guidance language
Gross margin trajectory — management has targeted the mid-70s; watch whether they reaffirm or soften that language
Hyperscaler concentration — cloud providers represented just under 50% of data center revenue in recent quarters; any shift in customer mix changes how durable the demand base looks through 2027
Sponsored
Wall Street Issues Dire Warning to Clients
Wall Street has issued a chilling warning for anyone with money in the U.S. stock market right now. Top analysts at these banks say a big event is coming that could both wipe out the market and keep it down for 10 years or longer. What can you do? A new tech breakthrough from a firm in Baltimore, Maryland may hold the answer.
The fundamental case for Nvidia is not a subtle one. Hyperscalers are committing more capital to AI infrastructure than Wall Street modeled at the start of 2026 — significantly more. Blackwell is in full production. Rubin is shipping samples with confirmed production launches in H2 2026. The company holds $51 billion in net cash, generated $97 billion in free cash flow last fiscal year, and trades at a lower forward earnings multiple than most semiconductor peers despite meaningfully higher growth rates.
The harder question is how much of that is actually unknown to the market heading into May 20. The stock is up 15% year to date. Expectations are high — probably higher than stated consensus reflects. Meeting guidance but not exceeding it may not be enough to push the stock higher from here.
If Q2 guidance clears $86.6 billion and China access gets folded into the forward outlook, that’s a different situation entirely. If neither happens, this could be one of those quarters where a strong result goes nowhere fast.
Watch the Q2 guidance number above everything else. That’s the real signal on May 20.
For informational purposes only. Not financial advice.
This content is for informational purposes only and should not be considered financial advice. Investing involves risk.
The Cheap Investor is a publication of Investing Media Solutions, LLC.
Welcome to Insider Trades Daily, glad you’re here!
Every day, more than 500,000 investors use this newsletter to track insider buying and selling across major public companies. It’s a simple way to see what the people closest to the business are doing with their own money.
Before we start sending your daily updates, there’s just one quick thing left to do. Please confirm your subscription using the link below.
P.S. If there’s anything we can do to improve your experience, please let us know by replying to this email.
Today’s Bonus Story
Nebius Breaks Out to All-Time Highs—Here’s What’s Driving It.
Written by Ryan Hasson. Date Posted: 5/5/2026.
Key Points
Nebius Group announced a $643 million acquisition of Eigen AI, driving NBIS shares to an all-time high of $176.42 on May 4.
The company holds a contracted backlog approaching $50 billion, anchored by major commitments from Meta, Microsoft, and a $2 billion NVIDIA investment.
Investors will want to watch the May 13 earnings report for ARR trajectory, hyperscaler deployment updates, and guidance on the Eigen AI integration timeline.
Nebius Group (NASDAQ: NBIS) has been one of the market’s most extraordinary stories over the past year, and this week the momentum has accelerated even further. The stock closed Monday, May 4, at a new all-time high of $176.42, up more than 14% on the day and roughly 600% over the past 12 months.
For investors who have followed the Nebius story since its early days as a small-cap AI infrastructure play with minimal analyst coverage and $120 million in annualized revenue, the transformation has been nothing short of remarkable.
And the catalyst behind this week’s breakoutis anything but noise. Here’s what is driving the latest momentum in NBIS, and what investors should watch next.
The Catalyst: Eigen AI
On May 1, Nebius announced it had agreed to acquire Eigen AI for $643 million. Eigen is an inference and model-optimization specialist focused on making AI model deployment faster and cheaper by reducing compute and memory requirements. The acquisition is strategically significant. Nebius plans to integrate Eigen’s technology directly into its Token Factory managed inference platform, enabling developers to deploy, refine, and scale AI models more efficiently on Nebius infrastructure.
The deal signals something important about where Nebius is headed as a business. The company has spent the past year building the physical infrastructure layer of the AI cloud stack: large-scale GPU clusters, data centers, and cloud services. The Eigen acquisition represents a deliberate move up the stack toward higher-margin, software-defined services. And for a company guiding toward $3 billion to $3.4 billion in 2026 revenue, expanding the platform’s capabilities and margin profile at this stage of growth is the right move.
The Foundation Underneath the Move
It is worth stepping back and appreciating what sits beneath these latest catalysts. Nebius enters this breakout with a contracted backlog approaching $50 billion, anchored by a $27 billion multi-year deal with Meta Platforms (NASDAQ: META), up to a $19.4 billion commitment from Microsoft (NASDAQ: MSFT), and a $2 billion strategic investmentfrom NVIDIA (NASDAQ: NVDA). Management has guided for 2026 revenue of $3 billion to $3.4 billion, up from $530 million in full-year 2025.
The company recently closed a $4.34 billion convertible debt financing round, giving it the financial firepower to execute on its aggressive capital plan without being constrained by its balance sheet. Q1 2026 earnings are due May 13, with analysts projecting a significant sequential revenue jump from Q4’s $227.7 million.
For a company that had almost no analyst coverage and $120 million in annualized revenue roughly 18 months ago, the scale and pace of that transformation is difficult to overstate. The overall consensus among analysts covering the stock remains bullish, with a Moderate Buy rating and a consensus price target of $154.75. As of May 5, the company had 15 analyst ratings, but that wasn’t always the case. In May of last year, the stock was covered by only two analysts, with a consensus price target of $45, when it was trading at almost $26 a share.
The Technical Picture
Of course, the company has gone from strength to strength, as shown by the stock’s rapid appreciation. With NBIS near all-time highs and up more than 100% on the year, disciplined investors probably do not want to chase the current price.
However, after earnings, if the stock beats expectations and issues strong guidance, a new opportunity could emerge. If the stock establishes a fresh base and consolidates above prior resistance near $160, a subsequent breakout could be the trigger that investors on the sidelines are waiting for.
What to Watch Next
The May 13 earnings report is the next major event on the calendar. Investors will be focused on three things: the ARR trajectory and whether it is tracking toward the $7 billion to $9 billion full-year 2026 target, operational updates on the Meta and Microsoft hyperscaler deployments, and early commentary on the Eigen AI integration timeline.
For a stock trading at all-time highs after a near-600% run over the past year, the bar heading into earnings is high. But with the Eigen acquisition expanding the platform’s capabilities, the contracted backlog providing revenue visibility that few AI infrastructure companies can match, and a growing roster of top-tier analysts now covering the name, the fundamental momentum heading into that report looks as strong as it has ever been.
Thank you for subscribing to Insider Trades Daily, which covers the most recent insider buying and selling activity from Wall Street CEO’s, CFO’s, COO’s and other insiders.
If you need help with your subscription, please feel free to email our U.S. based support team at contact@marketbeat.com.
If you no longer wish to receive email from InsiderTrades.com, you can unsubscribe.
Welcome to Insider Trades Daily, glad you’re here!
Every day, more than 500,000 investors use this newsletter to track insider buying and selling across major public companies. It’s a simple way to see what the people closest to the business are doing with their own money.
Before we start sending your daily updates, there’s just one quick thing left to do. Please confirm your subscription using the link below.
Several factors, including store count growth and positive same-store sales comps, position the business to accelerate revenue growth, while the reduced share count provides investors with additional leverage. The likely outcome is that Chipotle Mexican Grill will continue to perform well in 2026, outperform estimates, and sustain a bullish analyst revision cycle.
The key operational factor in 2026 is comps. The company has struggled with comps over the past year or so, relying heavily on new store openings to drive growth.
Now, with store count up on a one-year, two-year, five-year, and 10-year basis, and expected to keep growing, positive comps should magnify the impact. Questions about durability can be answered by this year’s jobless claims data, which inflected to contraction in January, suggesting improving labor market conditions and consumer strength in 2026.
Chipotle Mexican Grill Provides Shareholders With Leverage
Share buybacks are critical to this equation. The company generates ample free cash flow, has no debt other than its long-term lease obligations, and aggressively repurchases shares. Trailing 12-month activity resulted in a 4.3% average decline in share count in Q1, and future buybacks are expected. One catalyst for share price action is an anticipated increase in buyback activity, which could come at any time.
The balance sheet raises a red flag, as the company’s equity has declined by nearly 15% year over year (YOY). However, the decline is largely due to a reduction in share count and, to a lesser degree, margin impairment, both of which are expected to reverse in upcoming quarters. Improving same-store sales point to better unit economics and stronger margins for this consumer favorite. Until then, the balance sheet remains healthy, enabling the company to continue executing its strategy. That includes expansion of domestic and international store counts, potentially doubling the company’s footprint within the next five to seven years.
Valuation metrics also align with the outlook for a robust increase in stock prices. The 28X current-year earnings at which the company trades in 2026 is a bit rich; however, it reflects a solid outlook that is likely still cautious. In this scenario, consensus forecasts put the stock under 10X earnings at the 7-year point, suggesting 100% upside relative to the broad market average and as much as 200% if the company sustains a premium. If the forecasts prove to be cautious, as is likely, the upside potential could be even greater.
Analysts and Institutions Drive CMG Stock Into Reversal
Analysts are responding with cautious optimism. Although margin pressures remain a concern, many have pointed to the positive inflection in comps as a catalyst for the stock. That inflection signals traction with the Recipe for Growth strategy, leading to reaffirmed price targets and ratings.
As it stands, the 35 analysts MarketBeat tracked in late April carried a consensus rating of Moderate Buy; there is a 65% buy-side bias and no Sell ratings. The consensus price target implies 40% upside from the critical support level, with higher highs likely if momentum builds in Q2.
Post-release price action was bullish, with the stock rising 5% in after-hours and premarket trading, likely underpinned by institutions. The group owns more than 90% of the stock and has been aggressively accumulating while shares traded at long-term lows.
MarketBeat data shows a $1.5-to-$1 pace over the trailing 12 months, with activity ramping sequentially into Q1 2026. The balance in early Q2 sustained the bullish pace and will likely accelerate, given the catalysts in Q1 results.
Double-Bottom in Play for CMG Stock
CMG’s price action aligns with a double bottom, but it has not yet cleared the critical hurdles. While support is evident at the long-term lows and is likely to hold, resistance near $36, $37, and $40 may cap gains in the near term. Longer term, the key resistance level is near $40, aligned with the long-term 150-week exponential moving average and a pivot point crossed in mid-2025. A move above that level would signal a major shift in the market and could lead to fresh all-time highs within the next few quarters.
Chipotle’s biggest risks this year are inflationary pressures and international expansion. Inflation, particularly in beef and cooking oils, is eroding results, while geopolitical tensions threaten the pace of expansion. Beef prices, which remain high amid tight supply, are not expected to moderate until next year, if at all, while international expansion plans may be thwarted in Kuwait and the UAE, both precariously close to regional conflict zones. Delays will be reflected in the stock price.
Thank you for subscribing to Insider Trades Daily, which covers the most recent insider buying and selling activity from Wall Street CEO’s, CFO’s, COO’s and other insiders.
If you have questions about your newsletter, please feel free to email our South Dakota based support team at contact@marketbeat.com.
If you no longer wish to receive email from InsiderTrades.com, you can unsubscribe.
Copyright 2006-2026 MarketBeat Media, LLC. 345 N Reid Pl. #620, Sioux Falls, S.D. 57103-7078. United States..
🌾 Herbal Health Digest welcomes your feedback and questions. Please note: we cannot provide individualized health or medical advice.
🍃 This Herbal Health Digest email reached you at peter.hovis@gmail.com — where wellness meets inspiration. You can unsubscribe anytime using the link below.
🌼 We’re here for you! Get in touch with Herbal Health Digest, Mon–Fri (9am–5pm ET) at +1 (305) 404-8925, or email support@herbalhealthdigest.com.
💬 We put care into every word we share — please don’t copy or distribute Herbal Health Digest content without our written permission.
When neuropathy isn’t treated at the root, it can slowly eat away at your nerves — until you can’t open a jar, hold a fork, or even feel the ground beneath your feet.
And the worst part? Some of the most commonly prescribed treatments — like Gabapentin and Pregabalin — can actually make things worse over time. They only mask the symptoms, while the real cause keeps doing damage.
I learned all of this from a powerful study published by Harvard University.
➡️ The research showed that the real cause of neuropathy has nothing to do with age or physical wear and tear. It’s actually linked to a silent nutritional deficiency that damages both your peripheral nerves and your brain.
This deficiency has been spreading rapidly since June 2024 — especially in adults over 60.
If you or someone close to you experiences:
Constant numbness or burning in hands or feet
Sudden, unexplained shocks
Loss of balance
Trouble with simple tasks, like buttoning a shirt or opening a bottle
… chances are, you’re dealing with this hidden deficiency too.
The good news? There’s a little-known yellow vitamin that may help reverse this — often within just a few days.
It was discovered by Nobel Prize–winning scientists and has already helped over 48,000 people regain sensation and mobility.
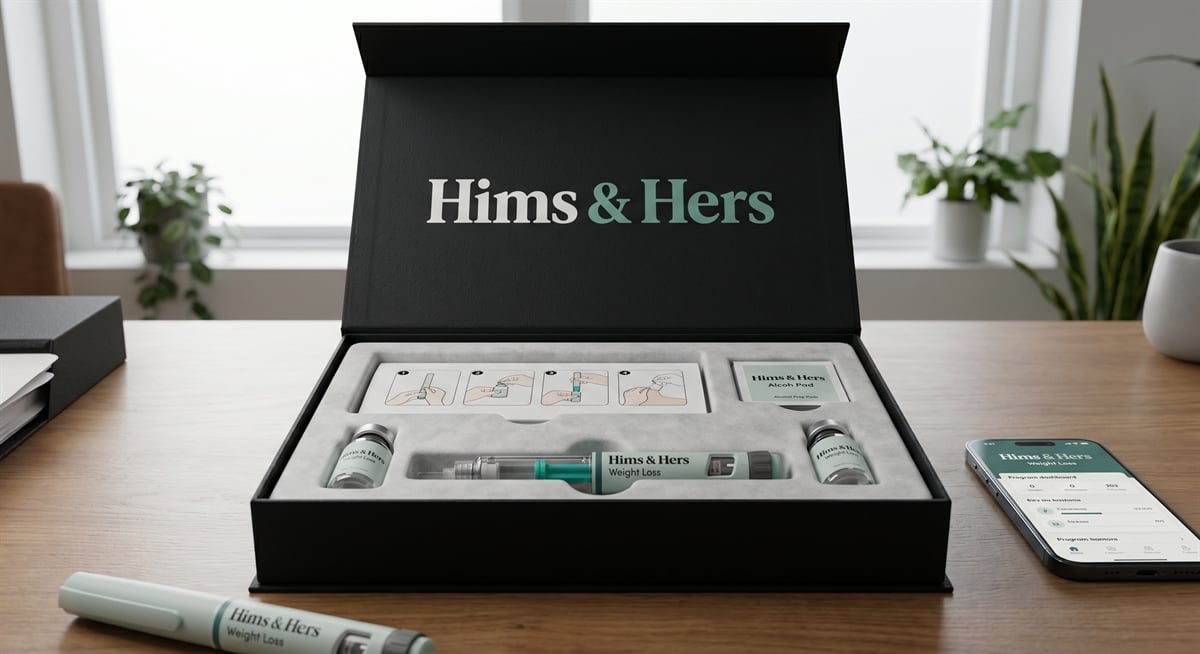
Hims & Hers Earnings Preview: The Novo Nordisk Shift Puts GLP-1 Strategy in Focus
Written by Jessica Mitacek on May 8, 2026
Key Points
Following a settled legal dispute with Novo Nordisk, HIMS has transitioned from selling compounded weight-loss drugs to offering brand-name Wegovy and Ozempic.
While the deal was finalized in March, investors are eager to see if this pivot will boost the top line or if the financial impact likely won’t be seen until Q2.
Despite its recent rally, the stock remains highly volatile with short interest exceeding 35%.
Healthcare stocks have struggled in 2026. With a year-to-date (YTD) loss of about 6%, that corner of the market has been the worst performer among all 11 sectors of the S&P 500 in 2026.
While that has been reflected in the YTD losses of some of Big Pharma’s biggest names, it has also adversely affected mid-cap stocks like telehealth platform Hims & Hers Health (NYSE: HIMS), which has fallen by more than 23% in 2026.
One day after a big announcement from the U.S. Food & Drug Administration (FDA) caused shares of HIMS to jump by nearly 4%, the stock gave it all back on Thursday, falling by nearly 5% as traders locked in profits.
But that wasn’t enough to derail the stock’s recent rally, which has seen HIMS gain nearly 32% over the past month and around 77% since its 52-week low on Feb. 27. As the company prepares to report Q1 2026 earnings on May 11, here’s what investors should watch for.
Is the Novo Nordisk Partnership Already Paying Off?
Following a well-publicized legal disputeearlier this year with Denmark-based Novo Nordisk (NYSE: NVO)—the eighth largest publicly traded pharmaceutical company in the world with a market cap of more than $204 billion—it’s been smooth sailing for Hims & Hers.
Since Novo Nordisk dropped its patent infringement lawsuit on March 9, HIMS has been on a tear. Not only did the Danish firm abandon its case, but it also reached a deal that allows Hims & Hers to sell Novo Nordisk’s brand-name Wegovy and Ozempic through its direct-to-consumer and virtual medical services platform.
As part of that deal, Hims & Hers agreed to stop advertising its compounded GLP-1 products, which given the FDA’s announcement that it is proposing that semaglutide, tirzepatide, and liraglutide be excluded from its 503B bulks list, could prove prescient for the company.
Wall Street will be looking for how that deal has impacted Hims & Hers’ top line. Despite the strategic shift being announced on March 9, Novo Nordisk’s GLP-1 products were not available for sale through the online platform until March 26. The books for Q1 closed on March 31, so those gross sales may not materialize on Hims & Hers’ income statement until Q2.
Will Hims & Hers Continue to Show Subscriber Growth?
The market will also be looking for confirmation that Hims & Hers’ total subscribers are holding above 2.5 million, if not steadily growing from there. That benchmark was reached near the end of 2025 and marked a more than 16% increase from the 2.2 million subscribers the company had at the end of 2024.
That growth is proving to be sustainable, after Hims & Hers ended 2023 with 1.5 million. But more important than the raw subscriber count is how the telehealth company generates 90% of its recurring revenue from its customer base.
Approximately 82% of its users remain on the platform for more than three months, and if Hims & Hers can demonstrate that it is sustainable, it should bolster full-year guidance.
Meanwhile, analysts are expecting earnings per share (EPS) of around three to four cents, which would mark an estimated 90% year-over-year decline. That may already be priced in, given the stock’s YTD performance, but a miss could accelerate selling.
The same goes for quarterly revenue, which consensus forecasts put in the range of $616 million to $619 million. Wall Street is already bracing for a “reset quarter” after revenue growth tapered from nearly 111% in Q1 2025 to less than 29% in Q4, so any surprise to the upside could spur another leg to the current rally.
When the SpaceX IPO launches, most retail investors will be locked out. The banks, funds, and insiders get in early – while everyone else waits on the sidelines.
But one small infrastructure supplier – a critical piece Musk can’t scale the Colossus network without – is still trading well under institutional radar. A new briefing reveals the name and ticker at no cost.Get the SpaceX infrastructure stock name and ticker here
Analysts Are Taking a Wait-and-See Approach
Despite an average 12-month price target of nearly $32, which implies potential upside of around 24%, Wall Street remains tepid on the stock.
Of the 17 analysts currently covering HIMS, four assign it a Buy rating, 12 assign it a Hold rating, and just one assigns it a Sell rating. Overall, the stock receives a consensus Hold rating.
Institutional ownership of nearly 64% falls within the typical range for mid-cap companies. Outflows of $1.62 billion have nearly caught up to inflows of $1.8 billion over the past 12 months after selling accelerated in Q4 2025. But that trend reversed in Q1, with institutional selling 88% lower than institutional buying.
With a high beta of 2.43, the inherently volatile stock is currently being heavily targeted by bears. Concerningly, more than 35% of the float—or nearly 70 million shares of the almost 228 million shares outstanding—is currently shorted.
Still, strong earnings could shift sentiment and propel the stock closer to the consensus analyst price target. Shareholders and prospective investors should mark their calendars for Monday, May 11, when Hims & Hers Health reports Q1 2026 results.
In the summer of 1961, a young American psychologist began an experiment on obedience. Not yet 30, he’d recently earned his Ph.D. in psychology from Harvard under the tutelage of Gordon Allport, and he wanted to understand how ordinary people could participate in atrocities.
Do you have feedback for our coverage? Tell us what you think by replying to this email.
We are still running special subscription deals in light of the ongoing war with Iran. Take this opportunity to become an Epoch Times subscriber—at the best rates possible—while they’re still available!
The Epoch Times strives to fill the void at a time when partisan and biased reporting has become commonplace. As staunch believers in traditional journalism, we rigorously pursue facts and accuracy, leaving views strictly as opinions.
When you do choose to explore people’s perspectives, we guarantee you the freedom of thought. Too often, certain voices are suppressed or silenced—that’s never the case at The Epoch Times. Browsing through the commentaries, you will immediately recognize honest, refreshing, and at times courageous discussions on topics perhaps purposefully left out by others: HollywoodCan Still Make Great Movies; What I Sawat the White House Correspondents’ Dinner; A Former Anthropic Employee’s Last Warning
… They are truly a feast for the mind.
Explore our entire treasure trove of content for $0.50 per week for a full year—our best annual plan. Subscribe Now
🎨 Fine Arts: A mother’s embrace — capturing pure and unconditional love: Over generations, five classical paintings demonstrate the timeless subject of maternal love.
🎼 Music:Stephen Foster, the father of American music: It’s only fitting that the man who would define the United States’s musical scene was born on our nation’s 50th birthday—July 4, 1826, in Lawrenceville, Pennsylvania, a town near Pittsburgh.
📜 American Essence: Panic, innovation, and the building of America’s first world’s fair: During the country’s 90th year, John Campbell, a professor at Wabash College in Indiana, became the first to officially propose the idea of hosting a world’s fair commemorating 1776.
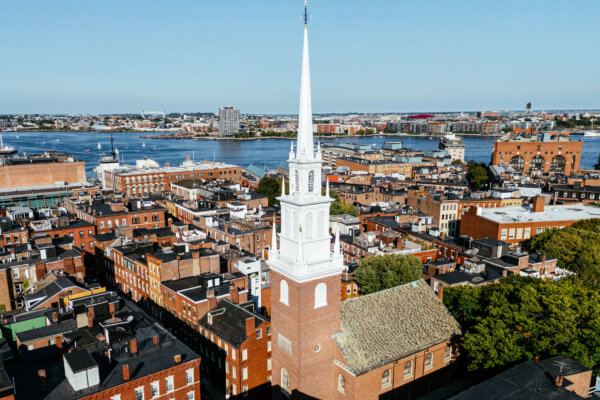
From the Ground Up:250 Years: Old North Church Is the Living Story of America: Best known for its role in the American Revolution, the Christ Church of Boston’s North End neighborhood is still home to a thriving Episcopal congregation. Read more →
FOLLOW US * When sharing an article, giftaccess@TheEpochTimes.com is added to the list of recipients. If your friend is not already a subscriber, we will send them a special link for free access to the article.
Manage your email preferences here or unsubscribe from Bright here.
Today we received miraculous news from Brophy teacher Mike Welty ’83 regarding his daughter Mary Welty (XCP ’12). After suffering a serious medical emergency earlier this week, Mary is currently awake and showing strong signs of recovery. Please continue to keep Mary and her family in your prayers, they are grateful for the support and love of the Brophy and Xavier communities.
A landmark Cooperative Research and Development Agreement (CRADA) with the U.S. Navy has served as the ultimate institutional validation for Odysight.ai (NASDAQ: ODYS), sending shares into a volatile, high-volume surge.
The deal centers on deploying Odysight.ai’s advanced visual sensing and artificial intelligence (AI) platform for condition-based maintenance on mission-critical aircraft carrier arresting cables.
While the market initially reacted to the headline, the core investment thesis appears to be anchored by a much deeper fundamental story: a rapidly monetizing $13.8 million backlog and a pristine, zero-debt balance sheet. As global defense budgets aggressively pivot toward predictive maintenance and operational readiness, this de-risked micro-cap may offer an asymmetrical entry point before its technology scales fleet-wide.
Why This CRADA Is a Game-Changer
The CRADA with the Naval Air Warfare Center Aircraft Division Lakehurst (NAWCAD) is much more than a run-of-the-mill supply contract. For a micro-cap like Odysight.ai, it represents a deep, formal collaboration that embeds its technology at the heart of the Pentagon’s modernization efforts. This partnership provides invaluable, real-world operational feedback, allowing Odysight.ai to refine its algorithms and hardware in one of the world’s most demanding environments.
This direct line to the end-user significantly de-risks future product development and provides a powerful competitive moat. Successfully proving the technology on carrier arresting cables, a system under immense and constant operational stress, is a strategic masterstroke.
It provides Odysight.ai with an unimpeachable case study to leverage for expansion into other mission-critical systems. This validation establishes a clear, logical pathway for scaling across the U.S. Navy’s fixed-wing aircraft, rotary-wing helicopters, and ground vehicle fleets. This approach mirrors a successful pattern of securing contracts with elite military operators worldwide. Odysight.ai has already logged key operational milestones with the Israeli Air Force for its SH-60 helicopter program and the Italian Air Force for AW139 platform testing. These engagements cement the system’s interoperability and establish Odysight.aias a trusted partner within premier international defense supply chains, not just a vendor.
Why Zero Debt and a $13.8M Backlog Matter
Many pre-profitability technology sector companies are hamstrung by weak balance sheets and the constant threat of dilutive financing. Odysight.aistands in stark contrast to this narrative. The technology developer exited its 2025 fiscal year with approximately $26 million in cash and equivalents and, critically, zero long-term debt. This robust liquidity profile is a powerful strategic asset. It provides a multi-year operational runway, granting management the flexibility to execute its pilot programs and scale production without the immediate pressure to tap equity markets. This financial independence allows Odysight.ai to negotiate from a position of strength and focus entirely on technological and commercial execution.
This financial stability is supercharged by exceptional revenue visibility. Odysight.aiis currently working through a contracted backlog of $13.8 million. This figure, representing more than 4.5 times Odysight.ai’s trailing 12-month revenue, signals a fundamental inflection point. Odysight.ai is transitioning from a speculative research-and-development entity into a commercial-stage enterprise with a clear path to accelerated growth. The successful monetization of this backlog throughout 2026 will be the key performance indicator for investors. Consistent conversion of this backlog to top-line revenue could trigger a significant re-rating of the stock, as the market shifts from valuing potential to rewarding proven execution.
The Market’s Volatile Reaction
The Navy CRADA announcement on May 11, 2026, served as a powerful market catalyst, igniting a trading firestorm. Shares of Odysight.ai saw volume surge to 39.12 million, an increase from its daily average of just under 470,000. This surge propelled the stock to an intraday high of $11.30 before aggressive profit-taking sent it to $4.75 by the closing bell.
This extreme price action, which triggered a Limit Up-Limit Down (LULD) trading pause, confirms that both retail momentum traders and institutional algorithms have now firmly fixed their sights on the equity. While the sharp retracement highlights near-term volatility, the record volume and elevated close signal a permanent shift in market awareness.
Aiding this newfound market interest is a shrewd strategic move to enhance liquidity and broaden the shareholder base. On April 9, 2026, Odysight.aifinalized a dual listing on the Tel Aviv Stock Exchange (TASE). This provides direct access to a deep pool of sophisticated regional institutional capital. This investor base has a nuanced understanding of the defense technology sector and is well-positioned to appreciate the long-term value of Odysight.ai’s contractual milestones, potentially creating a more stable valuation floor for the stock moving forward.
From Pilot to Profit: What to Watch for Next
The path forward for Odysight.ai hinges on execution. While the current analyst consensus rating is a Hold, this is common for a company at its commercial inflection point. The recent Moderate Buy rating and $10 price target from Benchmark Co. suggest that some on Wall Street are beginning to price in the successful execution of the current backlog and the immense scalability of the Navy partnership. The key metric for investors to monitor will be the rate at which the $13.8 million backlog is converted into recognized revenue in the coming quarterly reports. A consistent, sequential increase will validate the entire commercial model.
Furthermore, any announcements of follow-on contracts stemming from the NAWCAD pilot program would serve as a powerful upside catalyst, confirming the land-and-expand strategy. While Odysight.ai appears financially well-positioned to withstand near-term headwinds, investors should remain cognizant of the inherent risks of any micro-cap investment, including customer concentration and the operational challenges of scaling production to meet enterprise-level demand. For investors with a higher risk tolerance and a focus on disruptive defense technology, Odysight.ai offers a de-risked ground-floor opportunity. More conservative market participants may prefer to see a few quarters of consistent backlog conversion before committing capital. READ THIS STORY ONLINE
Banzai International (NASDAQ: BNZI) posted full-year 2025 revenue of $12.2 million, up 169% year-over-year, with Q4 growth of 116% and gross margins expanding to 81.9% – signaling a high-efficiency SaaS model gaining traction.
With over 150,000 customers, a planned acquisition of ConnectAndSell expected to add roughly $15 million in annual revenue, and a recent Zacks Rank No. 2 Buy upgrade, institutional confidence in BNZI’s improving fundamentals is building. Technical indicators also suggest a potential bottom formation.SEE WHY ANALYSTS ARE WARMING UP TO THIS AI MARTECH TURNAROUND PLAY
When an aerospace upstart’s next-generation BlueBird satellites are the largest commercial communication arrays to ever be deployed in low Earth orbit (LEO), expectations for that company can be astronomical.
So when space-based cellular broadband network provider AST SpaceMobile (NASDAQ: ASTS) reported Q1 2026 results on Monday, May 11, investors were understandably deflated by a bearish double-miss.
In the lead-up to the earnings call, which was held after the bell, ASTS gained nearly 6%. But after announcing dramatic misses on earnings and revenue, the stock sold off during after-hours trading as the market’s palpable disappointment resulted in a loss of more than 13%.
Here’s what investors need to know about the SpaceX rival going forward.
AST SpaceMobile’s Q1 Disappointment Brings Investors Back Down to Earth
Despite the company’s promising backdrop, the space-based cellular provider posted Q1 earnings per share(EPS) of negative 66 cents versus analyst expectations of negative 23 cents.
The EPS miss was AST SpaceMobile’s fifth in as many quarters.
Quarterly revenue also disappointed, with $14.74 million missing the consensus mark of $39.01 million by a country mile. That was particularly magnified when looking at the company’s Q4 2025 revenue of $54.31 against expectations for $39.53 million.
Fortunately, the Q1 report wasn’t without its highlights. AST SpaceMobile reported a healthy balance sheet with approximately $3.5 billion in cash, cash equivalents, and restricted cash as of March 31.
The company is still in its nascent stages of revenue generation, but it should be able to continue seamlessly scaling thanks to more than half a million square feet of manufacturing and operations space around the globe. BlueBird 8, 9, and 10 are expected to be delivered within a month, and AST SpaceMobile is in the process of assembly through BlueBird 33. Ultimately, the firm plans to have 100 BlueBird satellites in its fleet.
In his earnings call comments, CEO Abel Avellan highlighted the company’s 95% vertically integrated manufacturing strategy, noting how it provides a long-term advantage with its manufacturing team ramping up significantly over the past several quarters.
AST SpaceMobile’s Volatility Should Be Expected
AST SpaceMobile has dealt with its fair share of setbacks this year. Launch delays and Blue Origin deployment mishaps have resulted in heightened volatility in share prices. As a result, ASTS now carries a beta of 2.60, meaning it is more than two and a half times as volatile as the broad market.
But with high betas come high risk-reward opportunities. Shortly after the BlueBird 7 LEO failure in late April, the stock bounced back within a week on news that the U.S. Federal Communications Commission granted AST SpaceMobile commercial authority to deliver direct-to-device, or D2D, cellular broadband connectivity from outer space nationwide in the United States.
According to a company press release, AST SpaceMobile entered into an agreement with the United States Space Development Agency for the Europa Track 2 Commercial Solutions program as part of “the Hybrid Acquisition for proliferated Low-Earth Orbit (HALO) program,” which carries a total contract value of approximately $30 million.
So selloffs are nothing new to shareholders, many of whom have endured the highs and lows of buying and holding ASTS. Over the past year, while compiling a gain of nearly 204%, the stock has seen trough-to-peak gains as high as 315% while enduring at least 15 double-digit pullbacks.
After a Big Earnings Miss, ASTS Receives a Mixed Outlook
The silver lining is that the company’s revenue is expected to continue growing, which should result in earnings nearly breaking even over the next year. Based on a trailing 12-month EPS of negative $1.32, AST SpaceMobile’s earnings are expected to grow from negative 99 cents to negative one cent over the next four quarters.
Nonetheless, analysts are now understandably conservative in their expectations. The stock’s average 12-month price target is $82.51, indicating a potential upside of over 15%. Meanwhile, AST SpaceMobile has a consensus Reduce rating based on the 10 analysts who currently cover it.
Short interest of nearly 18%—or nearly 54 million shares of the 382 million shares outstanding—remains a short-term concern. However, long-term, the smart money appears to remain bullish on ASTS. Over the past 12 months, institutional buyers have injected nearly $3 billion into the stock, while outflows have totaled less than $500 million. READ THIS STORY ONLINE
Mode Mobile – the company turning smartphones into EarnPhones – has posted $115M+ in revenue, 3-year growth of 32,481%, and an ecosystem of 490M+ users. With a Nasdaq ticker ($MODE) secured and Kevin Harrington of Shark Tank among early backers, the company is positioning for a potential IPO.
After getting beaten down for the better part of a year, Axon Enterprise (NASDAQ: AXON) scored a big win after its last earnings report. Shares surged by nearly 11% following the firm’s May release, with the company posting impressive sales, earnings, and guidance.
Nonetheless, the defense stock is down big time, still trading at less than 50% of its 52-week high reached in August 2025. Some of this fall was likely justified, but other aspects are much more questionable.
At past highs, Axon traded at a forward price-to-earnings ratio (P/E) near 130x; evident of a company “priced for perfection.”
However, the stock has also sunk amid fears of artificial intelligence in the software industry. This comes even though hardware sales play a critical role in Axon’s business and make its flywheel effect work.
When push comes to shove, Axon’s results show why there is a lot of room for optimism around this name going forward.
Axon’s Beat and Raise Q1
In Q1 2026, Axon reported revenue of $807.3 million, good for a growth rate of 34% year over year (YOY). This very handily beat estimates of $778.9 million. Meanwhile, adjusted earnings per share (EPS) rose by just under 10% to $1.61, a slight beat over expectations of $1.60. Notably, gross margins took a meaningful hit, leading to revenue growing much faster than adjusted EPS.
Gross margin fell by 150 basis points YOY to 59.1%, with the company noting global tariffs as the primary driver. This is another legitimate factor hurting Axon stock, being a persistent talking point on earnings calls.
Despite this, the company maintained its full-year adjusted earnings before interest, taxes, depreciation, and amortization (EBITDA) margin guidance of 25.5%. Axon also raised its full-year revenue growth guidance to a midpoint of 31%. This is a meaningful boost over past midpoint guidance of 29%, coming as contracted booking growth increased 44% YOY, well above Q1 sales growth. Importantly, Axon is seeing considerable growth from its AI offerings, counteracting the narrative that the technology is a large threat to Axon rather than a tailwind.
AI Growth Soars as Law Enforcement Buys In
Axon’s AI Era plan is its most expensive hardware and software package for law enforcement. Here, bookings rose by 140% YOY, with the company noting that “nearly all large domestic law enforcement agencies are now including AI in their purchases.” That’s a very strong statement, showing that AI is moving to the core of how agencies make purchasing decisions, rather than being a nice-to-have.
Slide 23 of the company’s Investor Deck also illustrates how hardware sales form the basis of the company’s software, services, and AI flywheel effect. In year one of the AI Era Plan, hardware sales represent about half of revenue. This is where the company sells products like tasers, body cameras, virtual reality headsets, and drones.
However, after year one, hardware sales are very minimal. Over a five-year period, the combination of AI and non-AI software and services makes up over 75% of total plan revenue. This includes offerings like Draft One, where AI uses body camera recordings to create a first draft of incident reports, saving officers time on paperwork.
Agencies continue to pay for these services over several years, but they are useful only after first purchasing the necessary hardware. So, while Axon certainly has significant software exposure, its hardware-first model provides protection from AI competition that software-only companies do not possess.
Adding to this is the fact that demand for Axon’s drones is spiking. During the quarter, its counter-drone revenue increased by 300% YOY. Bookings rose considerably more, up 500% YOY, indicating that demand is accelerating.
Axon Continues Its Post-Earnings Success; Markets Remain Unconvinced
Notably, despite recent drops, Axon has continually shown the strength of its business through financial results. Following its past 10 earnings releases, Axon has seen an average post-earnings gain of approximately 12%. That is a feat investors would be hard-pressed to find in many other stocks.
Surely, past post-earnings success does not mean it will continue. However, it is evidence of one thing: the market has repeatedly underestimated Axon and then corrected after the company provides numbers that it cannot deny. It’s arguable that the same thing is happening now, given the stock’s massive decline and post-earnings jump.
Furthermore, much of Axon’s price action continues to coincide with the price action of the overall software market. This indicates that investors have yet to separate Axon from software stocks, despite the significant differences in its business model.
Analysts continue to have a positive outlook on Axon. The MarketBeat consensus price target sits near $713, implying upside north of 75%. Targets updated after the company’s earnings report are considerably lower, averaging around $604. However, this figure still implies substantial upside of just over 50%. READ THIS STORY ONLINE
A publicly traded peptide company just signed an exclusive partnership with a NYSE-listed MMA media platform tied to Conor McGregor and Dana White – reaching millions of combat sports and biohacking followers worldwide.
On April 15, RFK Jr. announced the FDA would remove 12 peptides from restricted Category 2 status. This company was already selling products tied to three of those peptides – and has developed a patent-pending transdermal patch addressing the 63.2% of adults with needle phobia. The peptide therapeutics market is projected to reach $294 billion by 2033.READ THE FULL REPORT ON THIS SMALL-CAP PEPTIDE COMPANY NOW
The Night Owl is a financial newsletter that provides in-depth market analysis on stocks of interest to individual investors. Published by MarketBeat and Early Bird Publishing, The Night Owl is delivered around 9:00 PM Eastern Sunday through Thursday. If you give a hoot about the market, The Night Owl is the newsletter for you.




 🌿 Keep your wellness inspiration flowing —