I Spent Three Days On the Ground in Costa Rica

View in browser

“Costa Rica isn’t a real estate story. It’s a scarcity story.”

Karim Rahemtulla, Co-Founder, Monument Traders Alliance 

Karim Rahemtulla

Dear Reader,

Just over a week ago, I flew to Costa Rica.

And before you roll your eyes, yes, it was for work. I’m a lucky guy, what can I say?

But three days on the ground with a pair of international real estate scouts from Ronan McMahon’s Real Estate Trend Alert (RETA) team was, in fact, work.

We toured multi-million-dollar properties in master-planned communities modeled after Italian hill towns.

We also visited new project sites you won’t find by searching online.

I noticed the golden-sand beaches were busy in what was supposed to be the “off-season”.

Safe to say, Costa Rica is the place to be right now.

I didn’t just come back with a tan and post-trip depression…

I came back with a sharper perspective on international real estate.

Most people think of Costa Rica as a lifestyle destination. Beaches, surf towns, vacation homes.

Ronan looks at these markets the way I look at fundamentals on a company’s balance sheet.

He looks for constrained supply, infrastructure shifts, rising demand, pricing disconnects, and asymmetric upside.

What I saw on the ground confirmed what his team has been reporting for some time.Costa Rica isn’t a real estate story. It’s a scarcity story.

And one specific market is the last real chance to own true beachfront property in the country.

The 1977 Law That Took 95% of the Beachfront Off the Table

In 1977, Costa Rica passed the Maritime Zone Law. In plain English, it took the first 200 meters of every beach in the country and put it under government control.

The first 50 meters are public. Nobody can own them. The next 150 meters are leased to private holders through 20-year government concessions, not sold.

That means only 5% of Costa Rica’s oceanfront is titled freehold. The kind of ownership Americans take for granted at home, where land can be freely sold, inherited, or mortgaged.

The other 95% is leasehold from the government, with all the restrictions that implies.

And the small slice that is titled? It almost always lands in the hands of luxury hotel chains like the Four Seasons, the Ritz-Carlton Reserve, the Andaz, and the Waldorf Astoria. These are the players that can afford to develop the rare freehold parcels.

A retail buyer almost never sees a true titled beachfront deal in Costa Rica. The ones that do exist sell for prices that only make sense for a hotel operator with branded residences.

That’s the supply side of this market.

Now Look at the Demand Side

While the supply has been legally capped for nearly half a century, the demand has been quietly accelerating.

Costa Rica’s tourism arrivals just crossed 1.9 million through the early part of this year.

Direct flights now run into Liberia (the country’s Pacific airport), from Seattle, San Francisco, Boston, Philadelphia, and a dozen other U.S. cities.

The drive from the airport to the coastal resorts that used to take three and a half hours now takes thirty minutes on new highway infrastructure.

The country is no longer remote. It’s a four-hour flight from the East Coast.

And the money is following the access.

The development next to where I stayed in Las Catalinas is being built by Steve Case, the founder of AOL.

The homes around it are selling for $2 to $15 million. Those are U.S. prices… in Costa Rica.

When the guy who built one of the biggest tech companies of the 1990s is putting his own capital into the same Pacific coast you used to need a four-wheel-drive to reach, you are not looking at a speculative bet.

You are looking at a transformation that is already happening.

SPONSORED

Media Won’t Report This 40% Market Crash Prediction

Former CIA insider, Jim Rickards warns of a market implosion that could hit any day now..

Learn how to safeguard your money from this threat before it’s too late.

The One Exception Ronan Just Secured

Most people get this market wrong from the start.

If you fly down cold and start looking at houses on the open market, you are paying the prices I just told you about.

$2 million on the low end, $15 million on the high end of a normal range, not the outliers.

That’s the dumb way to do this.

The reason I flew down with Ronan’s team is that RETA works the other side of this market.

RETA scouts properties two and three years before the broader money arrives, negotiates group-buying power on pre-construction projects, and gets members in at prices not available to a retail buyer walking off the plane in flipflops.

The track record speaks for itself. RETA members have been making returns of 60%, 70%, and sometimes 90% on properties over the last few years.

Lots near Ojochal doubled in seven years. Two-bedroom homes near Playa Flamingo went from $286,800 to $500,000 in just 17 months.

And right now, the team has secured something exceptionally rare.

A titled true beachfront project on a 2.5-mile stretch of beach in Jacó, the closest beach town to Costa Rica’s capital, San José. About an hour from the airport on the Caldera Highway.

For years, Jacó was known mostly as a laid-back surf destination. That’s changing rapidly.

Luxury development is arriving and higher-end buyers are showing up. Pre-construction condo prices moved roughly 6% in a single quarter earlier this year.

According to Ronan, the new deal his team secured isn’t beach access, isn’t “steps from the beach,” isn’t across the road from the sand.

It is true titled beachfront. Step out from your condo, past your resort-style amenities, and directly onto the sand.

In a country where only 5% of the oceanfront is titled and almost all of it is owned by hotel chains, that’s a category-defining piece of inventory.

The Numbers

I asked Ronan to walk me through what he expects this deal to do over the next several years. His response:

“With this deal, we’ll have a chance to lock in what I believe will be gains of $223,000 just five years after taking the keys. These are luxury condos in a best-in-class true beachfront community. Our condos are going to be in massive demand as rentals. Short-term I’d expect $50,200 a year in gross rental income. That’s a 17% gross yield. And I’m being conservative.”

I have known Ronan for more than 20 years. He’s not the type to blow an opportunity out of proportion. When he says he’s being conservative on a 17% gross yield, that’s the floor of what he expects, not the ceiling.Logo

YOUR ACTION PLAN

This Tuesday, May 19, @ 2 p.m. ETRonan is joining me inside Monument Traders LIVE.

We are going to walk through what I saw on the ground, the specific Jacó deal, the numbers behind it, how RETA negotiates off-market pricing for its members, and how this particular project came together.

Ronan is also going to open this deal to attendees of the session. That part is unusual. Normally these projects are reserved for paying RETA members only.

If you’ve been thinking about diversifying trading profits into international hard assets, this is the right conversation to be in the room for.

ADD THIS EVENT TO YOUR CALENDARWant more content like this?


FUN FACT FRIDAY

Costa Rica saw a whopping 660% spike in residency applications year-over-year recently, catapulting it into the top four global residency programs favored by Americans.

This residency boom (tied to its “pure life” lifestyle, stability, and incentives) is supercharging real estate growth.

It’s drawing high-net-worth individuals and expats, with projections for a net influx of over 350 HNWIs in 2026 alone, bringing roughly $2.8 billion in investable assets.


INSIGHTS YOU MAY HAVE MISSED

I Spent Three Days On the Ground in Costa Rica

Are You Holding the Next Cisco?

While the Market Lost Its Mind, We Got Paid

Nobody’s Calling This An AI Stock

SPONSORED

Can You Spot The Spike?

If so… you could spot BIG earnings moves… BEFORE they happen…

And target 293% in less than 24 hours…

If the stock moves up OR down… these trades win BIG!

Discover The Pre-Earnings SpikeMonument Traders Alliance

Monument Traders Alliance, LLC

You are receiving this email because you subscribed to Trade of the Day.
To unsubscribe from Trade of the Day, click here.

Questions? Check out our FAQs. Trying to reach us? Contact us here.
Please do not reply to this email as it goes to an unmonitored inbox.

To cancel by mail or for any other subscription issues, write us at:
Trade of the Day | 14 West Mount Vernon Place | Baltimore, MD 21201
North America: 800.507.1399 | International: +1.443.353.4977
Website | Privacy Policy
Keep the emails you value from falling into your spam folder. Whitelist Trade of the Day.

© 2026 Monument Traders Alliance, LLC | All Rights Reserved

Nothing published by Monument Traders Alliance should be considered personalized investment advice. Although our employees may answer your general customer service questions, they are not licensed under securities laws to address your particular investment situation. No communication by our employees to you should be deemed personalized investment advice. We allow the editors of our publications to recommend securities that they own themselves. However, our policy prohibits editors from exiting a personal trade while the recommendation to subscribers is open. In no circumstance may an editor sell a security before subscribers have a fair opportunity to exit. The length of time an editor must wait after subscribers have been advised to exit a play depends on the type of publication. All other employees and agents must wait 24 hours after publication before trading on a recommendation.

Any investments recommended by Monument Traders Alliance should be made only after consulting with your investment advisor and only after reviewing the prospectus or financial statements of the company.

Protected by copyright laws of the United States and international treaties. The information found on this website may only be used pursuant to the membership or subscription agreement and any reproduction, copying or redistribution (electronic or otherwise, including on the world wide web), in whole or in part, is strictly prohibited without the express written permission of Monument Traders Alliance, LLC, 14 West Mount Vernon Place, Baltimore, MD 21201.

REF: 000142349377

Are You Up for This “Money Ladder” Challenge?

Ad Image
TradeSmith Daily logo

Are You Up for This “Money Ladder” Challenge?

VIEW IN BROWSER

Michael’s note: We got a fantastic response yesterday to the launch of Jeff Clark’s first-ever trading challenge.

Jeff is one of our in-house options trading experts. And he’s aiming to harness the big moves we’re seeing in stocks this year – and turn a $5,000 stake into $1 million in 12 trades or fewer.

Think of it like a money ladder. Each rung is a single trade, and the winnings from one trade become the stake for the next – climbing higher with each rung.

More than 3,000 folks tuned in to Jeff’s launch. But there are still slots available to join Jeff and the other Challenge participants.

The odds of hitting $1 million are still low, as Jeff is quick to admit. But as he gets into below, in his 43 years as a trader, he’s seen only a handful of markets this favorable for an attempt like this.

Over to you, Jeff…

BY JEFF CLARK, EDITOR, MARKET MINUTE

The press dubbed it Software-Mageddon.

In January, the AI company Anthropic released a product called Claude Cowork.

It can create software on demand. A small business owner can describe what he wants in plain English and have a working program built for him in minutes.

Wall Street did the math fast. If businesses can create their own software for a couple of hundred dollars of AI subscription fees, why keep paying hundreds of thousands of dollars to the software companies?

The selling was brutal. Over $1 trillion in software market value was wiped out in a matter of weeks. Salesforce (CRM) – which makes the software companies use to keep track of sales – fell 45% from its high.

And it wasn’t alone. The iShares Expanded Tech-Software ETF (IGV)– which tracks dozens of America’s biggest software names – plunged 35% from its September high in just five months.

That’s a faster collapse than most investors will live through more than two or three times in a career.

Every pundit on every financial network was saying the same thing: AI is going to destroy the software industry.

I disagreed.

Not because I’m an expert on the software industry or AI. But because of what the IGV stock chart was telling me.

By Feb. 24, IGV was trading more than 20% below a key trendline called the 50-day moving average. In my 40-plus years of trading, this fund had almost never strayed more than 12% from that line before snapping back.

That morning, I told my Jeff Clark Trader subscribers to buy a call option on IGV. We paid $2.50 a contract.

Seven days later, we sold it for $5.50.

A 120% gain – in one week – on a sector everyone else had given up for dead.

And over the last year, I’ve given my subscribers the chance to make 13 other triple-digit wins and 51 double-digit wins.

Those are the kinds of gains you can make as an options trader during the disruptions we’re seeing in today’s market.

It’s why I’m so excited about that 12 Trades to $1 Million trading challenge I launched yesterday. These are ideal conditions for an options trader like me.

Recommended Link

Navellier Warns: This Could Leapfrog Elon’s SpaceX IPO

Elon Musk could take SpaceX public in 2026, at an estimated $1.75 trillion valuation. The IPO would include Elon’s AI model, Grok. But according to Louis Navellier, a radical new AI model will launch this year… over 1,000 times more powerful than Elon’s. And the company behind it could outperform SpaceX in the process. Click here for full details (including Louis’ new pick – free).

This Is Not a Normal Market

The kind of move we saw in IGV doesn’t happen in a normal market.

In a normal market, a sector ETF doesn’t fall 35% in five months on the back of a single product announcement. Stocks don’t reprice 20% or 30% in a single session. Companies that should be steady don’t start moving like speculative small caps.

But this isn’t a normal market. 

In a slow, grinding bull market, the kind of mean-reversion trade I took on IGV is hard to find. Stocks drift higher in a steady line. The rubber band never stretches far enough to snap. Most of my trades, in those years, are quiet doubles on quiet setups.

But in a disruption window – when stocks are moving 20% in a session and sectors are repricing overnight – the rubber band stretches far. And when it snaps back, it snaps back hard and fast.

That’s why I’ve issued the first-ever trading challenge of my career.

It’s built around the idea of a “money ladder.” We’ll start with a $5,000 stake. Then we’ll try to turn it into $1 million in 12 trades or fewer.

Low Odds, But Not Impossible

As longtime readers will know, this isn’t how I typically trade.

I’m a conservative, low-risk trader. I use options to generate income and to make low-risk speculations. I like to take my profits off the table rather than letting them ride. This strategy has kept me in the options game for more than four decades.

There aren’t many options traders who can claim that sort of longevity. And, it is mostly due to my conservative style of trading.

But one of my team members recently went through the track record of my newsletter recommendations. And across nine years and 381 closed trades, there were 36 separate streaks of three or more winning trades in a row. Twenty-one of those streaks ran five trades or longer. Eight ran for eight trades or more.

And on two occasions, the streaks were long enough that – if you’d rolled a $5,000 stake from one trade into the next – you would have crossed the $1 million mark.

The first was during the 2023 banking crisis. Nine trades that could have turned $5,000 to $1.3 million with a rollover strategy.

The second was during the AI repricing of 2025. Twelve trades that could have turned $5,000 into $2.6 million.

The timing of those two streaks wasn’t a coincidence. On both occasions, market conditions looked a lot like what we’re seeing right now: high volatility, broken assumptions, stocks moving 20% or 30% in a single session, sectors getting repriced overnight as the rules of normal investing temporarily stopped applying.

The odds are still low of hitting $1 million. I want to be clear about that.

Even in the best conditions I’ve seen in four decades, this requires favorable markets, disciplined execution, and some luck. Any trading carries real risk of loss. The money you use for the challenge should not be money you rely on to put food on the table.

But for the right person with a few thousand dollars they can afford to lose, it’s worth a real attempt.

Here’s How We’ll Scale the Money Ladder

Like I said, I’m recommending challenge participants start with $5,000. But if $5,000 feels too steep, you can do this challenge with $500 or even $200.

Here’s how it works. Whatever you put into the first trade, we attempt to double it. We’re aiming for a 100% gain on each option trade.

So if you start with $500, it becomes $1,000. Then we exit that trade and move to the next one. The downside is that if we lose 50% on any given option position, we exit the trade as well.

We never want the entire account exposed to one position, and we never want to hit zero. So if we put $5,000 into the first trade and it gets cut in half, we’re down to $2,500 and we exit immediately.

Then we move to the sidelines and look for another opportunity.

Yes, there will be times when we cut a loss at 50% and the trade later reverses in our favor. That’s going to happen. But we can’t focus on hindsight.

The rules are simple – we enter an option trade, and if it doubles, we exit. If it gets cut in half, we exit.

If we’re correct and the trade doubles, that means we can lose two trades for every one winner and still break even. That’s a 33% win rate. Historically, we’ve done much better than that in my services over time, so I like the odds of this working in our favor.

I expect we’ll have the first trade recommendation out within the next few days. I’m waiting for a setup that I believe is a no-brainer before we jump in.

I’m not going to force these recommendations. If we sit in cash for a while, I’m perfectly okay with that because I want this challenge to be something we can look back on six months from now and say, “What a fantastic run that was.” Not only because we made money, but because we learned a lot, too.

I’m excited about what’s ahead over coming weeks and months as these disruptions roll on.

You can check out the full details of my challenge and how you can participate here.

Best regards and good trading,

Jeff Clark signature

Jeff Clark
Editor, Market Minute

Matthew 5:38-39 – Jesus Teaches Turning the Other Cheek: A Lesson on Non-Retaliation

Having trouble reading this email? View it in your browser. 

Share this on Facebook
Pinterest
View as PDF

Matthew 5:38-39

(38) “You have heard that it was said, ‘An eye for an eye and a tooth for a tooth.’ (39) But I tell you not to resist an evil person. But whoever slaps you on your right cheek, turn the other to him also. 
New King James Version   Change email Bible version

Some may have taken the Old Testament guideline (see Exodus 21:23-25) in a literal fashion. At first glance, it seems that, if a person’s tooth or eye were lost in a scuffle or accident, the one who caused the loss to happen would be required to forfeit his own tooth or eye. Though some may have demanded this in times past, it is clearly not God’s intent for the law. Instead, it is a principle, given in concrete, understandable terms, that damage is to be justly compensated.

According to commentator Adam Clarke, the Jews of Christ’s day abused this law to extract every last penny from another, and in the majority of cases, there was no mercy shown. Human nature being what it was then, and still is now, they insisted that the one who caused the problem receive every bit of punishment coming to him. In short, they wanted and exacted revenge! Jesus wants us to understand that His disciples are not to act this way.

In countering the faulty understanding of this Old Testament law, Jesus teaches, “But I tell you not to resist an evil person. But whoever slaps you on your right cheek, turn the other to him also” (Matthew 5:39). He begins by instructing us not to escalate the situation by stubborn resistance or, worse still, by perpetrating an additional offense. Elsewhere, Paul writes, “Repay no one evil for evil” (Romans 12:17). If offended, do not offend in return. If injured, do not inflict an injury in payment. In other words, retaliation is not the answer.

Note that Jesus is not speaking of dangerous situations, like facing a robber with murderous intent or a rapist on a dark street. On His mind are circumstances of daily life that are insulting, bothersome, or even mildly injurious, but not life-threatening. The Interpreter’s Bible comments on the latter half of the verse: “A blow with the back of the hand to the right cheek was an insult, thus the palm of the hand was now poised to bring a blow to the left cheek.” The blow is struck contemptuously rather than homicidally.

In a situation like this, the first thing that comes to most minds is revenge. Jesus desires that, rather than avenging oneself and acting with the same attitude of hatred as the aggressor, we reflect our calling and suppress the urge to seek vengeance. We should even be willing to take a second slap, this one from the other’s open hand, without retaliation. Such pacifism usually pours cold water on the situation, avoiding further tit-for-tat retribution.

— John O. Reid

To learn more, see:
Go the Extra Mile

Topics:

Responsibility, Sense of

Retribution

Tooth for a tooth

Commentary copyright © 1992-2026  Church of the Great God
New King James Version copyright © 1982 by Thomas Nelson, Inc.

Facebook

 ‌

Instagram

 ‌

YouTube

 ‌

Spotify

 ‌


Subscription Information

This daily newsletter was sent to you at pahovis@aol.com because you subscribed at www.bibletools.org on Jan 30, 2011.

Email Preferences  |  Unsubscribe

Church of the Great God
P.O. Box 471846
Charlotte, NC 28247
803-802-7075

About The Berean | Archives | Random Berean | Subscriptions

🌎 Fermi Downgraded, Cisco Systems Upgraded, Solventum Initiated and more…

Ratings changes for Bandwidth, Cipher Mining, Cisco Systems, Marriott International, Applied Materials, Applied Materials, Fermi and more…Upgrade to MarketBeat All Access to get our best stock ideas, proprietary research, portfolio monitoring tools, and more.  Start Your Free Trial.

Unsubscribe.

MarketBeat Daily Ratings

VIEW MY PORTFOLIO

MAY 15TH, 2026

Follow MarketBeat on X
Follow MarketBeat on Facebook
Subscribe on YouTube
[Watch] FREE STOCK PICK for Elon Musk’s Starlink SuperIPO
Ticker Revealed: Pre-IPO Access to
The #1 stock to own BEFORE the SpaceX IPO
The AI stocks about to become worthless (and one that isn't)

[Watch] FREE STOCK PICK for Elon Musk’s Starlink SuperIPO (Ad)A little-known stock pick with money-doubling potential over the next year is revealed for free in the first three minutes of a new video. This company is a critical piece of Elon Musk’s fast-growing Starlink technology. It could climb 100 percent or more over the next year as Elon brings Starlink public in what may be the biggest IPO in history. No credit card is required to get the ticker.

WATCH THE FREE VIDEO TO GET THE TICKER TODAY.

Today’s Top Stories

McDonald’s Is the Cheapest It’s Been in Years—Does That Make It a Buy?

BY SAM QUIRKE  |  MAY 15, 2026 08:25 AM

The real SpaceX trade isn’t SpaceX  (Ad)

BY BEHIND THE MARKETS

Be Ready: 3 Upcoming Catalysts Could Drive Oracle to Record Highs

BY THOMAS HUGHES  |  MAY 15, 2026 06:40 AM

2 Ways to Play the Big Pharma Patent Cliff

BY NATHAN REIFF  |  MAY 15, 2026 06:05 AM

NOT buy any SpaceX IPO shares until you read THIS  (Ad)

BY WEISS RATINGS

Palantir’s Critics Are “Right”—But They’re Also Still Wrong

BY CHRIS MARKOCH  |  MAY 14, 2026 09:40 AM

A Quantum Shift: Why Speculative Money Is Ditching AI

BY JEFFREY NEAL JOHNSON  |  MAY 13, 2026 11:00 AM

Is This Palantir's Last Great Wealth Opportunity?

Quick Links

Analyst RatingsMy MarketBeatAccount SettingsMarketBeat All AccessStock ListsStock ScreenerCalculatorsPremium ReportsBest Stocks to Buy in MayTicker Revealed: Pre-IPO Access to “Next Elon Musk” Company (Ad)We’ve found The Next Elon Musk… and what we believe to be the next Tesla. 
It’s already racked up $26 billion in government contracts.
Peter Thiel just bet $1 Billion on it.

👉 UNLOCK THE TICKER NOW AND GET IT COMPLETELY FREE.

Your Watchlist

MANAGE YOUR WATCHLIST AND MONITOR YOUR PORTFOLIO

Apple logo

  Apple Inc. (AAPL)

$297.56 -0.65 (-0.22%)  As of 5/15/2026 9:30 AM ET

Amazon.com logo

  Amazon.com, Inc. (AMZN)

$261.71 -5.52 (-2.06%)  As of 5/15/2026 9:30 AM ET

Alphabet logo

  Alphabet Inc. (GOOGL)

$395.62 -5.45 (-1.36%)  As of 5/15/2026 9:30 AM ET

Meta Platforms logo

  Meta Platforms, Inc. (META)

$613.82 -4.61 (-0.75%)  As of 5/15/2026 9:30 AM ET

Microsoft logo

  Microsoft Corporation (MSFT)

$414.20 +4.77 (+1.17%)  As of 5/15/2026 9:30 AM ET
MANAGE YOUR WATCHLIST

Analysts’ Upgrades

Aveanna Healthcare (NASDAQ:AVAH) was upgraded by Stephens from “equal weight” to “overweight”. They now have a $11.00 price target on the stock. This represents a 41.9% upside from the current price of $7.75.Avita Medical (NASDAQ:RCEL) was upgraded by Lake Street Capital from “hold” to “buy”. They now have a $6.00 price target on the stock. This represents a 27.1% upside from the current price of $4.72.Cisco Systems (NASDAQ:CSCO) was upgraded by HSBC Holdings plc from “hold” to “buy”. They now have a $137.00 price target on the stock. This represents a 19.2% upside from the current price of $114.97.Crane NXT (NYSE:CXT) was upgraded by Northland Securities from “market perform” to “outperform”. They now have a $52.00 price target on the stock. This represents a 28.6% upside from the current price of $40.43.Societe Generale Group (OTCMKTS:SCGLY) was upgraded by Kepler Capital Markets from “reduce” to “hold”. The current price is $15.57.Timken (NYSE:TKR) was upgraded by JPMorgan Chase & Co. from “underweight” to “neutral”. They now have a $130.00 price target on the stock, up from $110.00. This represents a 11.6% upside from the current price of $116.49.
VIEW MORE UPGRADES
The #1 stock to buy BEFORE the June S-1 filing (Ad)When the SpaceX IPO launches, most retail investors will be locked out. The banks, funds, and insiders get in early – while everyone else waits on the sidelines.
But one small infrastructure supplier – a critical piece Musk can’t scale the Colossus network without – is still trading well under institutional radar. A new briefing reveals the name and ticker at no cost.

GET THE SPACEX INFRASTRUCTURE STOCK NAME AND TICKER HERE

Analysts’ Downgrades

Aegon (NYSE:AEG) was downgraded by Morgan Stanley from “overweight” to “equal weight”. The current price is $8.37.Alumis (NASDAQ:ALMS) was downgraded by HC Wainwright from “buy” to “neutral”. They now have a $25.00 price target on the stock. This represents a 10.7% upside from the current price of $22.58.Fermi (NASDAQ:FRMI) was downgraded by Evercore Inc from “outperform” to “in-line”. They now have a $11.00 price target on the stock. This represents a 60.5% upside from the current price of $6.86.Kohl’s (NYSE:KSS) was downgraded by Gordon Haskett from “buy” to “hold”. They now have a $14.00 price target on the stock. This represents a 19.7% upside from the current price of $11.70.StoneCo (NASDAQ:STNE) was downgraded by Citigroup Inc. from “buy” to “neutral”. They now have a $11.00 price target on the stock. This represents a 9.7% upside from the current price of $10.03.
VIEW MORE DOWNGRADES
These AI stocks could go to zero. Here’s why. (Ad)Louis Navellier – who manages $1.1 billion including $358 million in AI stocks – says a new AI computer being built at a classified government facility in Tennessee could make today’s leading AI models obsolete overnight. He compares it to the iPhone moment that wiped out Nokia, BlackBerry, and Motorola.
When this machine comes online, it will reportedly accelerate AI breakthroughs 360-fold – compressing five years of progress into five days. Navellier has identified specific stocks he’d sell before this hits, and one ticker he’d buy before May 5th.

SEE THE FULL FREE PRESENTATION WITH NAMES TO BUY AND SELL NOW

Analysts’ New Coverage

Avidity Biosciences (NASDAQ:RNA) is now covered by Leerink Partners. They set an “outperform” rating and a $25.00 price target on the stock. This represents a 89.4% upside from the current price of $13.20.Cellectar Biosciences (NASDAQ:CLRB) is now covered by LADENBURG THALM/SH SH. They set a “buy” rating and a $10.00 price target on the stock. This represents a 216.2% upside from the current price of $3.16.CNB Financial (NASDAQ:CCNE) is now covered by DA Davidson. They set a “neutral” rating and a $34.00 price target on the stock. This represents a 11.9% upside from the current price of $30.39.Devon Energy (NYSE:DVN) is now covered by Evercore Inc. They set an “in-line” rating and a $54.00 price target on the stock. This represents a 13.0% upside from the current price of $47.79.Eastern Bankshares (NASDAQ:EBC) is now covered by DA Davidson. They set a “buy” rating and a $24.00 price target on the stock. This represents a 23.4% upside from the current price of $19.45.Orrstown Financial Services(NASDAQ:ORRF) is now covered by DA Davidson. They set a “neutral” rating and a $41.00 price target on the stock. This represents a 14.0% upside from the current price of $35.97.Solventum (NYSE:SOLV) is now covered by Wedbush. They set an “outperform” rating and a $94.00 price target on the stock. This represents a 25.4% upside from the current price of $74.97.J. M. Smucker (NYSE:SJM) is now covered by Evercore Inc. They set an “outperform” rating and a $117.00 price target on the stock. This represents a 17.8% upside from the current price of $99.34.Unity Bancorp (NASDAQ:UNTY) is now covered by DA Davidson. They set a “buy” rating and a $68.00 price target on the stock. This represents a 29.1% upside from the current price of $52.68.
VIEW MORE NEW COVERAGE
GET 30 DAYS OF MARKETBEAT ALL ACCESS FREESign up for MarketBeat All Access to gain access to MarketBeat’s full suite of research tools:

  • Best-in-Class Portfolio MonitoringView the latest news, buy/sell ratings, SEC filings and insider transactions for your stocks. Compare your portfolio performance to leading indices and get personalized stock ideas based on your portfolio.
  • Stock Ideas and RecommendationsGet daily stock ideas from top-performing Wall Street analysts. Get short term trading ideas from the MarketBeat Idea Engine. View which stocks are hot on social media with MarketBeat’s trending stocks report.
  • Advanced Stock Screeners and Research ToolsIdentify stocks that meet your criteria using seven unique stock screeners. See what’s happening in the market right now with MarketBeat’s real-time news feed. Export data to Excel for your own analysis. 

START YOUR 30-DAY FREE TRIAL

Thank you for subscribing to MarketBeat!

MarketBeat empowers everyday investors to make better investment decisions by delivering up-to-the-minute financial information and best-in-class market research.

If you have questions or concerns about your subscription, please don’t hesitate to email MarketBeat’s South Dakota based support team at contact@marketbeat.com.

If you wish to opt out or update which newsletters you subscribe to, you can modify your email preferences or unsubscribe from these emails.

© 2006-2026 MarketBeat Media, LLC. 
345 N Reid Place, Suite 620, Sioux Falls, SD 57103. U.S.A..

Today’s Featured Content: [Watch] FREE STOCK PICK for Elon Musk’s Starlink SuperIPO(From Paradigm Press)

Today’s Blessing

Today’s Blessing
May 15, 2026

Gratitude has a way of multiplying what we have — not by changing our circumstances, but by shifting what we’re able to see. Look around today with fresh eyes. There is more here than you’ve been noticing.LOOK WITH FRESH EYES 

Discover Your Path

Today’s Blessing is here to guide you through life’s twists and turns, helping you become the best version of yourself and fulfill your destiny.✨Angel NumbersAngel numbers are divine affirmations from the universe, giving us signs we’re on the right track and that we’re not alone.CONTINUE →🙏Faith MessagesHear stories from around the world that will help motivate and bring positivity to your life’s journey.CONTINUE →💫InspirationEmpowering and inspirational stories. See some of these tips from our friends to set you on the pathway to success.CONTINUE →

You’re always one blessing away from a brighter day… and a bigger life. May these stories, affirmations, prayers, and insights lift your spirits and inspire you to lift others.

Go forth and be blessed!LEARN MORE 

🕊️

Please, Unsubscribe Here to stop receiving these emails

The internet of poop

Follow @FlipboardSee More in The Daily EditionDownload App

The assassin's delusion

The assassin’s delusion The Atlantic · Adam Serwer Violence serves an authoritarian agenda. 

FLIP

Let's redo the math on Ukraine

Let’s redo the math on Ukraine The Bulwark · Brynn Tannehill The deadly arithmetic of Russian casualties may add up to Putin’s defeat. 

FLIP
The deadliest drug

The deadliest drug flipboard.com · STAT Alcohol kills more Americans each year than all other drugs combined. Why does the U.S. ignore its most harmful substance use crisis? 

FLIP
As tick bites surge, conspiracy theories follow

As tick bites surge, conspiracy theories follow grist.org · Zoya Teirstein Where scientists see climate change at work, others see the designs of a global cabal. 

FLIP

Stay informed and inspired!

Download Flipboard to get the latest news and stories on the topics you care about.

The internet of poop

The internet of poop 404 Media · Jason Koebler “I hoarded a large database of something valuable, just not what you expect … 150k stools images.” 

FLIP
Video: How music rewires the human body, in 59 minutes

Video: How music rewires the human body, in 59 minutes bigthink.com · Michael Spitzer Music is at least a million years older than language, yet we still see it solely through the lens of entertainment. 

FLIP
Japan is saving elderly people from 'lonely deaths'

Japan is saving elderly people from ‘lonely deaths’ DW English · Julian Ryall As society changes, many elderly people find themselves isolated. Some are working hard to give them a new lease on life. 

FLIP
What the light knows

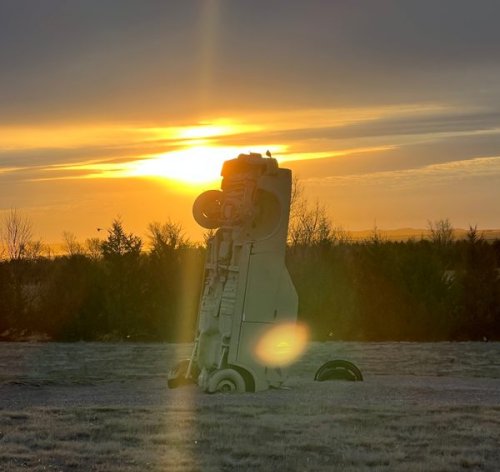
What the light knows Atlas Obscura · Louise Story Since her father’s passing, Louise Story has witnessed an unexplainable ray of light each April — this year, at a handmade Stonehenge in Nebraska. 

FLIP
'Euphoria' star Colman Domingo is suddenly everywhere

‘Euphoria’ star Colman Domingo is suddenly everywhere hollywoodreporter.com · Mia Galuppo From “Michael” to “The Four Seasons,” the consummate character actor is getting all the attention — and setting the terms of his newfound stardom. 

FLIP
Customer loyalty was once measured in Green Stamps

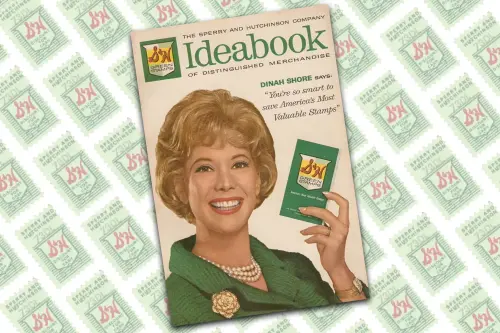
Customer loyalty was once measured in Green Stamps Smithsonian Magazine · Heather Hughes The more you shopped, the bigger the rewards. 

FLIP

Was this sent to you by a friend? For more like it, subscribe here.BLOG · CAREERS · ADVERTISEUpdate your email preferences or unsubscribe here.View our privacy policy here.©2026 Flipboard, Inc. Made with love at 555 Bryant St #352 Palo Alto, CA 94301

🦉 The Night Owl Newsletter for May 13th

UnsubscribeTicker Revealed: Pre-IPO Access to “Next Elon Musk” Company (From Banyan Hill Publishing)

D-Wave Earnings Looked Weak, But Investors May Be Missing This

Written by Nathan Reiff

D-Wave logo overlaying a quantum computing chip.

Earnings season is a pivotal moment for many stocks, but particularly for firms in a fledgling industry like quantum computing. When major player IonQ Inc. (NYSE: IONQ) reported results for the first quarter of 2026 in early May, investors took note of promising revenue growth, a raise to full-year guidance relative to prior projections, and a strong showing in both partnerships and system sales. Still, a crucial piece of the puzzle—profitability—remains missing.

Now, other big names in the pure-play quantum sphere are sharing their own results, including from firms like D-Wave Quantum Inc. (NYSE: QBTS)and Rigetti Computing (NASDAQ: RGTI). D-Wave, known for its sizable cash holdings and recent purchase of Quantum Circuits Inc., stands out for its dual focus on two distinct technological approaches to quantum computing.

Like IonQ, the company noted several compelling developments in its Q1 2026 earnings, particularly in bookings, sales pipeline, and technological advances.

However, top- and bottom-line performance may have contributed to a post-earnings selloff that brought the share price down 7% on May 12, reversing the recent mini-rally initiated in April.

The Bright Spots in D-Wave’s Earnings: Bookings, Recurring Revenue, Sales Pipeline, and More

A number of highlights emerge from a closer look at D-Wave’s first quarter of the new year. Notably, quarterly bookings reached $33.4 million, a record for Q1 and a massive increase of about 2,000% year-over-year (YOY). This figure is impressive on its own, but one of the real strengths here is D-Wave’s major growth to its quantum-computing-as-a-service (QCaaS) business, which climbed by 15% YOY to $1.8 million in revenue. QCaaS positions D-Wave to be able to build recurring revenue into its stream, which could be crucial in its efforts to achieve sustainable profitability. A $10-million enterprise QCaaS agreement from Q1 was a major driving factor here.

The company’s sales pipeline is shining as well, with growth of more than 100% sequentially to Q1 2026. D-Wave sees system sales—the lion’s share of its revenue so far—totaling two or three per year going forward, with at least two projected for 2026. These big-ticket sales do not necessarily mean recurring revenue, but they vastly outsize other revenue streams for the firm at this point.

Technological advances are also crucial for any quantum computing company, and D-Wave highlighted some important ones for the first three months of the year. A standout achievement for the company is its roadmap to 100 logical qubits, a major technological breakthrough, which it believes can be achieved by 2032.

Finally, investors have been waiting for signs as to whether D-Wave has been able to maintain its historically strong cash position. With more than $588 million in cash and equivalents as of the end of the quarter, the company’s reserves remain healthy.

The Reason for the Share Price Decline

It’s difficult for D-Wave to avoid negative headlines for its top- and bottom-line performance in the quarter, despite all of the successes above. Notably, revenue of $2.9 million was down more than 80% YOY and came in about $1.3 million below analyst predictions. Though losses per share beat predictions by 3 cents, they nonetheless widened by 3 cents relative to the prior-year quarter.

A closer look may give long-term D-Wave investors some comfort. Part of the reason for the seemingly-massive revenue slippage is the fact that Q1 of last year saw the sale of a quantum annealing computer system for nearly $13 million. A single transaction can have a major impact on revenue performance, particularly when overall revenue is so low.

Still, that D-Wave is so susceptible to these significant shifts based on the timing of an individual system sale is a reflection of how reliant the company has been on these types of one-off deals. Investors will surely be happy to see the company move toward a more predictable, consistent revenue stream.

Investors in the quantum computing space will need to evaluate whether D-Wave is still a suitable target based on its performance relative to its peers (for one thing, Rigetti announced on the same day that its Q1 2026 revenue roughly tripled YOY to $4.4 million).

The path toward profitability may have become somewhat clearer based on QCaaS performance, but widening losses and the sizable gap between expected revenue and actual performance suggest that there may still be significant ground to cover.

D-Wave shares remain a Moderate Buy, with 14 out of 17 analysts bullish on the stock. READ THIS STORY ONLINE
[Watch] FREE STOCK PICK for Elon Musk’s Starlink SuperIPO (Ad)

[Watch] FREE STOCK PICK for Elon Musk’s Starlink SuperIPO

A little-known stock pick with money-doubling potential over the next year is revealed for free in the first three minutes of a new video. This company is a critical piece of Elon Musk’s fast-growing Starlink technology. It could climb 100 percent or more over the next year as Elon brings Starlink public in what may be the biggest IPO in history. No credit card is required to get the ticker.WATCH THE FREE VIDEO TO GET THE TICKER TODAY.

Nebius Upside Expands as AI Feedback Loop Intensifies

Written by Thomas Hughes

Nebius Group logo displayed on a metal plaque inside a data center with illuminated server racks.

Nebius Group (NASDAQ: NBIS) is another example of a company in an AI-driven feedback loop. The rapid rise of AI infrastructure enables AI model training, which in turn enables inference, outcomes, use cases and increased demand.

Because outcomes tend to be positive, the technology advances with each cycle, strengthening the trend in a potentially indefinite loop. Nebius is well-positioned to benefit, as it provides both the infrastructure for training and inference and tools to support its development.

Nebius’ position was reflected in its recent earnings results, released May 13. The company continues to invest, and, according to CEO Arkady Volozh, unprecedented demand exceeds capacity. This suggests that upcoming results will further sustain the trend of outperformance relative to market expectations, and strength will continue until sufficient capacity is built. Based on the demand trends seen across the AI stack, including GPUs, CPUs, memory, and nuts-and-bolts plays in connectivity and networking, that won’t happen for at least a few years.

Nebius Debt Is a Concern, Offset by Rapidly Expanding Leverage

Nebius’ growing debt is a concern, as it blossomed during Q1, but less so than it was just a quarter ago. The offsetting details include quarterly results showing top- and bottom-line outperformance in Q1 and highly visible evidence that the company can profit at scale. Revenue surged by nearly 700%, outpacing the consensus estimate by several hundred basis points, underpinned by hyperscaler demand.

The impact on margin was significant, with leverage evident across all metrics. Gross margin improved by 2,300 basis points (bps), compounded by high-double-digit declines in R&D, G&A, and expenses margins, which left the company’s bottom line in much better shape than expected. The critical detail is that non-GAAP earnings per share of negative 23 cents outpaced the consensus by 58 cents, offering the market a pleasant surprise.

As concerning as Nebius’ rapid increase in debt may be, it is offset by balance sheet strength, cash flow, and a robust business pipeline. Balance sheet highlights include cash more than doubling, current and total assets rising, and equity increasing despite the increased debt. Debt leverage is also low, at less than 1X, given the more than $9 billion in cash, with the company’s core business experiencing robust demand. The likely outcome is that Nebius will have little trouble servicing its load and paying it off over time.

Nebius can be expected to continue investing, as it plans to deploy up to $20 billion in AI-related capital expenditure (CapEx) this year alone, but its pipeline more than offsets the strength. Deals in Q1 increased the backlog by approximately 250% to 4GW of contracted capacity, underpinned by hyperscalers such as Meta Platforms (NASDAQ: META), which is sufficient to more than double the company’s current-year revenue outlook. Plans now include a new AI factory in Pennsylvania, adding up to 1.2GW of capacity to the rapidly expanding network.

Analysts in Catch-Up Mode, Underpinning NBIS Stock Price Action

The analyst trends are bullish for NBIS, and the company continues to fire on all cylinders, forcing them to respond. As it stands, the trends include increasing coverage, firming sentiment, a 73% Buy-side bias to the Moderate Buy rating, and an uptrend in the consensus price target. 

The only bad news is that price action is outpacing the consensus, setting the stage for a potential price correction. However, given the current trends, price corrections are likely to be buying opportunities, and institutions will be among the buyers.

MarketBeat data reveals institutional ownership at 20% and growing. The group has accumulated on balance every quarter since the IPO, ramping activity sequentially into Q1 2026, and sustaining the bullish tilt in early Q2. The Q1 earnings release provided no reasons to sell, only reasons to hold and build on positions over time.

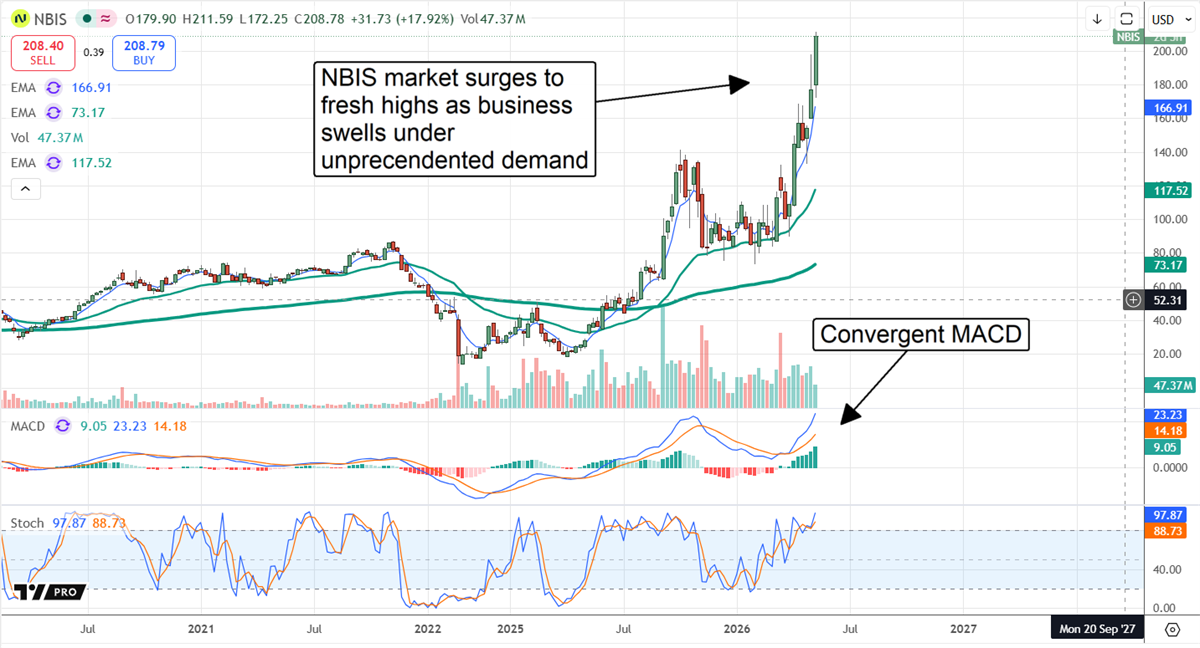
Nebius stock price action is bullish, reflecting a strengthening market with potential to continue accelerating. Signs of strength include the sequentially larger candles formed in late April and early May, as well as the convergence of MACD. 

It shows market momentum is building to record highs and indicates a high probability that higher prices will be set. Technical risks include the stochastic indicator, which signals overbought conditions, but it can remain within its range for weeks and months during bull-market rallies.

NBIS surges as AI demand blossoms.

Catalysts include backing from NVIDIA (NASDAQ: NVDA). NVIDIA pledged $2 billion in funding to assist the data center buildout, promising early and sufficient access to next-generation chips. The deal affirms Nebius’ critical role in the AI infrastructure industry and derisks its outlook. Other catalysts include the company’s operations, which enable cost efficiency, superior performance, and reduced power consumption. READ THIS STORY ONLINE

Ticker Revealed: Pre-IPO Access to “Next Elon Musk” Company (Ad)

Ticker Revealed: Pre-IPO Access to 'Next Elon Musk' Company

We’ve found The Next Elon Musk… and what we believe to be the next Tesla. 

It’s already racked up $26 billion in government contracts.

Peter Thiel just bet $1 Billion on it.👉 UNLOCK THE TICKER NOW AND GET IT COMPLETELY FREE.

Plug Power Flips The Switch On Profitability

Written by Jeffrey Neal Johnson

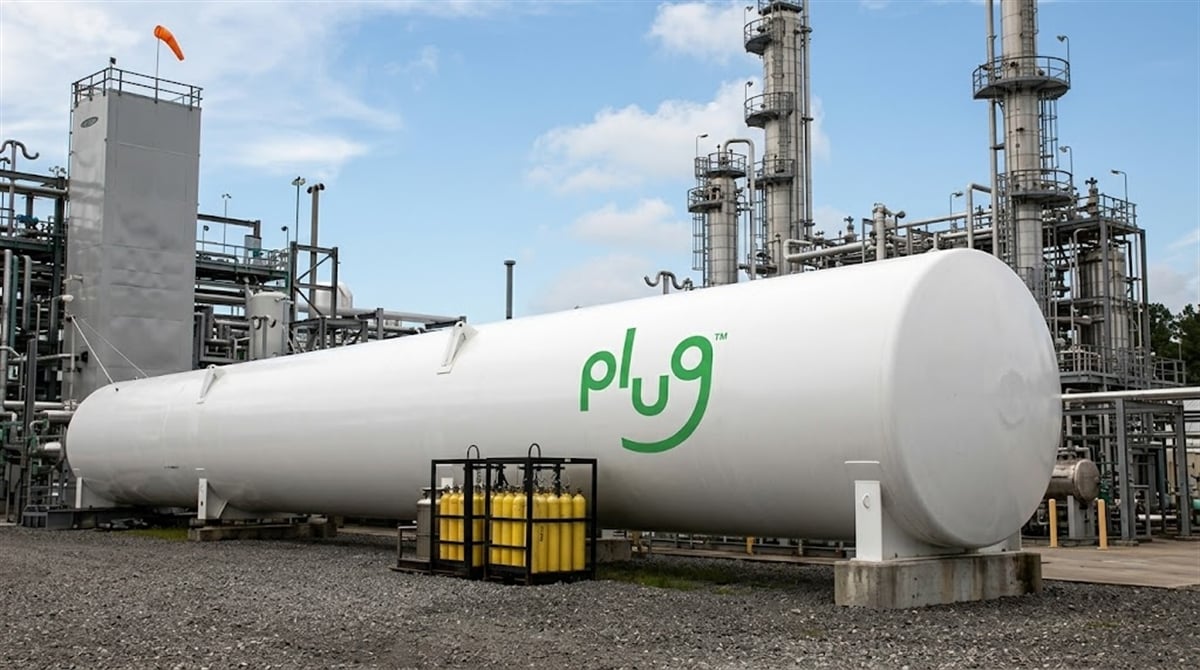
A large white Plug Power storage tank sits at an industrial hydrogen production facility.

A dramatic operational recovery is creating a powerful new narrative in the hydrogen sector. Shares of Plug Power (NASDAQ: PLUG) jumped following its first-quarter earnings report, which signaled a decisive inflection point in its path to profitability.

A 22% year-over-year revenue expansion and significantly narrower losses provided the fundamental firepower, but it was the underlying strategic execution that demanded investor attention. By aggressively expanding margins and fortifying its balance sheet, Plug Power is building a sustainable growth model. This turnaround is not only validating a bullish long-term outlook but also creating immense pressure on the over 24% of the float currently held short.

From Burning Cash to Building a Profit Engine

For quarters, Plug Power’s primary headwind has been severe margin compression, but the latest earnings data shows a sharp reversal of this trend. Gross margin improved by 42 percentage points, moving from a deeply negative 55% in the prior-year quarter to a much more manageable negative 13%.

This change was not an accounting trick but the result of tangible cost-down initiatives. The Project Quantum Leap strategy, first unveiled in 2025, is now bearing fruit, evidenced by a year-over-year reduction of more than 30% in GenDrive per-unit service costs.

Simultaneously, fuel margin rates improved by 54 percentage points, driven by better leverage across the Plug Power hydrogen network and more favorable third-party sourcing contracts. This operational tightening is the core catalyst validating the bullish reversal thesis.

While the headline GAAP earnings per share figure was a loss of 18 cents, this figure includes approximately $140 million in non-cash charges, primarily related to convertible debt and warrant valuations. When these non-operational, market-driven adjustments are excluded, Plug Power’s adjusted EPS stands at a loss of only 8 cents. This figure not only beat analyst expectations of a 9-cent loss but also paints a clearer picture of a business making substantial progress in its underlying economics. The performance reinforces management’s guidance of achieving a positive run rate for earnings before interest, taxes, depreciation, and amortization (EBITDA) by the fourth quarter of 2026.

Funding the Future Without the Dilution Drain

A key concern that has weighed on investors has been Plug Power’s historic cash burn. Management is addressing this head-on with a multi-pronged strategy focused on non-dilutive capital generation, aiming to fund operations through to its positive EBITDA target without harming shareholder value. An expected $275 million is anticipated from hydrogen project asset monetizations, including a key deal with Stream Data Centers. The first transaction from this program, valued at approximately $142 million, is expected to close in June 2026.

In a more immediate cash injection, Plug Power is finalizing the sale of a Section 48 Investment Tax Credit from its St. Gabriel, Louisiana joint venture. This is projected to deliver $39.2 million in proceeds by the end of May 2026, providing a timely liquidity buffer.

Beyond asset sales, Plug Power is targeting internal efficiencies. Management has laid out a plan to reduce elevated inventory levels by at least $100 million in the second half of the year. Successfully executing this supply chain normalization represents another critical, non-dilutive source of capital to fund its growth objectives and further insulate its balance sheet.

Gridlock Is Creating a Green Light

While near-term catalysts are focused on margins and liquidity, a powerful long-term energy narrative is solidifying the business case for hydrogen infrastructure. A growing challenge for large-scale industrial and logistics operations is the strain on local utility grids, exacerbated by the power demands of data centers and widespread electrification.

This problem has created a compelling new value proposition for Plug Power’s on-site solutions. Enterprise clients such as Amazon (NASDAQ: AMZN) and Walmart (NYSE: WMT) are increasingly leveraging GenDrive and GenFuel systems as behind-the-meter power sources. This strategy allows a facility to offload roughly 2 MW of electricity demand from the grid, a significant advantage where utility power is constrained, expensive, or unreliable. This pivot from a simple productivity tool to a mission-critical energy solution represents a massive addressable market.

Disruptions in global energy markets have also renewed interest in energy security and synthetic fuels. This has been a notable tailwind for Plug Power’s electrolyzer business, which saw revenues climb 343% year over year.

While international projects can face regulatory delays, Plug Power is mitigating this risk by diversifying its pipeline and advancing key North American contracts, like the 275 MW engineering design award in Quebec, which fall under a more predictable permitting framework. This domestic focus, combined with the clear demand from enterprise customers for grid independence, provides a stable, growing revenue base to complement the more complex international opportunities.

The High-Voltage Case for Plug Power

The combination of a fundamental business turnaround and a powerful new energy narrative has created a compelling setup for Plug Power. The bull case rests on the continued recovery of margins and on Plug Power’s strategic positioning as a key solution to the modern energy crisis.

As more enterprises face grid-related growth constraints, the demand for behind-the-meter solutions is poised to accelerate, providing a durable tailwind. This robust strategic positioning is what makes the large short interest a secondary, albeit potentially explosive, factor. Each milestone achieved in the turnaround plan makes a bearish thesis less tenable.

The primary risk remains execution, though Plug Power has laid out a clear, multi-faceted plan to manage its cash flow and fund its path to profitability. Should there be any stumbles in the asset monetization timeline, Plugs’ aggressive inventory reduction and the imminent tax credit cash infusion provide significant operational buffers.

For investors, the focus should be on the execution of this strategy. The dramatic improvement in gross margins appears to be the definitive inflection point, suggesting that Plug Power is successfully navigating its transition from a high-growth, cash-burning innovator to a sustainable and profitable energy-tech leader. READ THIS STORY ONLINE

These AI stocks could go to zero. Here’s why. (Ad)

These AI stocks could go to zero. Here's why.

Louis Navellier – who manages $1.1 billion including $358 million in AI stocks – says a new AI computer being built at a classified government facility in Tennessee could make today’s leading AI models obsolete overnight. He compares it to the iPhone moment that wiped out Nokia, BlackBerry, and Motorola.

When this machine comes online, it will reportedly accelerate AI breakthroughs 360-fold – compressing five years of progress into five days. Navellier has identified specific stocks he’d sell before this hits, and one ticker he’d buy before May 5th.SEE THE FULL FREE PRESENTATION WITH NAMES TO BUY AND SELL NOW

More Stories

The Night Owl is a financial newsletter that provides in-depth market analysis on stocks of interest to individual investors. Published by MarketBeat and Early Bird Publishing, The Night Owl is delivered around 9:00 PM Eastern Sunday through Thursday. If you give a hoot about the market, The Night Owl is the newsletter for you.

The Night Owl Newsletter.

View as a Web Page

If you need assistance with your account, please don’t hesitate to contact our U.S. based support team at contact@marketbeat.com.

Unsubscribe

Copyright 2006-2026 MarketBeat Media, LLC. All rights reserved.
345 N Reid Place #620, Sioux Falls, SD 57103-7078. United States..

Read More: [Watch] FREE STOCK PICK for Elon Musk’s Starlink SuperIPO(From Paradigm Press)

Be Still and Know—May Powerlines Newsletter

View this email in your browser

Dear Friend,

Be still and know God invites surrender, not striving harder. In stillness, we lay down control and discover His power, presence, and peace working in us.

Moses: Victory Through Stillness (Exodus 14:14)

At the Red Sea, Israel panicked as Pharaoh’s army closed in. Moses listened to God. Deliverance came not by human strength, but by trust. The sea parted when they stood still and obeyed.

David: Waiting Before the Crown (Psalm 27:14)

David was anointed king but waited years in trials and uncertainty. Though tempted to seize the throne, he trusted God’s timing. His greatness was restraint, not ambition. The crown came in God’s time, without regret, as God’s doing, not his own.

Joseph: Trusting God in the Silence(Genesis 50:20)

Betrayed, enslaved, falsely accused, and imprisoned, Joseph waited in silence. Yet he stayed faithful, trusting God was at work. In time, God raised him from prison to the palace, using his long waiting to save a nation and fulfill His purpose.

Jehoshaphat: Surrender Before the Battle(2 Chronicles 20:12)

When King Jehoshaphat faced a great enemy, he prayed and trusted in God rather than rushing into battle. As the people worshiped, God fought for them. Victory came not through strength, but surrender. Sometimes the most powerful step forward is stillness before God.

A Special May Invitation: Be Still and Know Bundle

Stillness is hard, yet God invites us to trust Him. As we slow down, we see His work. This Mother’s Day, we honored women who nurture us and remember to rest in His presence.

At Hour of Power, we share the strength God provides through our outreach—partner with us by requesting the Be Still and Know Mug. Each sip is a gentle reminder of Psalm 46:10, perfect for moments of prayer, reflection, or quiet devotion.

God loves you and so do I,

Bobby Schuller

P.S. Click here to read inspirational messages in this month’s issue of Powerlines Newsletter. 

Copyright © 2026 Hour of Power, All rights reserved.
Hour of Power email list

Our mailing address is:
Hour of Power
P.O. Box 100
Garden Grove, CA 92842

This email was sent to pahovis@aol.com
why did I get this?unsubscribe from this listupdate subscription preferences
Hour of Power · P.O. Box 100 · Garden Grove, CA 92842 · USA