These Blue-Chip Bonds Are Trading Like Junk

Stansberry Research Logo
Stansberry Digest

Delivering World-Class Financial Research Since 1999

Editor’s note: Don’t miss your chance to profit…

The past few years of high interest rates have turned the credit market on its head. As a result, the bonds of blue-chip businesses are trading at a massive discount.

But according to Rob Spivey – director of research for our corporate affiliate Altimetry – that likely won’t be the case for much longer. And it’s creating a rare opportunity for investors who are paying attention…

In today’s Masters Series, originally from the October 31 issue of the Altimetry Daily Authority daily e-letter, Rob details how you can position yourself to profit from this market shift…


These Blue-Chip Bonds Are Trading Like Junk

By Rob Spivey, director of research, Altimetry

Investors love to sit where the grass is greenest…

When interest rates were near zero, long-term corporate bonds traded near face value – also called “par” ($1,000). Some even climbed above par for a time.

Folks were hungry for stable income. They jumped at the prospect of earning 5% or more through bonds issued by blue-chip businesses. There was just no other way to lock in those kinds of returns for a decade-plus.

But when the Federal Reserve started driving rates higher in 2022, those same long-dated bonds were suddenly worth less on paper.

Even the biggest, safest companies on Earth pale in comparison with the U.S. government. It’s bigger… has more money… and is all but guaranteed to keep chugging along.

So when short-term U.S. Treasurys started yielding as much as long-term corporate debt, the choice was obvious.

Investors fled to shorter-term debt… pushing prices down even though the underlying credit quality didn’t change. And bonds are still cheap today.

But as we’ll explain, that likely won’t be the case for much longer. And it’s creating a rare opportunity for the folks who are paying attention…
Recommended Links:

‘Tech Stock’ Potential With ‘Treasury Bond’ Risk

Top experts call this both a “port in the storm” and their No. 1 recommendation of 2026. It’s a group of opportunities that could DOUBLE in the next year – with a risk profile like buying Treasurys. (Some think even better.) It’s only possible because of a rare anomaly that could disappear within weeks. Today, our corporate affiliate Altimetry is breaking the story. Get the details here while there’s still time.


Don’t Ignore This New Wall Street Warning for 2026

Fifty-year Wall Street legend Marc Chaikin, founder of our corporate affiliate Chaikin Analytics, called the 2022 bear market, the 2023 bank failures, the 2020 crash, and the 2025 tariff tantrum – all in advance. In light of the recent volatility, he’s now stepping forward to warn of a “violent market shift” headed straight for U.S. stocks in early 2026. Here’s how to prepare.


Interest rates are still high relative to history…

And bond prices – as measured by the Vanguard Total Bond Market Index Fund (BND) – are close to their lowest levels of the past decade.

Take a look…

You can see in the chart that bonds are trading at much lower prices, on average, because of higher interest rates. And importantly, it’s not just distressed debt that’s cheap…

It’s the entire bond market.

The bonds of many stable, blue-chip businesses are trading at distressed prices – hundreds of dollars below par value ($1,000).

But as we said, this setup might not stick around for much longer.

The Fed cut rates three times in 2024. And after holding off for most of 2025… it cut rates three consecutive times to close the year.

That likely won’t be the end…

President Donald Trump has been pushing for lower rates since he took office. He has gone as far as threatening to remove Powell from his post.

While the Fed’s current plan would leave rates around 3.5% to 3.75%… that’s still much higher than Trump’s 1% to 2% target.

We think Trump will get his way this year. Powell’s term as Fed chair ends in May. The Trump administration will be able to appoint a new chair who shares the president’s views on rate cuts.

And when that happens… it will be like 2022 in reverse. Bond investors will ditch U.S. Treasurys when they stop being so attractive.

They’ll hop right on over to the blue chips they’ve been ignoring for years.

As investors pile back in, the prices of those bonds will soar back toward par value.

That brings us to today’s opportunity…

Investors have a short window of time to buy in before the rush. And that’s exactly what we told folks to do in our Credit Cashflow Investor monthly advisory.

Only we didn’t just recommend our one favorite bond…

We recommended six.

The bonds were all issued by household names. You’d likely recognize most, if not all, of the underlying companies. There’s no question about their stability.

And yet, they’re dirt-cheap today.

If Trump gets his way in 2026, our recommendations could appreciate far sooner than maturity. We could be ready to take profits in as little as a year or so.

Opportunities like this don’t come around often. The past few years of high interest rates have turned the credit market on its head. The bonds of stable, trusted businesses are trading like “junk.”

And folks who take advantage of this setup could be in for a sizeable reward.

Regards,

Rob Spivey


Editor’s note: According to Rob, Trump’s actions are creating a rare anomaly that has never existed in market history.

For investors who are paying attention, this could result in the opportunity to double your money – with less risk than nearly any other asset in the markets.

That’s why Rob recently went on camera with Joel Litman – Altimetry’s chief investment officer – to discuss how you can position yourself to profit from this market shift. Learn more here…

You have received this e-mail as part of your subscription to Stansberry Digest. If you no longer want to receive e-mails from Stansberry Digest click here.

Published by Stansberry Research.

You’re receiving this e-mail at pahovis@aol.com. Stansberry Research welcomes comments or suggestions at feedback@stansberryresearch.com. This address is for feedback only. For questions about your account or to speak with customer service, call 888-261-2693 (U.S.) or 443-839-0986 (international) Monday-Friday, 9 a.m.-5 p.m. Eastern time. Or e-mail info@stansberryresearch.com. Please note: The law prohibits us from giving personalized financial advice.

© 2026 Stansberry Research. All rights reserved. Any reproduction, copying, or redistribution, in whole or in part, is prohibited without written permission from Stansberry Research, 1125 N Charles St, Baltimore, MD 21201 or stansberryresearch.com.

Any brokers mentioned constitute a partial list of available brokers and is for your information only. Stansberry Research does not recommend or endorse any brokers, dealers, or investment advisors.

Stansberry Research forbids its writers from having a financial interest in any security they recommend to our subscribers. All employees of Stansberry Research (and affiliated companies) must wait 24 hours after an investment recommendation is published online – or 72 hours after a direct mail publication is sent – before acting on that recommendation.

This work is based on SEC filings, current events, interviews, corporate press releases, and what we’ve learned as financial journalists. It may contain errors, and you shouldn’t make any investment decision based solely on what you read here. It’s your money and your responsibility.

Finally, I found

Finally, I Found It 

Karim Rahemtulla, Head Fundamental Tactician, Monument Traders Alliance 

Karim Rahemtulla

Dear Reader,

I’ve had some great stock successes in my career.

RYCEY was one of the big ones. I called it the “single best value play in the history of the markets” in 2022.

Since then it’s gone from under $2 to over $16.

My followers have reported making $141,000… $272,000… $1 million… and even $8.2 million on this one stockAnd yet, RYCEY was not as good as the stock I just found.

It’s a tiny company – just 2,500th the size of Nvidia.

Yet it holds the patents on a new chip technology that uses up to 40% less energy than silicon… while increasing performance up to 100-fold!

This tech just set two new world records.

The Center for Strategic & International Studies reports this new tech “has emerged as a frontrunner in the quest to push the boundaries of electronics, ushering in a new era of energy-efficient and high-performance devices.”

And here’s what makes it so exciting.

Nvidia is so wowed by this tech, they immediately partnered with this tiny company to get its tech into Nvidia’s brand new AI super-factories.

In short, this tiny company could become one of the most important in the world by this time next year.

That’s why I put together a brand new presentation for you.

In it, I explain…

How the tech works…

Why the major tech firms like Nvidia are flocking to the company with all the patents…

And why I believe this one stock is the single best buy in the markets today.

If you’re looking for one great stock with the potential to repeat Nvidia’s 35,600% rise over the last 10 years, this is it.

Watch My Presentation on the Greatest Stock Story Ever Told Right Here

Yours in smart speculation,Karim Rahemtulla Signature

Karim Rahemtulla, Head Fundamental Tactician
Monument Traders AllianceMonument Traders Alliance

Monument Traders Alliance, LLC

You are receiving this email because you subscribed to Trade of the Day.
Trade of the Day is published by Monument Traders Alliance, LLC.

To stop receiving special invitations and offers from Trade of the Day, please click here.
Please note: This will not impact the fulfillment of your subscription in any way.

Ready to start investing? Click here now.
Questions? Check out our FAQs. Trying to reach us? Contact us here.

To cancel by mail or for any other subscription issues, write us at:
Trade of the Day | 14 West Mount Vernon Place |Baltimore, MD 21201
North America: 800.507.1399 | International: +1.443.353.4977
Website | Privacy Policy
Keep the emails you value from falling into your spam folder. Whitelist Trade of the Day. 

© 2026 Monument Traders Alliance, LLC All Rights Reserved 

Please do not reply to this email as it goes to an unmonitored inbox.

Nothing published by Monument Traders Alliance should be considered personalized investment advice. Although our employees may answer your general customer service questions, they are not licensed under securities laws to address your particular investment situation. No communication by our employees to you should be deemed personalized investment advice. We allow the editors of our publications to recommend securities that they own themselves. However, our policy prohibits editors from exiting a personal trade while the recommendation to subscribers is open. In no circumstance may an editor sell a security before subscribers have a fair opportunity to exit. The length of time an editor must wait after subscribers have been advised to exit a play depends on the type of publication. All other employees and agents must wait 24 hours after publication before trading on a recommendation.

Any investments recommended by Monument Traders Alliance should be made only after consulting with your investment advisor and only after reviewing the prospectus or financial statements of the company.

Protected by copyright laws of the United States and international treaties. The information found on this website may only be used pursuant to the membership or subscription agreement and any reproduction, copying or redistribution (electronic or otherwise, including on the world wide web), in whole or in part, is strictly prohibited without the express written permission of Monument Traders Alliance, LLC, 14 West Mount Vernon Place, Baltimore, MD 21201.

REF: 000142349377

[Confirm email] 5 days to master options in this tech

With one, simple strategy, I’m able to day trade options every single morning starting at 9:30am est. 

This one options move allows me to get in and out fast for double-digit gains in about an hour. 

Over the past few years, my alerts would’ve turned 25k into over 1.8 million. 

And I want you to see how to do it with me, live, on camera. 

My name is Mike Shorr. I started my career on the floor of the CBOE in Chicago trading options. My trading firm had months totaling millions in profits. 

Today, I continue to day trade options, but also trade alongside other traders like yourself in my Short Term Options room. 

For 5 days, starting on the 9th… you can join me in my trading room. No cost. No credit card. 

Confirm your email here
Day Trading Options with Mike Shorr in his Trading Room
February 9th – 13th

I’ve never once opened up my trading room to the public for 5 days, for free. Never in 5+ years doing this live. 

You get the first shot in. 

But this may be the only email you get to register. 

If you wish to learn more about day trading options, grab your spot here for next week’s first ever Open House in my day trading options room.

Mike Shorr

Prosper Trading

Founder of the Short Term Options Virtual Trading Floor®


Sunday’s Exclusive Article

The Hot Dog Hedge: Smithfield Acquires Nathan’s Famous

Written by Jeffrey Neal Johnson. Article Published: 1/25/2026. 

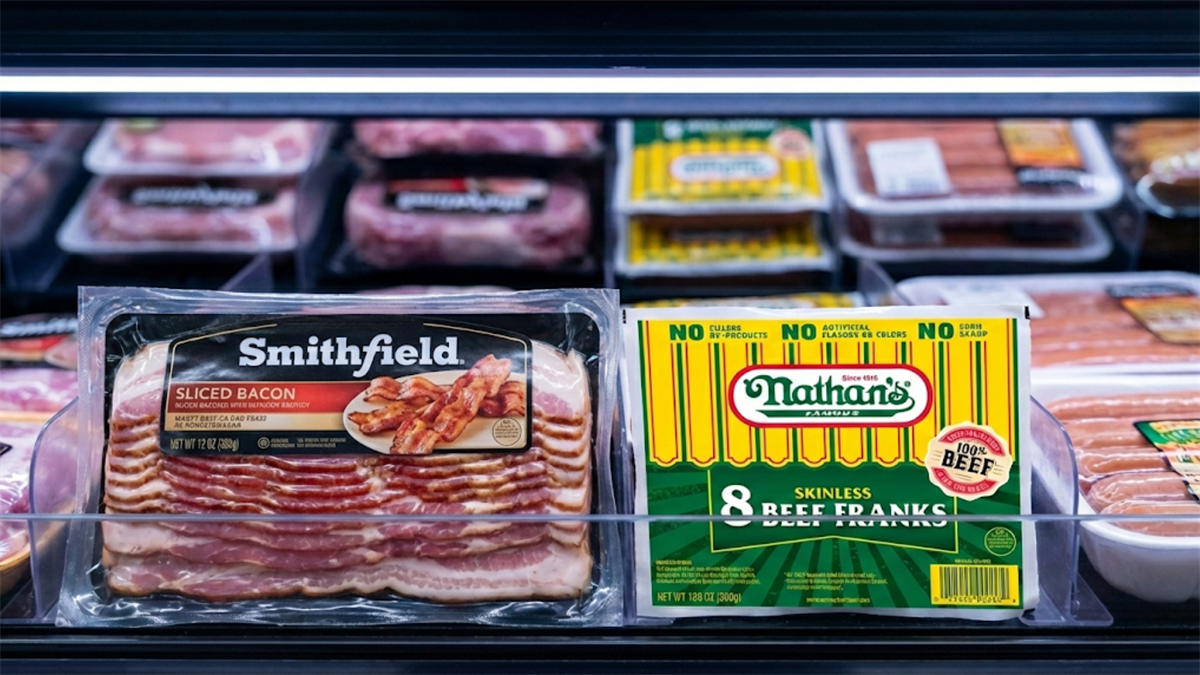
Smithfield bacon and Nathan’s beef franks in a grocery cooler, spotlighting packaged meat and food stocks.

Article Highlights

  • Smithfield is funding the entire acquisition of Nathan’s Famous with cash on hand to avoid high interest rates and deliver immediate earnings growth for shareholders.
  • The deal transforms Smithfield from a manufacturer into a brand owner, eliminating licensing fees and capturing the full profit margin on retail products.
  • Acquiring a premium beef brand allows the company to diversify its protein portfolio and utilize its massive scale to better manage input costs.

For companies that have recently returned to the public markets, the first major acquisition is a defining moment: it shows investors how management plans to deploy capital for growth. Smithfield Foods (NASDAQ: SFD), which completed its IPO in January 2025, has wasted little time. The pork industry giant has entered into a definitive agreement to acquire Nathan’s Famous (NASDAQ: NATH) for $102 per share.

Beyond the headline about two iconic American brands joining forces, the deal is a deliberate financial move to convert ongoing royalty payments into immediate earnings. By leveraging its large operational scale, Smithfield plans to optimize a brand it already manufactures for. For shareholders, this looks less like a speculative bet and more like a high-probability return.

A Cash Deal in a Debt World

A Message From An Ex-CIA Officer About Trump (Ad)

The mainstream media – and very few Americans know anything about this.

I wouldn’t be doing my job if I didn’t come forward and explain what’s happening.

I believe this will make history.Please take a moment to watch my interview now.

The transaction terms underscore a conservative approach. Smithfield will pay $102 per share in an all-cash deal, valuing the enterprise at roughly $450 million, and it is funding the purchase entirely with cash on hand.

With borrowing costs still elevated, many buyers must take on new debt to fund acquisitions — adding interest expense that can erode future profits. Smithfield’s ability to finance this purchase without issuing debt is a sign of balance-sheet strength. The company finished the third quarter of fiscal 2025with more than $3 billion in available funds and a modest leverage ratio of about 0.8x net debt to adjusted EBITDA.

Deploying idle cash to buy an operating business typically outperforms leaving it in a low-interest account, where inflation can erode value. Smithfield expects the acquisition to be immediately accretive to adjusted earnings per share, adding to the company’s bottom line upon closing rather than after a lengthy turnaround.

Moreover, Smithfield pays a dividend yield of roughly 4.32%, and this purchase helps support that payout by securing more predictable cash flows. The strategy reflects a preference for high-probability returns over speculative ventures.

From Renter to Owner: A $9 Million Opportunity

At the heart of the deal is the elimination of licensing fees. For more than a decade Smithfield has manufactured and distributed Nathan’s retail products, but without owning the brand it paid high-margin royalties back to Nathan’s corporate entity.

Acquiring Nathan’s ends those payments. Smithfield projects about $9 million in annual run-rate cost savings within two years of closing, much of it from eliminating the licensing obligation. The transaction converts Smithfield from a brand renter into an owner, allowing it to capture the full profit on every package sold.

Mergers often carry integration risk — combining factories, systems, and workforces can be costly and complex. This deal carries minimal integration risk because Smithfield already operates the supply chain for Nathan’s retail business. The same factories will continue producing the products, so there are no major system consolidations or plant closures required. It is largely a change in financial ownership rather than an operational overhaul, letting Smithfield streamline its Packaged Meats segment with little friction.

Beef vs. Pork: The Inflation Hedge

Commodity dynamics help explain the timing. Nathan’s products are 100% beef and recently faced a 16%–20% jump in the cost of beef and trimmings. As a smaller, beef-focused standalone company, Nathan’s had limited tools to offset that inflation.

Smithfield, by contrast, is the world’s largest pork processor and hog producer and is benefiting from lower grain and feed costs that support its core margins. Adding a premium beef brand diversifies Smithfield’s protein mix, providing a natural hedge: when pork margins weaken, beef may perform better, and vice versa.

More importantly, Smithfield brings procurement scale, hedging capabilities and buying power that a smaller business like Nathan’s could not match. Those advantages should help stabilize input costs for Nathan’s products and protect margins over time.

Consumer behavior also matters. During periods of inflation, shoppers often trade down from expensive cuts to more affordable processed options such as hot dogs and sausages. Owning a premium hot dog brand positions Smithfield to capture that volume and strengthens its position across both pork and beef categories.

Disciplined Growth: A Strategic Base Hit

This acquisition is a high-probability base hit rather than a risky home run swing. It does not dramatically change Smithfield’s scale, but it secures a valuable asset long term. Previously, Smithfield’s rights to the Nathan’s brand were set to expire in 2032; the deal removes that expiration and locks the cash flows into Smithfield’s operations in perpetuity.

The transaction is expected to close in the first half of 2026, subject to customary regulatory reviews, including the Committee on Foreign Investment in the United States (CFIUS). The companies have included customary termination fees and closing conditions that reflect confidence in the timing.

For shareholders, this move reinforces the Moderate Buy consensus around the stock. It bolsters the case that Smithfield is a disciplined capital allocator willing to use its strong balance sheet to lock in long-term value. By removing the licensor from the equation, Smithfield has simplified its economics and set the stage for sustained margin improvement in its Packaged Meats business. Investors now have a clear catalyst to monitor as Smithfield converts a long-standing manufacturing relationship into permanent ownership.

Thank you for subscribing to The Early Bird, MarketBeat’s 7:00 AMnewsletter that covers stories that will impact the stock market each day.

This email is a paid sponsorship sent on behalf of Prosper Trading Academy, a third-party advertiser of The Early Bird and MarketBeat. 

If you need help with your newsletter, please feel free to email MarketBeat’s U.S. based support team at contact@marketbeat.com.

If you no longer wish to receive email from The Early Bird, you can unsubscribe.

© 2006-2026 MarketBeat Media, LLC. All rights reserved.
345 N Reid Pl., Suite 620, Sioux Falls, S.D. 57103-7078. United States..

From Our Partners: This Isn’t a Portfolio. It’s an AI Engine. (From RAD Intel)

Trump’s Final Shocking Act Begins February 24

Dear Reader,

After signing more than 220 Executive Orders… more than any president in American history… Donald Trump is preparing for one final move.

On February 24th — I have every reason to believe he will sign his Final Executive Order.

When I say that it’s his FINAL executive order…

It’s not because he’s leaving office.

It’s not because he’s sick or having any health issues.

It’s not because he’ll be impeached for the Epstein files, or some dark, twisted scandal.

There’s another reason that, despite a long future in front of him, this will be Trump’s very last Executive Order…

Click here or below for this unbelievable story…

Regards,

Turn Your Images On


Ian King
Chief Strategist, Strategic Fortunes


Further Reading from MarketBeat Media

Why Walmart Continues to Rally While Executives Sell the Stock

Written by Jeffrey Neal Johnson. Originally Published: 1/27/2026. 

Walmart logo over grocery aisle with rising arrow, highlighting WMT stock and retail sales growth.

In Brief

  • Walmart is rapidly evolving into a high-margin technology company by automating its supply chain and expanding its lucrative digital advertising business.
  • The recent wave of executive stock sales is a standard practice tied to a leadership transition, rather than a signal of weak corporate fundamentals.
  • Institutional investors continue to buy the stock because the company dominates the retail sector, has a massive competitive moat, and pays a reliable dividend.

Walmart (NASDAQ: WMT) is currently defying expectations. The stock is trading near all-time highs — around $118 per share — and the company is closing in on a historic $1 trillion market capitalization. By most financial measures, the retail giant is firing on all cylinders, outperforming competitors and the broader retail sector. Yet for investors watching the insider trading dashboard, a contradictory signal appears: while the market is buying aggressively, many executives are selling.

Over the last 12 months, tracking data shows a clear disparity: zero open-market purchases by insiders and more than $60 million in sales. Typically, insider selling can be interpreted as reduced confidence in a company’s prospects. Still, Walmart’s stock price is up over 5% in the last 30 days and up 10% in the past 90 days.

This Isn’t a Portfolio. It’s an AI Engine. (Ad)

First comes real enterprise traction. Then comes structural leverage. Then comes compounding.

RAD Intel is an AI company already past step one. With $60M+ raised, 14,000+ investors, and a reserved Nasdaq ticker $RADI, the foundation is in place.This is typically where repricing begins. Invest now at $0.85 per share.

To reconcile that disconnect, investors need to look beyond the headline numbers. Walmart is evolving from a primarily brick-and-mortar grocer into a higher-margin, technology-enabled business. That transition, combined with the company’s strength during uncertain economic times, suggests institutional confidence is considerably stronger than the caution flagged by executive sales.

Profit Taking or Loss of Faith?

When a CEO liquidates millions in company stock it attracts attention. In January 2026, outgoing CEO Doug McMillon sold approximately 19,416 shares, a transaction valued at over $2.3 million. Incoming CEO John Furner also sold roughly $1.5 million in stock, and other senior executives, including Executive Vice President Daniel Bartlett, executed sizable sales during the same period.

At first glance, a ledger showing 10 insiders selling and zero buying over the last year looks bearish. However, three key factors provide important context that reduces the perceived risk:

  • The changing of the guard: The selling coincides with a major leadership transition. McMillon is retiring on January 31, 2026, and Furner assumes the CEO role on February 1. Executives commonly liquidate shares for estate planning, tax planning or to diversify their portfolios when leaving a role or taking on new responsibilities.
  • Selling into strength: These sales occurred near recent highs — roughly $118–$120 per share — after about a 24% annual rally. Exiting positions at elevated valuations is often rational profit-taking rather than a sign of panic.
  • Market absorption: Despite millions of dollars of insider supply hitting the market, the stock has held up. Buyer demand from institutional investors has been sufficient to absorb those sales, suggesting that market participants still see value.

The Ultimate Recession Hedge: Winning the Trade-Down

The 2026 economic backdrop remains mixed, with lingering inflationary pressures and uneven growth. In such environments, consumers tend not to stop spending; they change where they spend. This “trade-down” effect sees shoppers move from premium grocers like Whole Foods or mid-tier chains such as Target (NYSE: TGT) to Walmart to stretch their budgets.

Walmart’s Everyday Low Price promise attracts value-conscious customers, and the composition of that customer base is shifting. Data from the company’s third-quarter earnings indicates market-share gains are being driven in part by higher-income households earning over $100,000 annually.

This demographic broadening creates a durable competitive moat, insulating Walmart from economic swings that typically hurt retailers dependent primarily on lower-income shoppers. When the economy wobbles, Walmart’s customer base tends to expand rather than contract.

For conservative investors, the stock also provides an income cushion:

That mix of steady income and defensive demand helps cement Walmart’s role as a core holding for investors seeking stability without forgoing growth exposure.

Beyond Brick and Mortar: The Tech-Powered Future

Value investors often balk at Walmart’s valuation. The stock trades at a price-to-earnings ratio near 41x, well above historical retail averages around 20x–25x. But the market increasingly values Walmart as more than a traditional grocer — it’s being re-rated as a hybrid of retail and technology.

The rationale for a premium valuation lies in higher-margin revenue streams that don’t depend on selling physical goods:

  • Advertising business: Walmart’s global advertising operations, helped by the Vizio acquisition, grew 53% in the most recent quarter. Selling digital ads on Walmart.comand connected-TV inventory generates much higher profit margins than selling groceries, and expansion of this segment can disproportionately boost earnings.
  • AI and automation: Walmart is deploying technology to improve its cost structure. The company is rolling out Sparky, an AI shopping assistant developed in partnership with OpenAI, to personalize the shopping experience. More than half of its e-commerce fulfillment volume is now automated, permanently lowering the cost to serve and enabling Walmart to compete on price while protecting margins.

Even Walmart’s strategic move to list on the NASDAQ signals an alignment with technology peers rather than legacy retailers, and investors appear willing to pay a premium for that strategic shift.

Why Fundamentals Outweigh the Noise

Insider-trading alerts can be unnerving, but good investing separates noise from signal. The recent executive selling at Walmart appears structural — tied to a historic leadership transition and reasonable profit-taking at elevated prices — and has not halted the stock’s momentum because broader market buying is grounded in solid fundamentals.

Walmart combines defensive stability through grocery dominance with offensive growth from advertising and automation. Whether the economy slows or accelerates, the company is positioned to capture value. For investors navigating 2026, Walmart remains a core holding that offers downside protection alongside upside potential.

This email is a sponsored message from Banyan Hill Publishing, a third-party advertiser of MarketBeat. Why did I receive this email content?. 


If you would like to unsubscribe from receiving offers for Strategic Fortunes, please click here.


If you have questions or concerns about your newsletter, please don’t hesitate to email our U.S. based support team at contact@marketbeat.com.

If you would no longer like to receive promotional emails from MarketBeat advertisers, you can unsubscribe or manage your mailing preferences here.

© 2006-2026 MarketBeat Media, LLC. 
345 N Reid Place #620, Sioux Falls, SD 57103. United States..

See Also: This Isn’t a Portfolio. It’s an AI Engine. (From RAD Intel)

Switch2 Sales Hit Records Despite Nintendo’s Pullback

Unsubscribe

Confirm Your Name Before the Letter Goes Out (From American Alternative)


Nintendo Stock Falls 20%—But the Rebound Case Is Growing

Written by Chris Markoch on February 6, 2026 

Nintendo logo with Switch console, NES and Mario cap on desk, hinting at Switch2 sales rebound.

In Brief

  • Nintendo shares have pulled back sharply despite strong console-unit milestones, creating a potential 2026 rebound setup.
  • Engagement, software releases, and brand licensing could support Switch2 ecosystem growth through 2026.
  • Easing input costs and supply-chain shifts may help margins, while technicals suggest oversold conditions.

In the first half of 2025, Nintendo (OTCMKTS: NTDOY) was not only one of the best-performing consumer discretionary stocksbut a market standout as well. It surged 76% in anticipation of the company’s long-awaited Switch2 release. But it seems traders weren’t looking to stay long, as the stock is down 20% in the last 12 months and over 18% year-to-date as of Feb. 5.

It wasn’t that Switch2 sales disappointed. The company has sold 155.4 million units of its new console, surpassing the previous record of 154 million units by the Nintendo DS. However, there have been concerns over the number not being better. That corresponds with lower profit numbers, cautious forward guidance, tariff risks, and softer-than-expected holiday demand.

However, this could be a case of a stock being so bad, it’s good. There are catalysts that suggest 2026 could be a bounce-back year for NTDOY stock.

Starlink pre-IPO opportunity with this $30 stock (Ad)

A little-known stock could double as Elon Musk prepares to take Starlink public in what may be the biggest IPO in history. This company is a critical supplier to Starlink’s fast-growing satellite network. One analyst believes it’s positioned for significant upside as the IPO approaches. You can get the ticker symbol free in the first three minutes of a brief video—no credit card required.Watch the video to get the ticker now

The Best May Be Yet to Come for Switch2 Sales

Nintendo’s latest investor presentation hints that the best growth phase for the Switch2 ecosystem may still be ahead. The company announced that active monthly users reached an all-time high, with engagement levels up nearly 25% year-over-year.

That’s an encouraging sign that players are not just buying the console but staying in the ecosystem. In addition, the paid Nintendo Switch Online membership base expanded, with the attach rate improving due to the launch of more bundled hardware options.

This will also be a year when Nintendo releases Switch2 versions of many of its most popular titles. Alongside upcoming releases tied to “The Legend of Zelda” and “Splatoon” franchises, Nintendo confirmed ongoing development for its next-generation game engine, which could enhance long-tail monetization for Switch2.

This gives investors a clear reason to view 2026 not as a late-cycle phase, but as a platform-expansion year.

Adding to the excitement, Super Mario turns 40 this year. To celebrate the milestone, a “Super Mario Galaxy” movie will be released. The box office success of “The Super Mario Bros. Movie” in 2023 nearly doubled the brand’s licensing revenue, and management reiterated plans for cross-promotional campaigns that convert movie audiences into active players. If the upcoming Galaxy movie can perform as well, it could spark both console and software demand heading into the holiday season.

Cost and Tariff Headwinds Could Ease

The company’s margin pressure in recent quarters stemmed from higher memory component prices and elevated transport and tariff expenses. However, management highlighted during the presentation that these headwinds are beginning to moderate. Contract memory prices started declining in early 2026, and component costs for NAND and DDR5 memory have shown early signs of stabilization.

Nintendo also stated that it is diversifying its supply chains outside of China and pursuing more local assembly in Vietnam. Those moves will help hedge against prolonged tariff risks. These measures, combined with favorable foreign exchange positions, suggest that much of the recent cost compression may prove temporary.

A Message From An Ex-CIA Officer About Trump (Ad)

The mainstream media – and very few Americans know anything about this.

I wouldn’t be doing my job if I didn’t come forward and explain what’s happening.

I believe this will make history.Please take a moment to watch my interview now.

Why the Thesis Could Be Wrong

The bullish case assumes Switch2 remains the dominant platform through 2026, but it comes with risks. Consumer fatigue could set in if Nintendo’s first-party lineup slows, especially with Sony Group (NYSE: SONY)and Microsoft (NASDAQ: MSFT) expected to introduce hardware refreshes this year.

Hardware margins also remain sensitive to component pricing. Memory and silicon costs could rebound rather than normalize. In that case, Nintendo’s profitability could remain under pressure longer than expected. And while franchise-based films have driven engagement, movie tie-ins are inherently unpredictable. Disappointing box-office results could dent sentiment and licensing revenue.

Lastly, the gaming industry’s transition toward cloud and subscription ecosystems still poses a strategic challenge. Nintendo has chosen a slower, more conservative path toward online monetization, which could leave it trailing competitors on recurring revenue growth if player preferences shift more quickly than expected.

The NTDOY Chart Supports the Comeback Story

For those who buy into the supportive thesis for Switch2 sales, then the next question is whether now is a good time to get in on Nintendo stock. The chart answers in the affirmative.

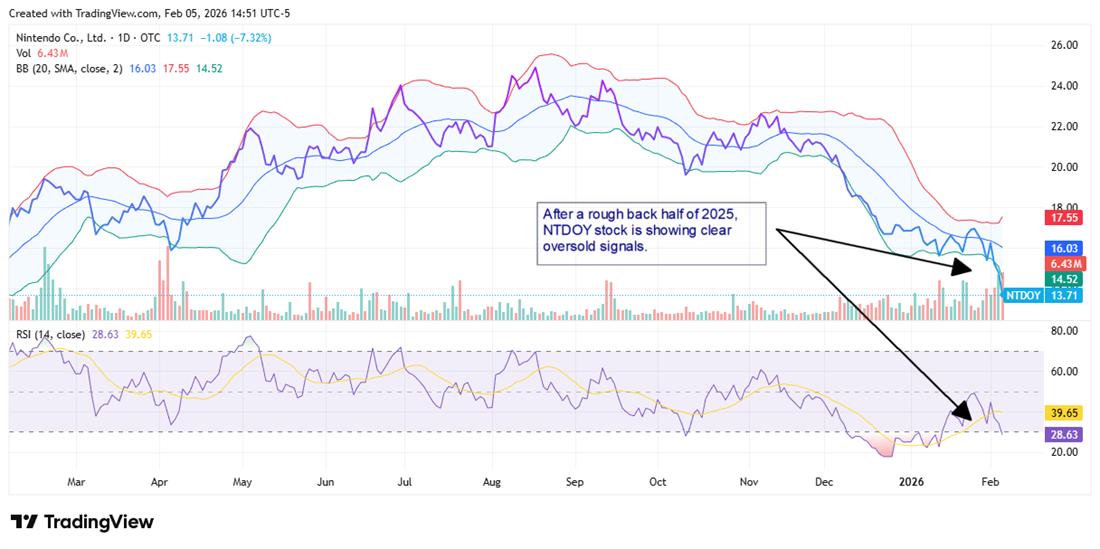
For starters, the latest selling has pushed the stock price below its lower Bollinger band. This is a technical signal indicating a trend reversal, and NTDOY stock has historically responded to such a signal with a rebound.

NTDOY stock chart displaying clear oversold signals.

The stock is also oversold from a momentum perspective. The relative strength indicator (RSI) is at 28.6, which indicates oversold conditions. On their own, neither signal is a confirmed buy signal. However, when you put them together, it’s a good indication that sentiment could change.

If it does, investors should look for NTDOY stock to reclaim the 20-day simple moving average (SMA). That would be a 17% gain from the price as of this writing.

Read this article online ›

Further Reading

MarketBeat All Access is the premier all-in-one stock research solution that helps you identify the best stocks, monitor your portfolio, and keep track of the market.

Did you enjoy this article?

I liked this article.
I did not like this article.

Thank you for subscribing to MarketBeat!

MarketBeat empowers everyday investors to make better trading decisions by providing real-time financial information and objective market research.

If you need help with your newsletter, please feel free to contact our South Dakota based support team at contact@marketbeat.com.

If you would like to unsubscribe or change which emails you receive, you can manage your mailing preferences or unsubscribefrom these emails.

Copyright 2006-2026 MarketBeat Media, LLC. All rights protected.
345 North Reid Place #620, Sioux Falls, S.D. 57103. U.S.A..

Today’s Featured Link: Trade this between 9:30 and 10:45 am EST (From Base Camp Trading)

Trump to Meet Netanyahu on Iran; Savannah Guthrie: ‘We Will Pay’; App Identifies US Goods to Boycott

Breaking News from Newsmax.com

• Netanyahu to Meet Trump Feb. 11 in DC on Iran Talks

Special: Doctor Admits Something About Trump’s Brain

• ‘We Will Pay,’ Savannah Guthrie Says in Plea to Mother’s Kidnappers

• Apps to Boycott US Goods Gained Traction in Crisis Over Greenland


SPONSOR


ADVERTORIAL

hospital

A famous doctor just made a shocking claim about President Trump’s brain: 

“I’m afraid he shows the clear signs of…” 


>>Click above to play video or view the evidence here<< 


This ad is sent on behalf of NewMarket Health Publishing, LLC. P.O. Box 913, Frederick, MD 21705, USA. If you would like to unsubscribe from receiving offers from NewMarket Health Publishing, LLC, please click here.

This email is never sent unsolicited. You have received this Newsmax email because you subscribed to it or someone forwarded it to you. To opt out, see the links below.

Remove your email address from our list or modifyyour profile. We respect your right to privacy. Viewour policy.

This email was sent by:
Newsmax.com
362 N. Haverhill Road
West Palm Beach, FL 33415 USA

DM917914
0105020dm57d

Today’s Blessing

Today’s Blessing
February 8, 2026

Forgiveness is an act of self-love. When you release grudges, you free yourself from carrying weight that was never yours to bear.RELEASE AND BE FREE 

Discover Your Path

Today’s Blessing is here to guide you through life’s twists and turns, helping you become the best version of yourself and fulfill your destiny.✨Angel NumbersAngel numbers are divine affirmations from the universe, giving us signs we’re on the right track and that we’re not alone.CONTINUE →🙏Faith MessagesHear stories from around the world that will help motivate and bring positivity to your life’s journey.CONTINUE →💫InspirationEmpowering and inspirational stories. See some of these tips from our friends to set you on the pathway to success.CONTINUE →

You’re always one blessing away from a brighter day… and a bigger life. May these stories, affirmations, prayers, and insights lift your spirits and inspire you to lift others.

Go forth and be blessed!LEARN MORE 

🕊️

Please, Unsubscribe Here to stop receiving these emails

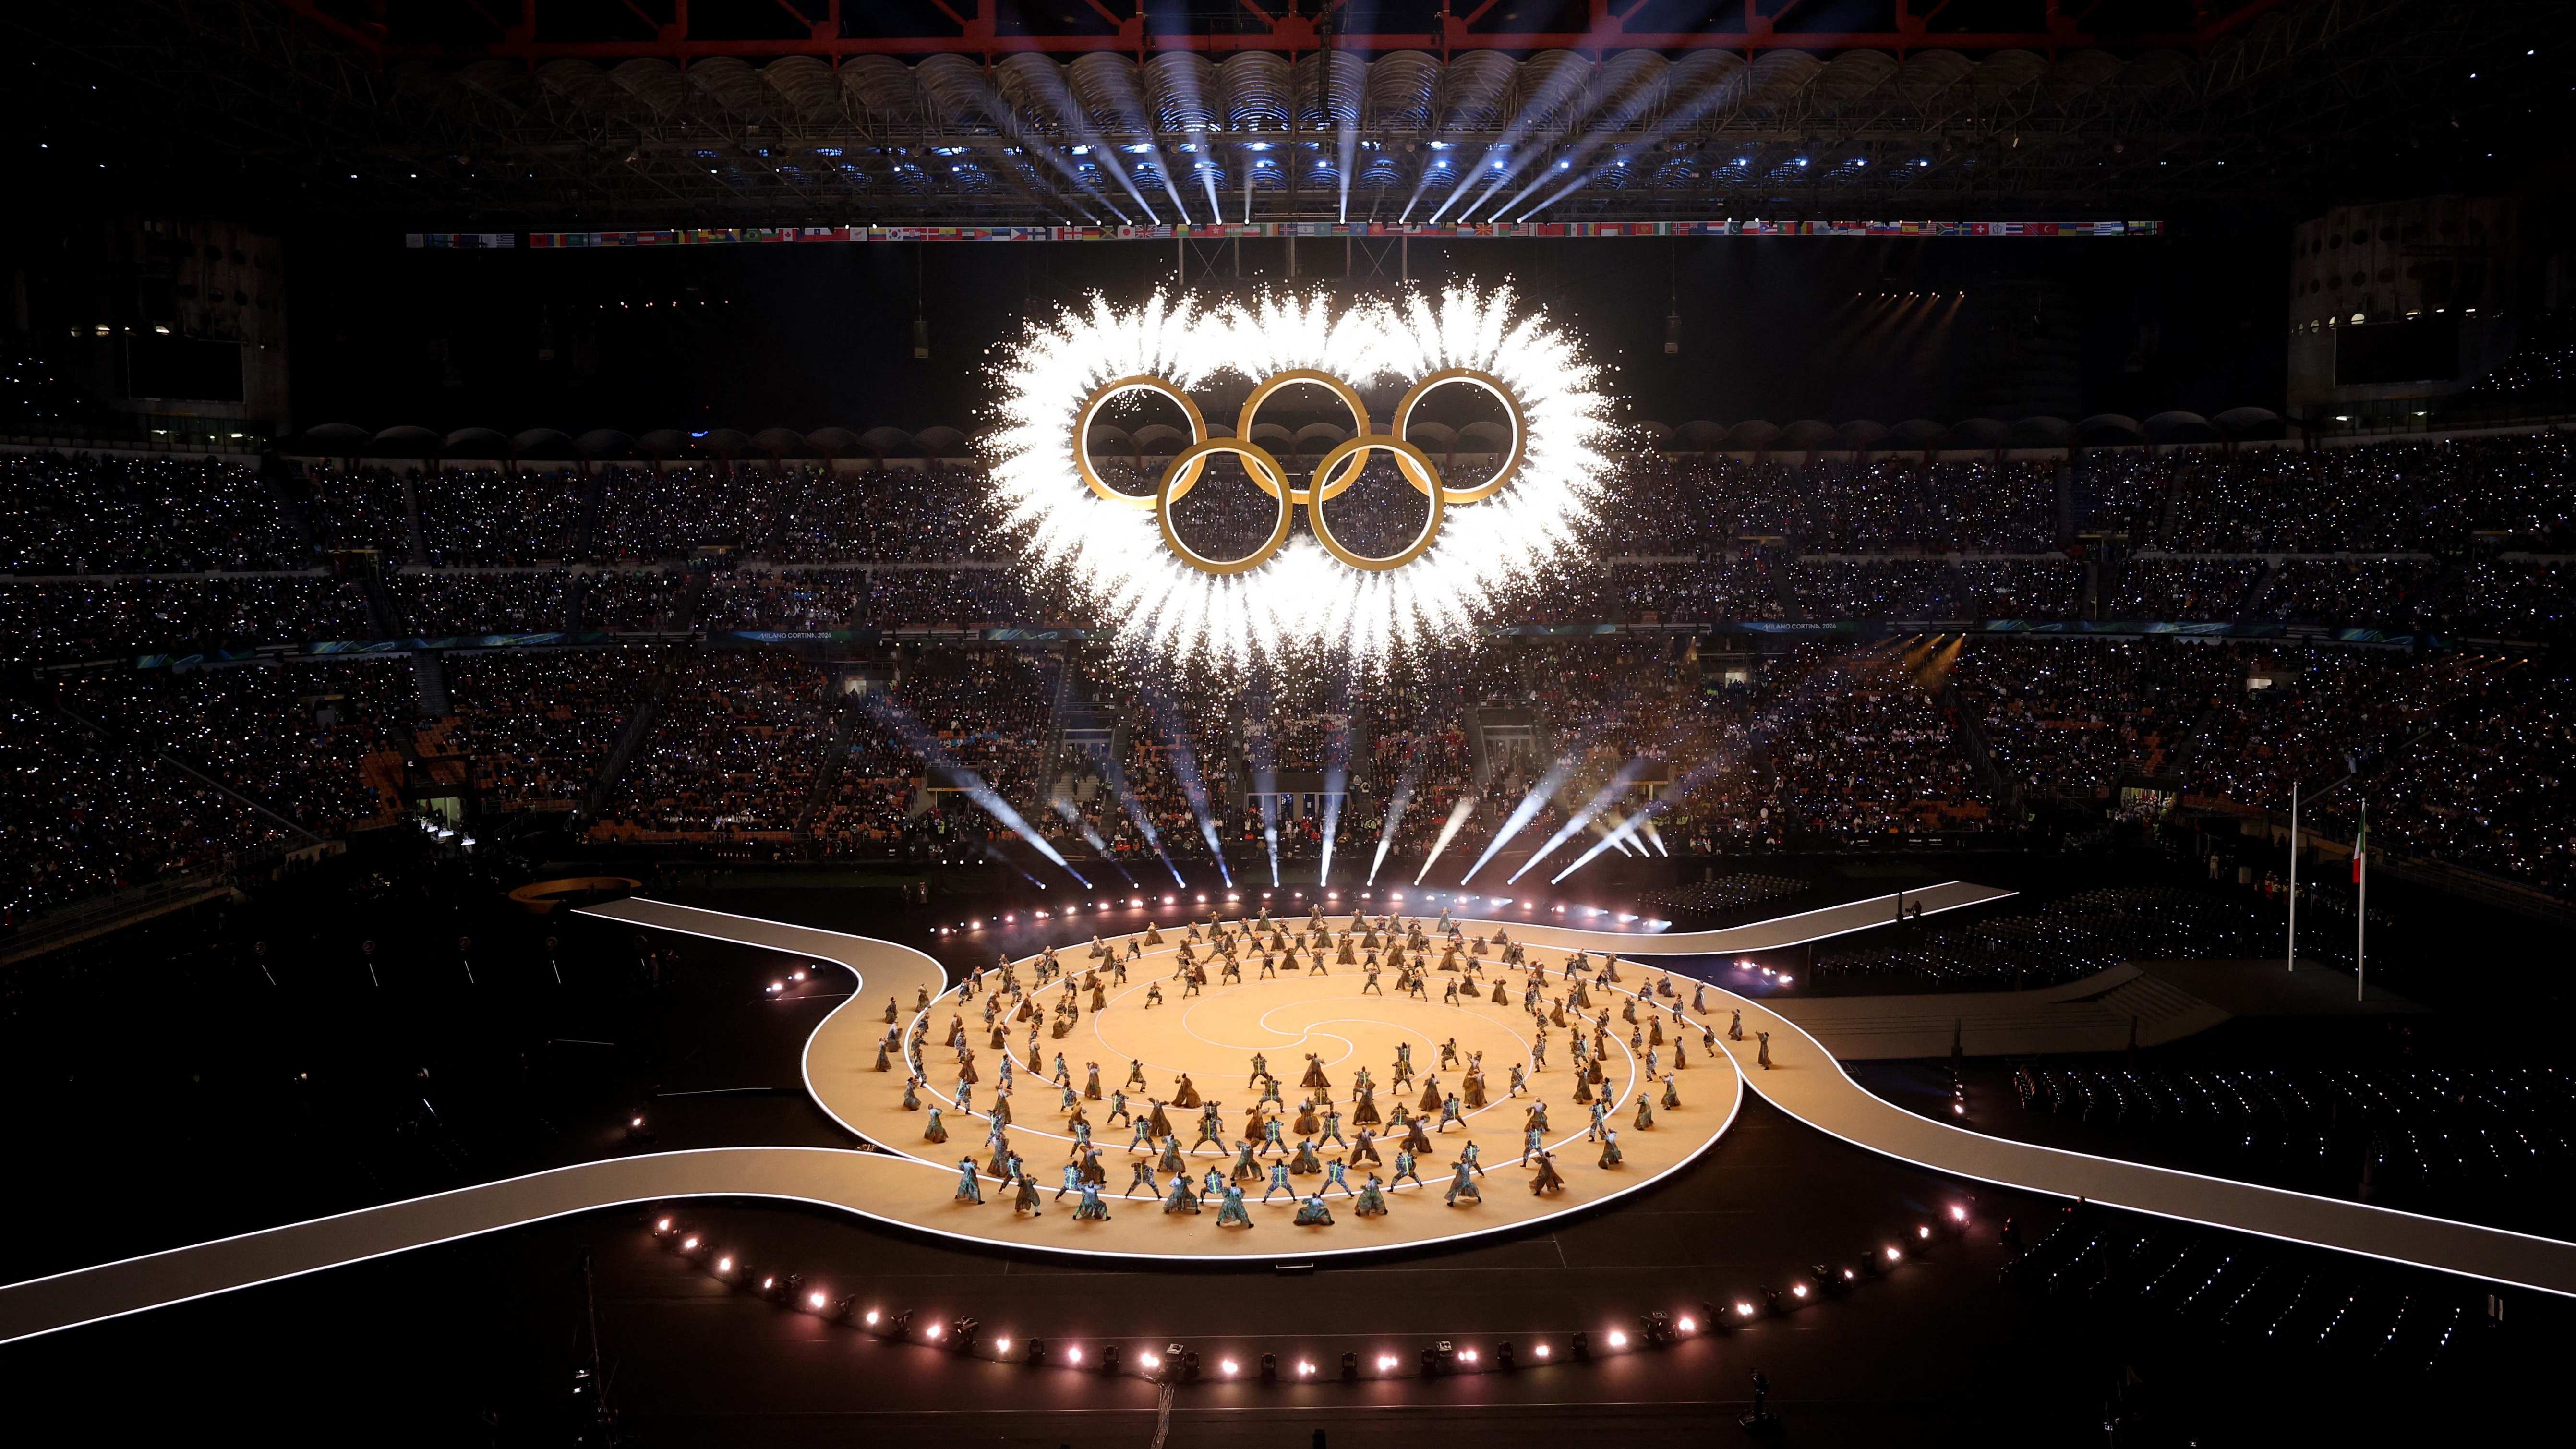
SI Weekend Roundup: Milan Cortina Opening Ceremony Paraded the Wonder of Italy to the World


SI WEEKEND ROUNDUP

Sports Illustrated

Milan Cortina Opening Ceremony Paraded the Wonder of Italy to the World

Andrew Gastelum

The 2026 Winter Olympics are officially underway with a rousing display of Italian culture in a nation that is constantly struggling with letting go of fond memories from its past.

READ MORE 

Sports Illustrated

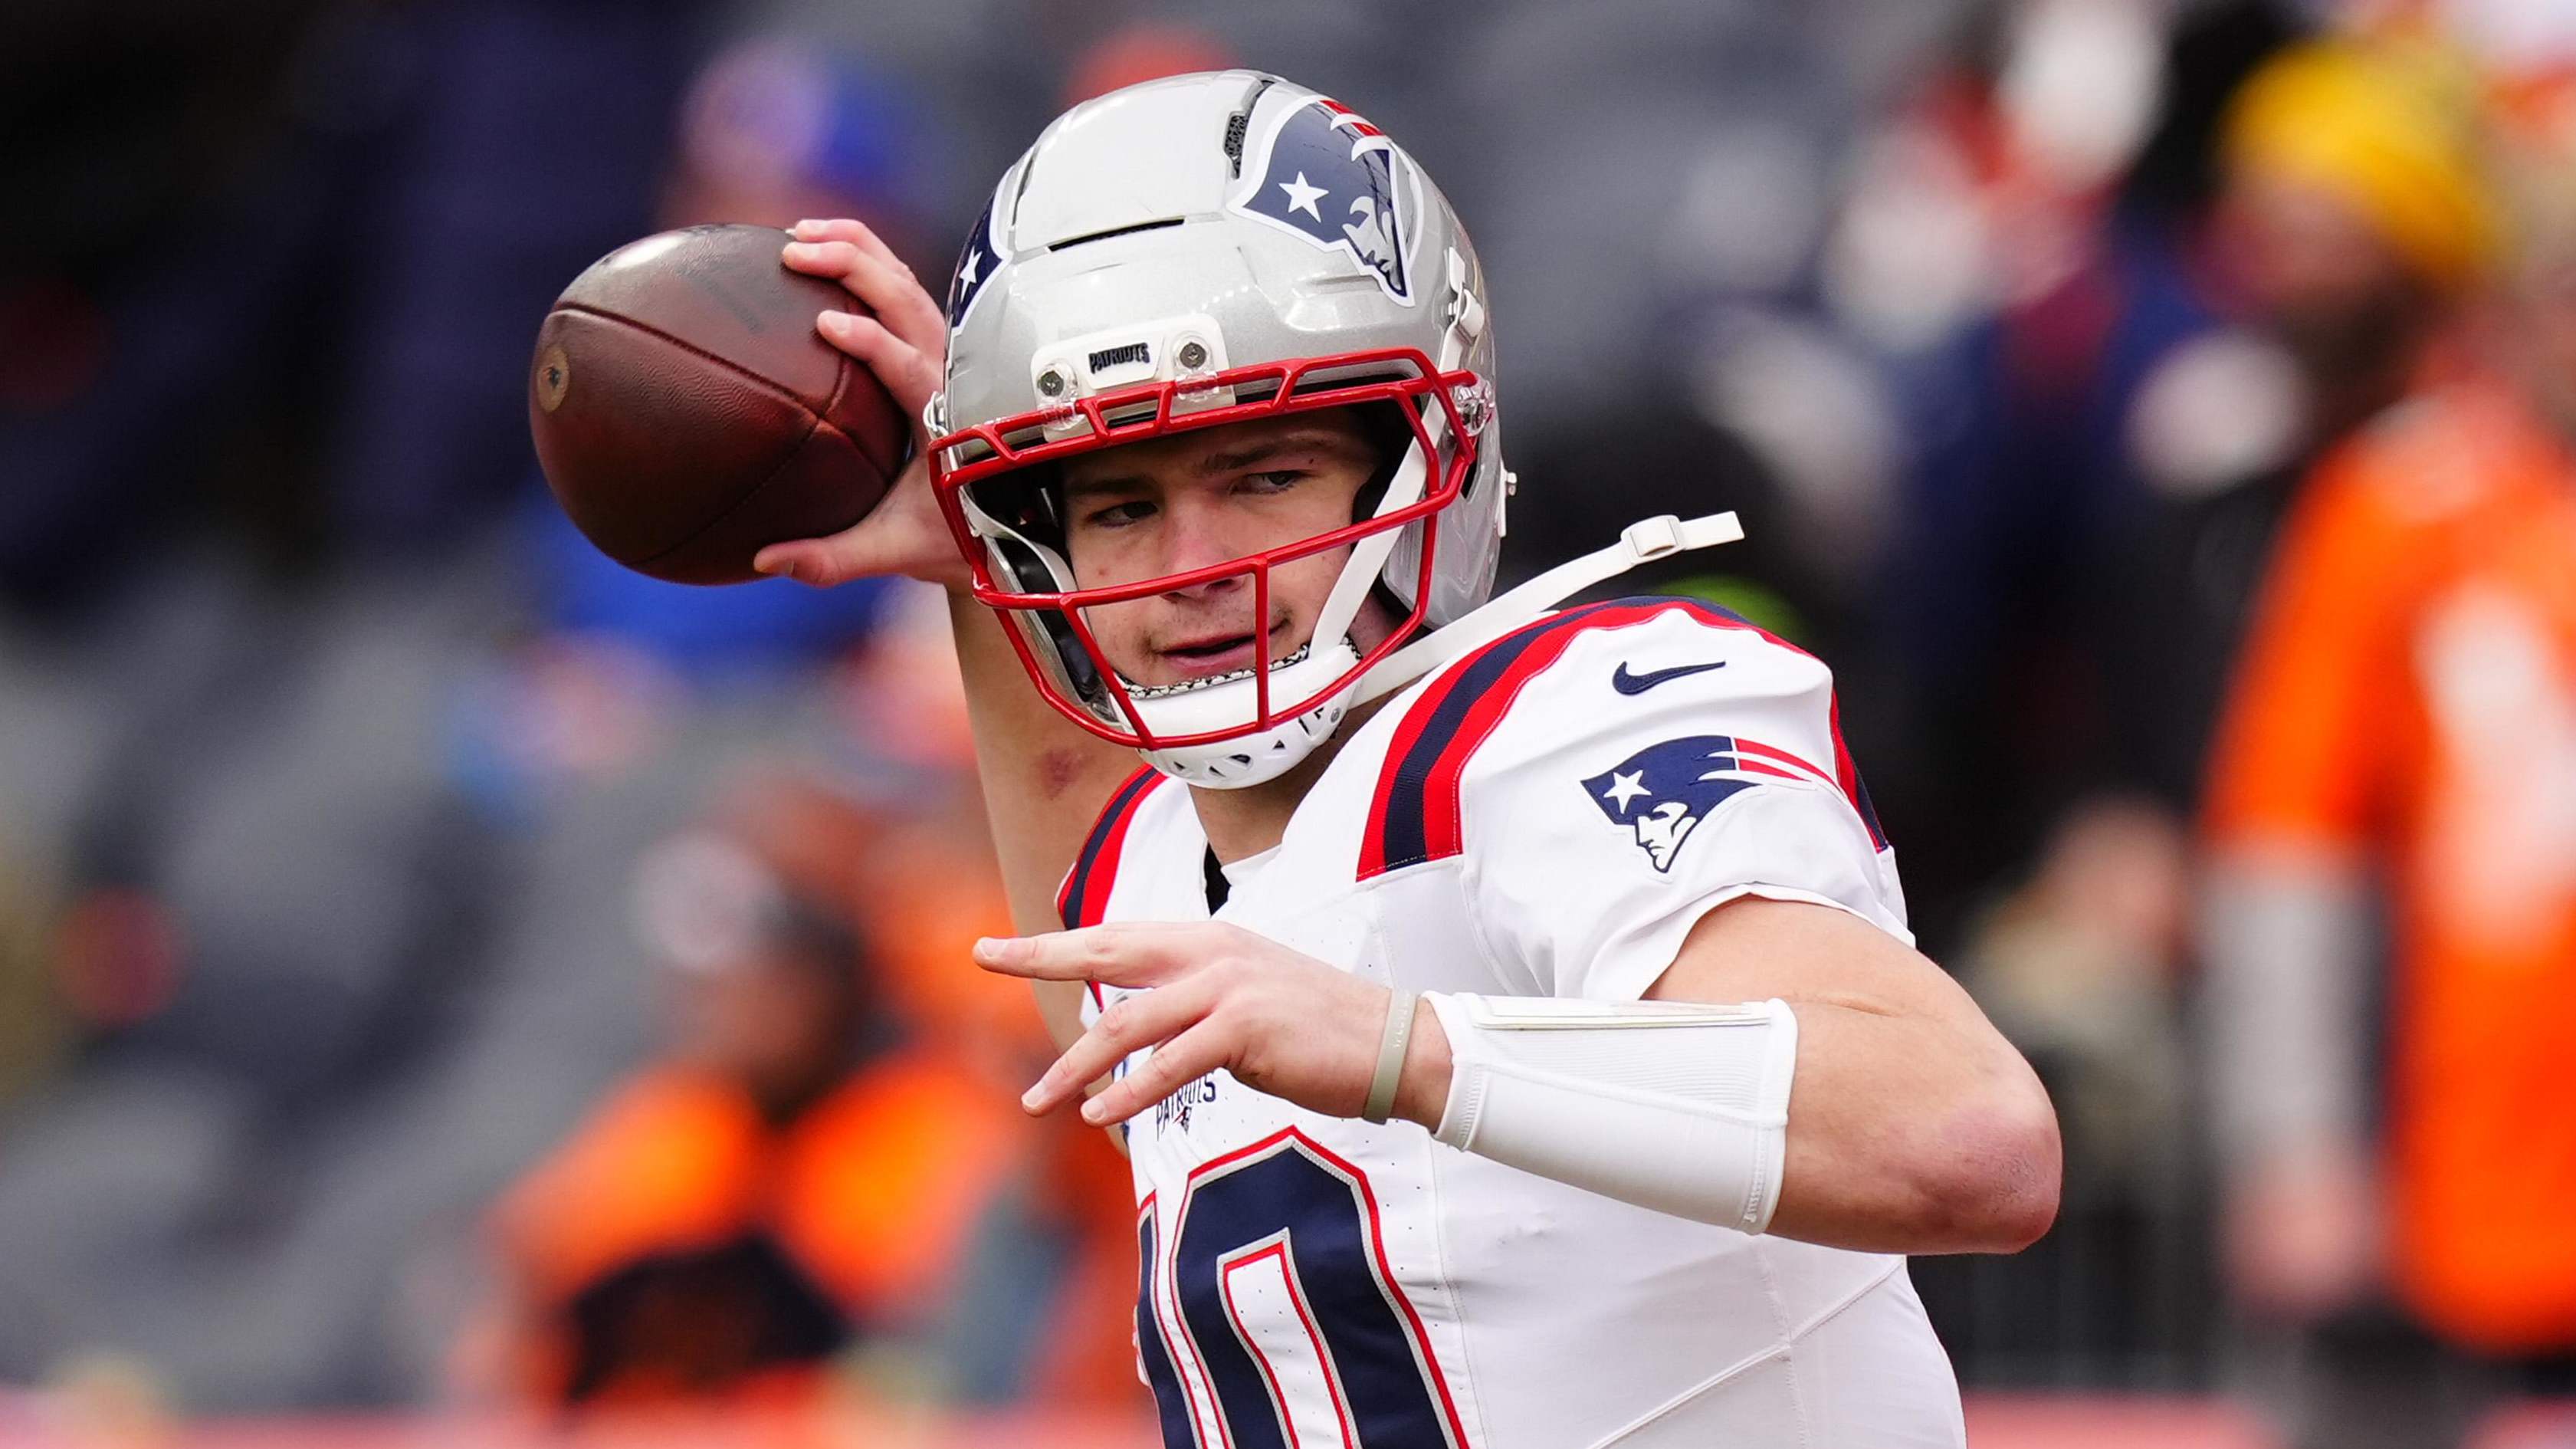
Albert Breer’s NFL Awards Ballot: Drake Maye for MVP, Matthew Stafford for First-Team All-Pro

Albert Breer

In the wake of the Bill Belichick Hall of Fame controversy, it’s best to be transparent about votes for individual honors. Plus, the Nick Emmanwori injury could be cause for concern in Seattle.

READ MORE 

Sports Illustrated

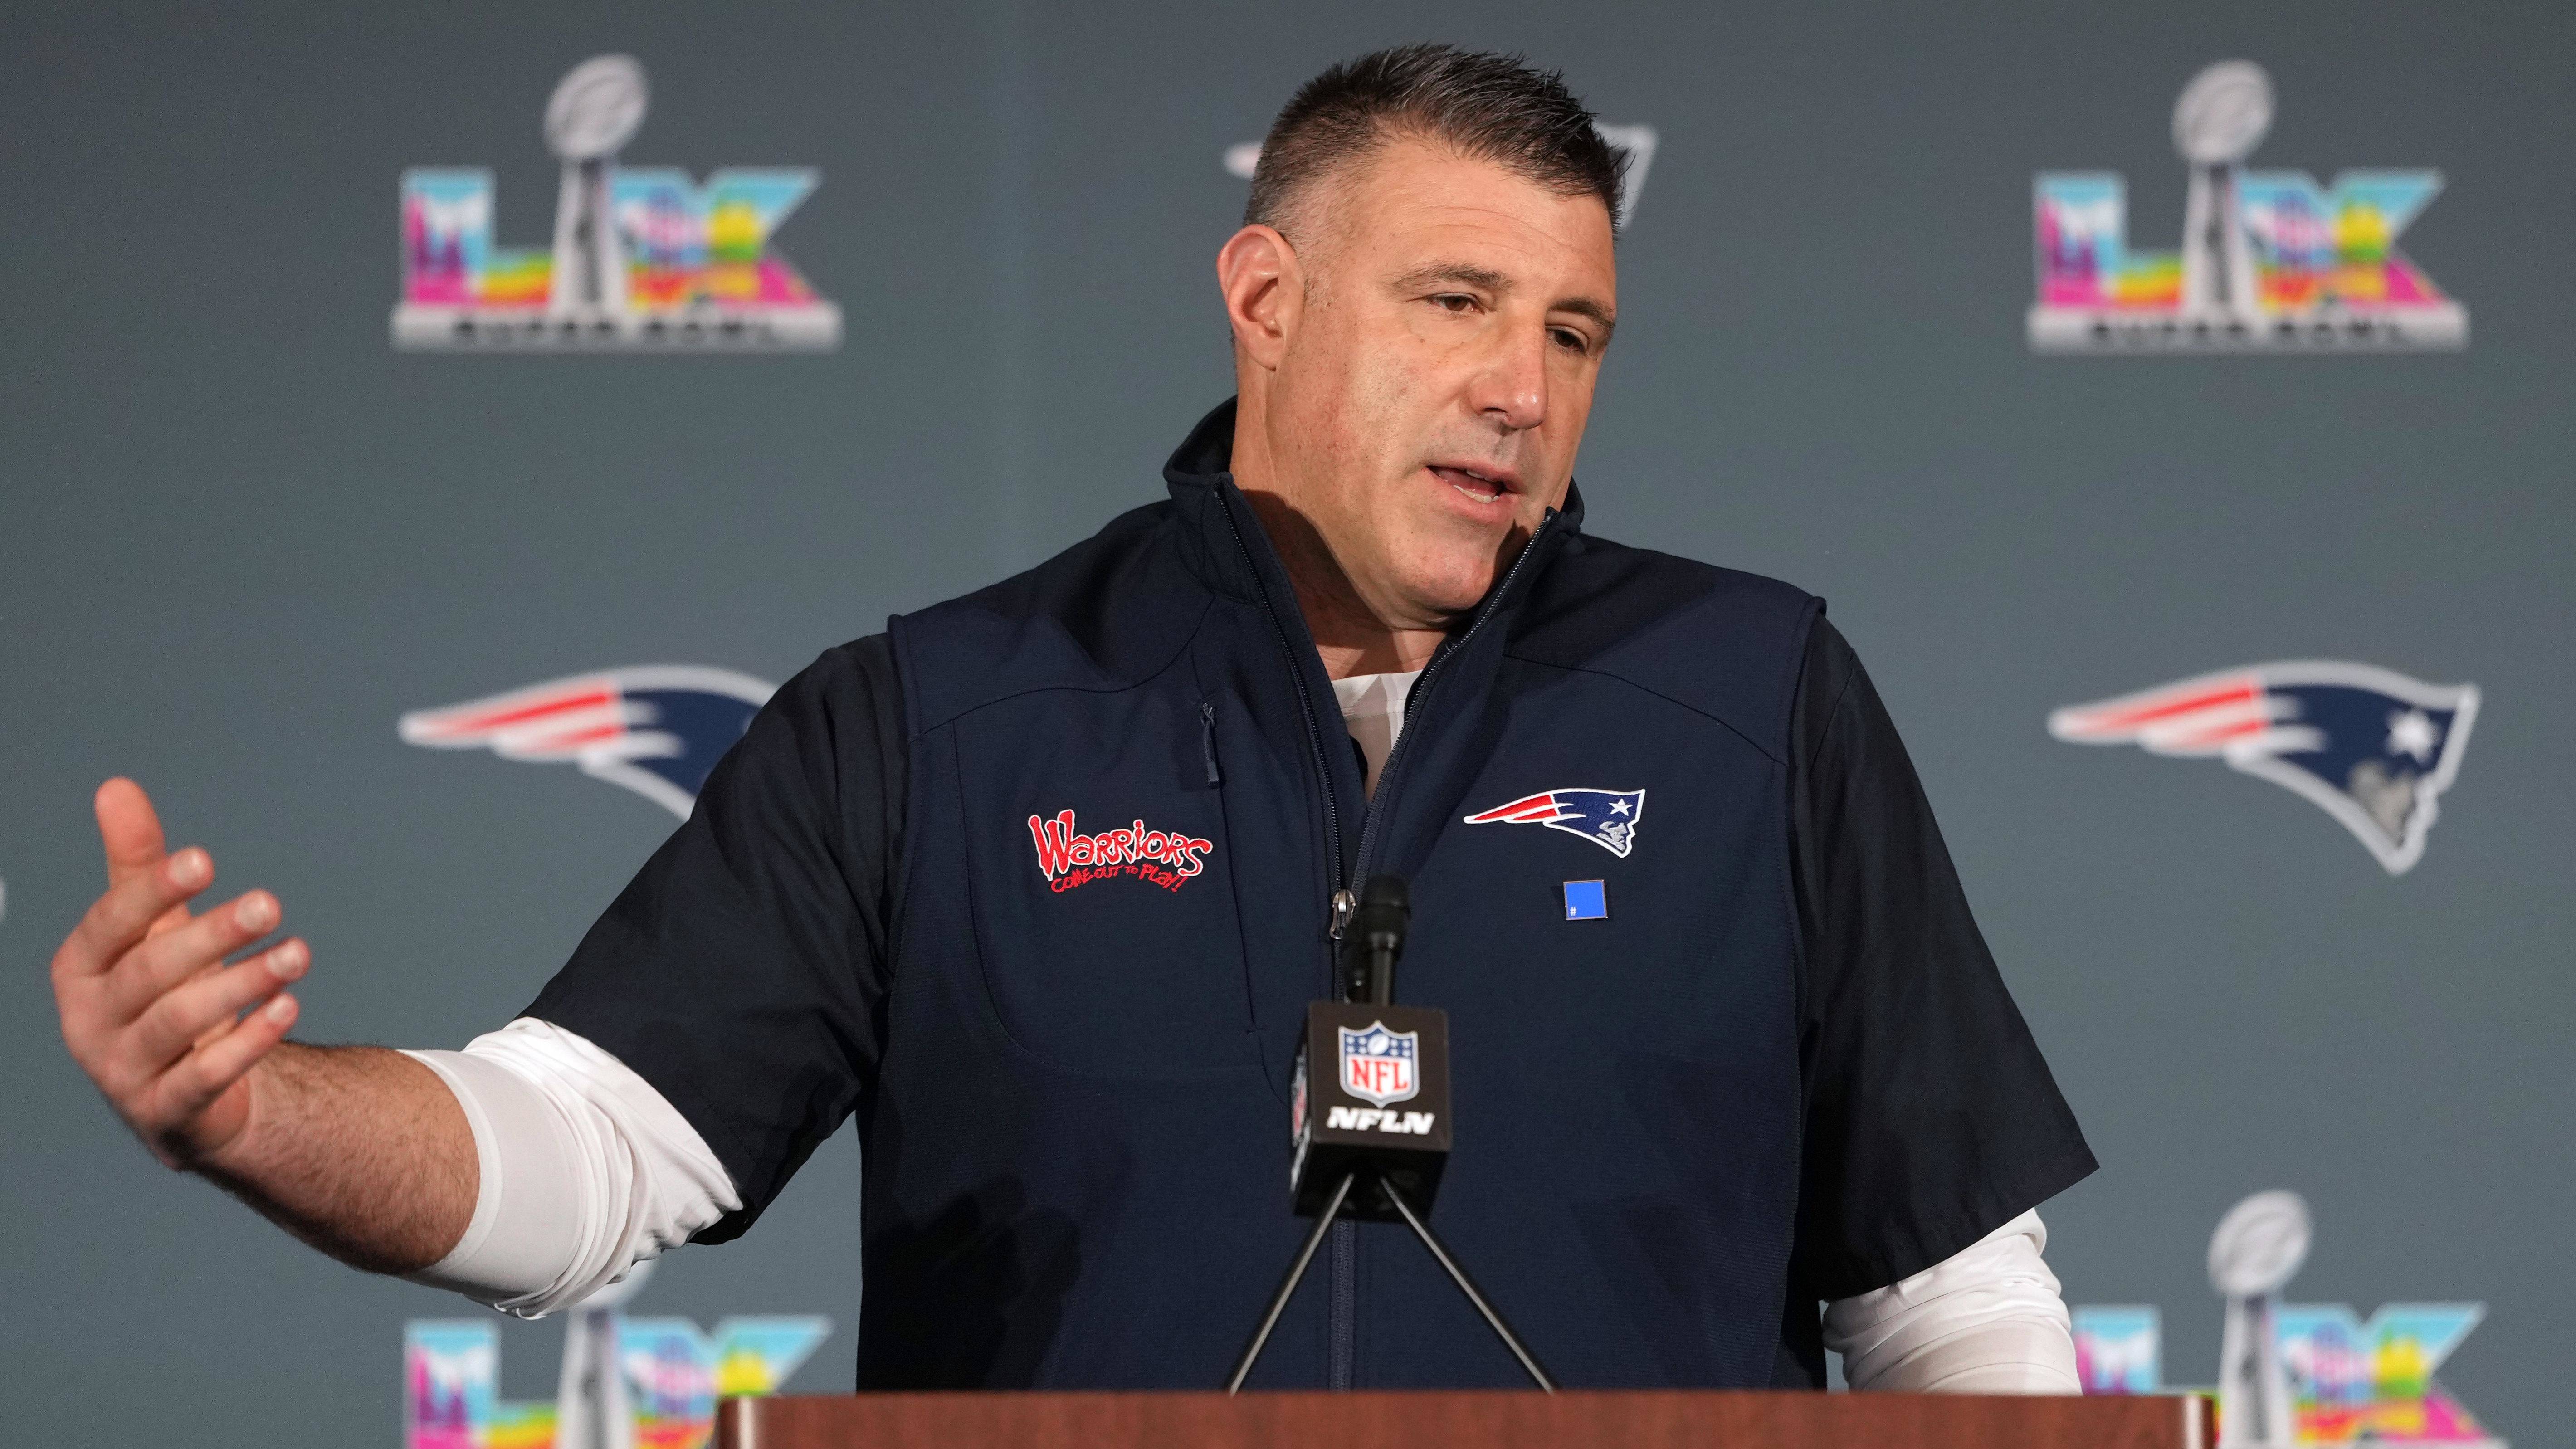
Mike Vrabel’s Face-Tingling Energy Drink Has Become Part of Patriots Culture

Conor Orr

He chugs it before meetings. He updates players on his daily consumption. ‘I am amazed,’ one player says.

READ MORE 

Join the SI Boxing Newsletter

A weekly spotlight on the biggest fights, stories and in-depth reporting on boxing, from features to sharp commentary on combat sports.

Click to Subscribe! 

More from Sports Illustrated

  • Why Super Bowl TV Ratings Will Be Down This Year Read More
  • Donald Trump’s ICE Mess Has Spilled Over, Staining Team USA’s Winter Olympics Read More
  • How One Fan’s Paranormal Encounters Could Help the Seahawks Vanquish Their Ghosts Read More
  • Even in Her Victory Lap, Jessie Diggins Is Always Thinking About Others Read More
  • How Seahawks DC Aden Durde Became the Coach Who Could Break a Major Barrier Read More


Get the print edition of Sports Illustrated delivered to your door.

Click to subscribe! 


Sign up for SI Newsletters

Stay ahead of the game—sign up for all of SI’s newsletters, from golf and soccer to MMQB, and never miss a moment.

Get it in your inbox

TikTok
Instagram
Facebook
Threads
X


We may receive compensation for some links to products and services included in this email.

Sports Publishing Solutions Inc.
625 Broadway, 10th floor
New York, NY. 10012
You are receiving this email because you are subscribed to the Sports Illustrated newsletter.

You can unsubscribe here .

Privacy Policy – Terms & Conditions

© 2026 Sports Publishing Solutions Inc. All rights reserved.
SPORTS ILLUSTRATED IS A REGISTERED TRADEMARK OF ABG-SI LLC.
All betting and gambling content included in the Sports Illustrated newsletter is intended for individuals 21+ (18+ in DC, KY, NH, RI, and WY). Betting and gambling content, including picks and predictions, are based on individual commentators’ opinions and we do not guarantee any success or profits. If you or someone you know has a gambling problem, crisis counseling and referral services can be accessed by calling 1-800-GAMBLER or texting 800GAM.

Click this link to view the newsletter in your browser.

The Lithium Boom

February 07, 2026 

The Lithium Boom 

Did you know it takes 10,000 iPhone batteries worth of lithium to make one EV battery pack? With 350M+ EVs projected to be sold globally by 2030, lithium demand is looking steep. 

Current recovery methods involve waiting for liquids to evaporate in ponds the size of 100 football fields. This inefficiency can’t keep up with forecasted demand. But EnergyX’s technology can recover up to 3X more lithium than traditional methods. 

Here’s how they’re redefining the $546B energy storage market: 

  • Disruption: EnergyX’s GET-LiT™ technology recovers lithium from brine at the lowest cost when benchmarked against industry leaders, and it’s protected by 120+ patents. 
  • Ecosystem: From recovery to deployment, EnergyX is building a vertically integrated platform to power the global transition to EVs, backed by investment from leaders like General Motors and Eni. 
  • Opportunity: EnergyX is offering everyday investors the chance to join ahead of full-scale commercialization.

A third-party pre-feasibility study recently confirmed EnergyX’s Project Black Giant™ in Chile has the potential to generate over $1.1B annually at projected market prices once fully operational. 

On top of that, their nearly 50,000 acres of land in Texas and Arkansas has some of the highest lithium concentrations ever recorded in the U.S. 

Even better? You can claim your piece of this early-stage opportunity and become an EnergyX shareholder today.

Disclaimer

This is a paid advertisement for EnergyX’s Regulation A+ Offering. Please read the offering circular at invest.energyx.com. Under Regulation A+, a company has the ability to change its share price by up to 20%, without requalifying the offering with the SEC.

Update your email preferences or unsubscribe here

111 SE 1st Avenue
Delray Beach, FL 33444, United StatesTerms of Service 

Your Northern Cardinal is waiting—claim yours today

Your Northern Cardinal is ready to brighten someone’s day. Start your annual gift now to help protect the birds you love—and receive a Northern Cardinal plush as thanks.Northern Cardinal.

Peter Anthony, Valentine’s Day has long been linked to birds—some scholars even suggest the holiday’s February timing connects to birds’ mating season. So this month, we’re celebrating a feathered classic that feels like a love note in flight: the Northern Cardinal.

With its brilliant color, bold crest, and clear whistled song, the Northern Cardinal can brighten the coldest winter day—and it’s beloved enough to be the official state bird of no fewer than seven eastern states. When you start an annual donation today, you’ll power year-round work to protect cardinals and other birds—and we’ll send a Northern Cardinal plush as a symbolic gift to you or a special someone in your life.Birds urgently need the protection of people who care about them and are ready to help—people like you, Peter Anthony. Last year’s State of the Birds report warns that one-third of U.S. birds need conservation action, and that birds are telling us that the habitats people depend on are vanishing, with declines happening across habitats.

But thanks to support from generous people like you, there are real solutions to the crisis birds are facing. For 120 years and counting, we have preserved habitats, conducted scientific research, influenced policymakers to enact commonsense conservation laws, and engaged communities across the hemisphere to protect the natural resources upon which birds—and we—depend.

Please, Peter Anthony, adopt a Northern Cardinal today and help protect the birds we love—this season and all year long.

With gratitude,

National Audubon SocietyDonate NowPhoto: Michele Black/Audubon Photography Awards120th Anniversary LogoNational Audubon Society
225 Varick Street, New York, NY 10014 USA
(844) 428-3826audubon.org

© 2026 National Audubon Society, Inc.

Pause fundraising emails for two weeks

Update your email preferences or unsubscribe