Bed Bath & Back to Life? An Aggressive Turnaround Takes Shape
Written by Jeffrey Neal Johnson on May 1, 2026
Key Points
Bed Bath & Beyond reported its first meaningful top-line revenue expansion after many consecutive quarters of decline, signaling a potential shift in momentum.
A strategic acquisition spree is transforming the legacy retailer into a fully integrated “Everything Home” ecosystem to capture the entire homeownership lifecycle.
Institutional investors and company insiders are demonstrating strong conviction in the turnaround strategy through significant, recent buying activity.
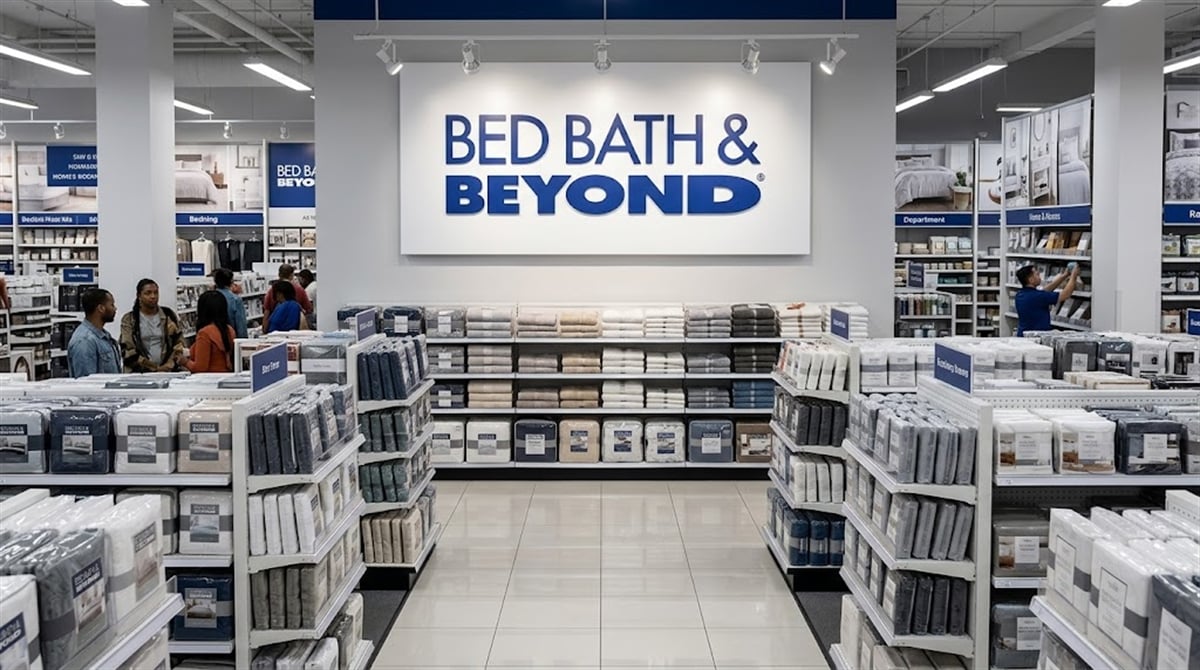
Bed Bath & Beyond (NYSE: BBBY) has executed one of the most aggressive, contrarian turnarounds in modern retail, posting its first top-line growth in nearly five years while systematically acquiring high-value assets across the home services sector. With over a 14% short interest ripe for a squeeze and management ruthlessly extracting $60 million in operational bloat, this high-beta recovery play offers immediate upside as the legacy retailer rapidly transforms into a high-margin Everything Home ecosystem.
When the SpaceX IPO launches, most investors will already be too late. The real opportunity isn’t the IPO itself – it’s the infrastructure behind it.
One small-cap company supplies a mission-critical component to Musk’s xAI Colossus site that can’t be built around. While retail waits for a ticker that doesn’t exist yet, early money is moving into this supplier at a fraction of its potential value.See the small-cap stock powering the SpaceX buildout today
Proof of Life: Revenue Rebounds After Years of Decline
The latest fiscal data reveals a fundamental inflection point. For the first quarter of 2026, a 6.9% year-over-year revenue expansion to $248 million ended a grueling 19-quarter streak of top-line contraction. This critical metric signals that consumer engagement is accelerating.
Underlying the revenue beat is a substantial improvement in profitability. Adjusted earnings before interest, taxes, depreciation, and amortization (EBITDA) improved to negative $8 million, marking the sixth consecutive quarter of year-over-year EBITDA growth.
Gross profit stabilized at a resilient 23.9%, yielding $59 million. Management delivered an earnings per share beat of 6 cents, posting a loss of 25 cents per share against consensus estimates of a 31-cent loss.
While structural unprofitability persists, as evidenced by a negative net margin of 8.1%, the trajectory points toward recovery. By simplifying the organization and consolidating operations, leadership laid a foundation that supports growth without excessive cash burn. Bed Bath & Beyond’s balance sheet retains $163 million in cash and equivalents, providing liquidity to fund near-term operations and manage the integration phase without necessitating immediate dilutive equity offerings.
Building an Empire on Distressed Assets
Revenue stabilization is merely the initial phase of the broader strategy. Management is aggressively shifting from highly competitive, low-margin legacy retail into high-ticket, project-based categories. This structural transition effectively insulates the top line from macroeconomic headwinds impacting discretionary retail spending. By combining product sales, installation services, and financing, the business model increases the average transaction size and builds long-term customer lifetime value.
To accelerate this pivot, Bed Bath & Beyond initiated a massive acquisition pipeline. Recent definitive agreements include a $150 million acquisition of The Container Store and a concurrent $150 million deal for F9 Brands, which brings Lumber Liquidators and Cabinets To Go under the corporate umbrella.
By integrating these assets alongside recent purchases of Kirkland’s Home, Elfa, and Closet Works, Bed Bath & Beyond aims to capture the entire homeownership lifecycle. A homeowner typically remains in a house for 11 to 12 years; the new ecosystem captures spending across that entire timeframe, from furnishings and storage to flooring and kitchen renovations.
Integrating distressed assets introduces operational complexity, but leadership aims to achieve $60 million in annualized cost savings through asset consolidation and extraction over the next nine months. Removing duplicative administrative, supply chain, and technological overhead will offset the capital requirements of the expanding portfolio.
When the SpaceX IPO launches, most retail investors will be locked out. The banks, funds, and insiders get in early – while everyone else waits on the sidelines.
But one small infrastructure supplier – a critical piece Musk can’t scale the Colossus network without – is still trading well under institutional radar. A new briefing reveals the name and ticker at no cost.Get the SpaceX infrastructure stock name and ticker here
Leadership Realigns to Power a Tech-Forward Strategy
Executing a multi-brand ecosystem requires specialized oversight and seamless technological integration. The appointment of Amy Sullivan as President ensures cohesive integration across the retail and home services pillars. The addition of Kyla Robinson to lead technology transformation highlights a commitment to modernizing the data infrastructure. By launching a unified customer identity layer in partnership with Bilt, Bed Bath & Beyond is positioning itself to maximize customer lifetime value through targeted engagement. The Bilt platform will operate as a shared intelligence layer across the portfolio, providing a single sign-on profile and flexible rewards tied to lifestyle and services rather than isolated transactions.
Volatile Setup: The Smart Money Piles In
Wall Street recognizes the fundamental improvements. Institutional ownershipstands at a commanding 76%. Over the trailing 24 months, institutional capital flows show $85.43 million in buying against just $23.16 million in selling. Recent filings reveal that Able Wealth Management initiated a massive 844,600-share position. Insider conviction also remains strong, with Director Joseph J. Tabacco Jr. acquiring 20,000 shares on the open market for approximately $102,200.
Despite institutional accumulation, bearish sentiment remains elevated. Short interest climbed month over month to 9.07 million shares, or around 14% of the public float. With a days-to-cover ratio of 4.7, the stock is heavily exposed to a short squeeze. Recent market action demonstrated this volatility, with the stock surging nearly 35% intraday on heavy call option volume before facing aggressive profit-taking. Trading volume eclipsed 42.89 million shares, a massive 1,725% surge in relative volume.
For momentum traders, the 3.01 beta confirms extreme sensitivity to market catalysts. From a valuation standpoint, the stock trades at a deeply discounted trailing price-to-sales ratio of 0.31X. This multiple offers a wide margin of safety relative to broader retail sector peers, many of which trade closer to 0.8X sales. The discounted valuation prices in integration risks while leaving upside potential if management achieves its cost-reduction targets.
All Eyes on May: The Upcoming Shareholder Vote
The transformation from a legacy retailer into a diversified home services conglomerate is accelerating. The upcoming shareholder vote, scheduled for May 14, 2026, is the next critical catalyst. This vote will formalize the strategic direction and finalize the aggressive merger pipeline, specifically the transactions for The Container Store and F9 Brands, which are expected to close in July 2026.
Investors might want to add Bed Bath & Beyond to their watchlist as the company demonstrates progress toward sustained profitability. Those with a higher risk tolerance could monitor the options chain and short interest data for indicators of momentum shifts leading up to the May 14shareholder vote.
Thank you for subscribing to DividendStocks.com’s daily newsletter for dividend and income investors that covers ex-dividend stocks, new dividend declarations, dividend stock ideas, and the latest market news.
If you have questions or concerns about your newsletter, please don’t hesitate to contact our South Dakota based support team at contact@marketbeat.com.
If you no longer wish to receive email from DividendStocks.com, you can unsubscribe.
BIG SCREEN. BIGGER MOMENTS.Get breaking news, big games, and binge-worthy shows in stunning 4K*. Plus, watch up to four streams at once with MultiView. All from the comfort of your couch.
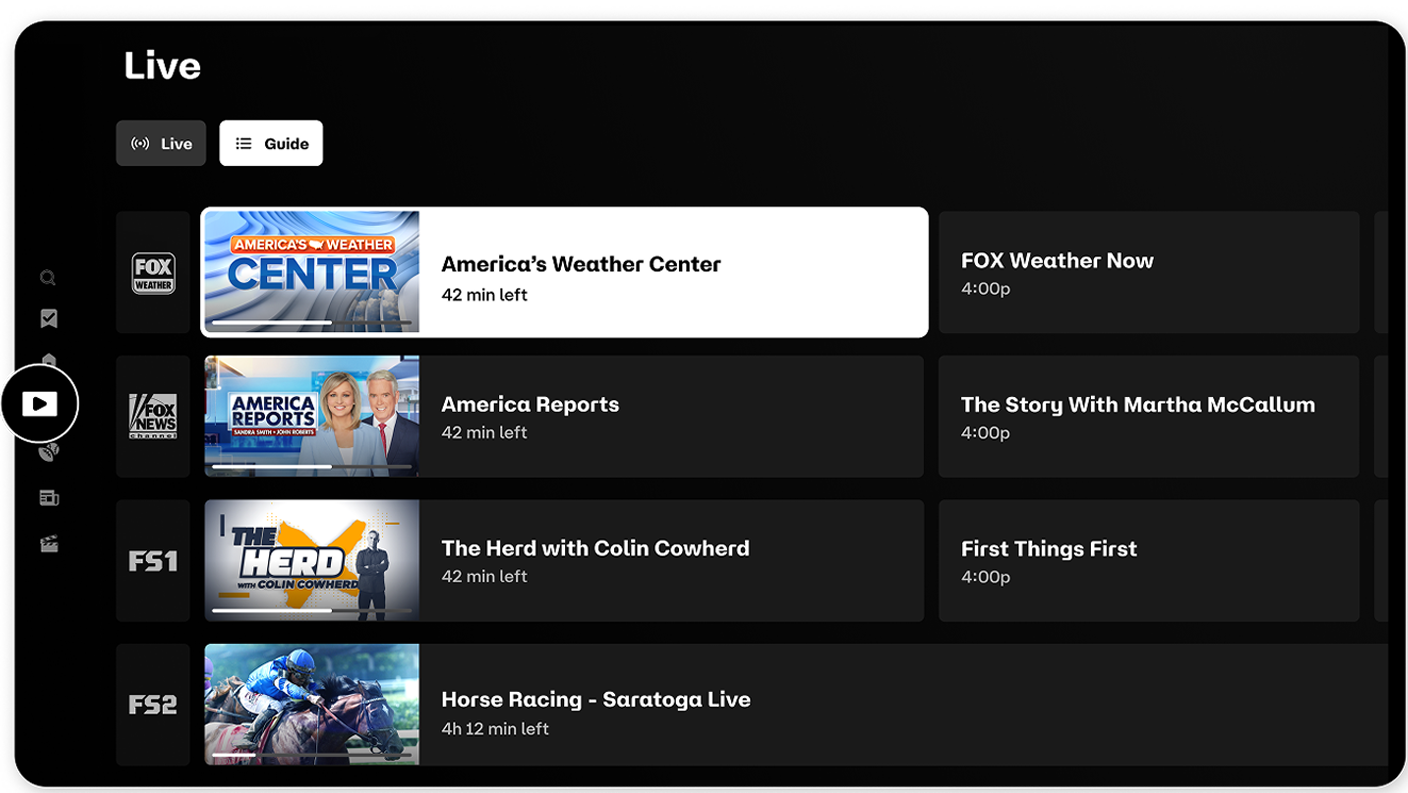
Start Streaming From MLB thrills and NASCAR racing to NFL showdowns, breaking news and favorite primetime shows, FOX One brings it all together—live, loud and unfiltered. 24/7 CHANNELSFOX channels are always on—perfect for big-screen viewing. Find the Guide on the LIVE tab to see what’s playing now and what’s next. NEVER MISS A MOMENT Record your favorite shows or games by adding them to My Stuff, or add leagues and teams to record every game that matters. CATCH UP WITH HIGHLIGHTSTied up during game time? Catch up with highlights then instantly join the game live. Can’t pick just one game or newscast? MultiView lets you watch live curated streams on your TV—side by side, all in one screen. AVAILABLE WHERE YOU WATCH DOWNLOAD THE FOX ONE MOBILE APP Follow Us:
Do you have a question? Click here to visit our Help Center. Please do not reply to this message.
Today’s Night Prayer is brought to you by Rosary.com
A Night Prayer
Jesus Christ, my God, I adore You and thank You for all the graces You have given me this day. I offer You my sleep and all the moments of this night. I place myself and all my loved ones, wherever they may be, in Your sacred side and under the mantle of Our Blessed Mother. Let Your holy angels stand watch and keep us in peace. Amen.
Quote of the Day
“You cannot put straight in others what is warped in yourself.” -St. Athanasius of Alexandria
Today’s Meditation
“That is the essential word: mission. Everyone who is baptized, if he understands the part he has to play, is a missionary. He may not be called upon to go to foreign lands; his apostolate may be destined only to affect his near neighbors. But he must understand that wherever he may happen to be, he has a function to perform there: he not only has to save himself, but he also has to sanctify and save his brethren.” —Raoul Plus, S.J.
Here at Rosary.com, we recognize that we’re more likely to pray the Rosary if we have one we absolutely love. That’s why our designers hand-select each bead, crucifix, and centerpiece to reflect beloved devotions such as Immaculate Conception, Undoer of Knots, patron saints, and more!
With sacrament season, Easter, and even Mother’s Day coming quickly, now is the time to find a gift for a devoted Catholic in your life…or to refresh your own collection.
Personalize select pieces to create unique gifts, or to fashion the perfect piece that you’ll love to pray with.See Them All
The daily examination of conscience is an ancient Catholic practice. It’s very simple, and it’s designed to help us identify our sins and weaknesses so that we can improve and grow stronger in the spiritual life, while providing an excellent ongoing preparation for regular Confession. It consists of taking a few minutes at the end of the day to prayerfully review our actions in the light of God’s commandments, followed by the Act of Contrition.
Reflect on the victories and losses
Actively reflecting on the high and low points of the day can help you live more intentionally and bring a renewed sense of resolve into the following day.
Review your actions, words, and thoughts today. Did you actively guard yourself against temptation? Where did sin creep in?
In what moments did you practice virtue and moral courage?
Were you attuned to the Holy Spirit’s promptings today? Where did you feel His inspiration?
Ask Him for the graces necessary to follow His Will more purposefully tomorrow.
Act of Contrition
O my God, I am heartily sorry for having offended Thee, and I detest all my sins because of Thy just punishments, but most of all because they offend Thee, my God, Who art all good and deserving of all my love. I firmly resolve with the help of Thy grace to sin no more and to avoid the near occasions of sin. Amen.
Practice gratitude
It is God’s love that has brought you into existence and to this exact moment. Practice looking for His hand in your day.
Where did you feel His loving gaze upon you today?
What people or moments helped you see God in your life?
Thank God for all these moments!
Ask Him to help you recognize His blessings and providence tomorrow.
Renew your commitment to Christ
Remember: our Faith is founded upon a Person—Christ! Renew your personal love and devotion to Him.
Thank God for the gift of His Son Jesus and our call to be His disciples.
Tell the Lord of your desire to know Christ more personally.
If possible, set an intention for your day tomorrow. Ask Our Lord to guide you in this act.
Pray a Hail Mary, Our Father, or another beloved prayer.
Rest with God
Praise Him, sun and moon, praise Him, all you shining stars! — Psalm 148:3
The past few days and weeks and months have been dark ones indeed for the suffering Jewish people. They have been attacked again and again, shattering tens of thousands of lives. At the same time, much of the world is blaming the problem on them instead of those who hate and attack them. They need a light of hope today. Will you be part of that light? Together we are telling, and more importantly showing, the people of Israel that they are not alone. We have received a generous matching gift challenge that will double your gift to help twice as many people—so please be as generous as you can when you send your gift today.
Your support of the Friends of Zion today allows us to comfort the people of Israel who have been devastated by the war, continue to purchase and deliver food, medicine, clothing, and other necessities of life for the poor Holocaust survivors and refugees of Ukraine, continue to operate the Friends of Zion Museum, and to meet urgent humanitarian needs among the poor Jewish people living in Israel.
Thank you so much for being part of this vital worldwide prayer movement.DONATE NOW
Weekly Prayer Service
Pray with us for Israel and submit your prayer requests.
“Lord, I pray today for the safety and security of the inhabitants of Jerusalem. Their enemies are many; their friends are few. Let me be a faithful friend to them. And I ask that for the sake of Your righteous Name You will defend and deliver them from evil.”
In those days shall Judah be saved, and Jerusalem shall dwell safely: and this is the name wherewith she shall be called, The LORD our righteousness. Jeremiah 33:16
Join with us and millions of others around the world in prayer for Israel:PRAY WITH US
IDF downs Hezbollah drones, strikes dozens of terror targets in Lebanon
The Israel Defense Forces said on Friday that it had intercepted at least four drones launched by Hezbollah, while the outcome of a fifth interception attempt remained under review.READ MORE
London police charge man with attempted murder in antisemitic Golders Green stabbing attack
British police on Friday said they had charged a 45-year-old man with two counts of attempted murder following an antisemitic attack during which two men were stabbed in Golders Green, north London, earlier in the week.READ MORE
Stay Connected
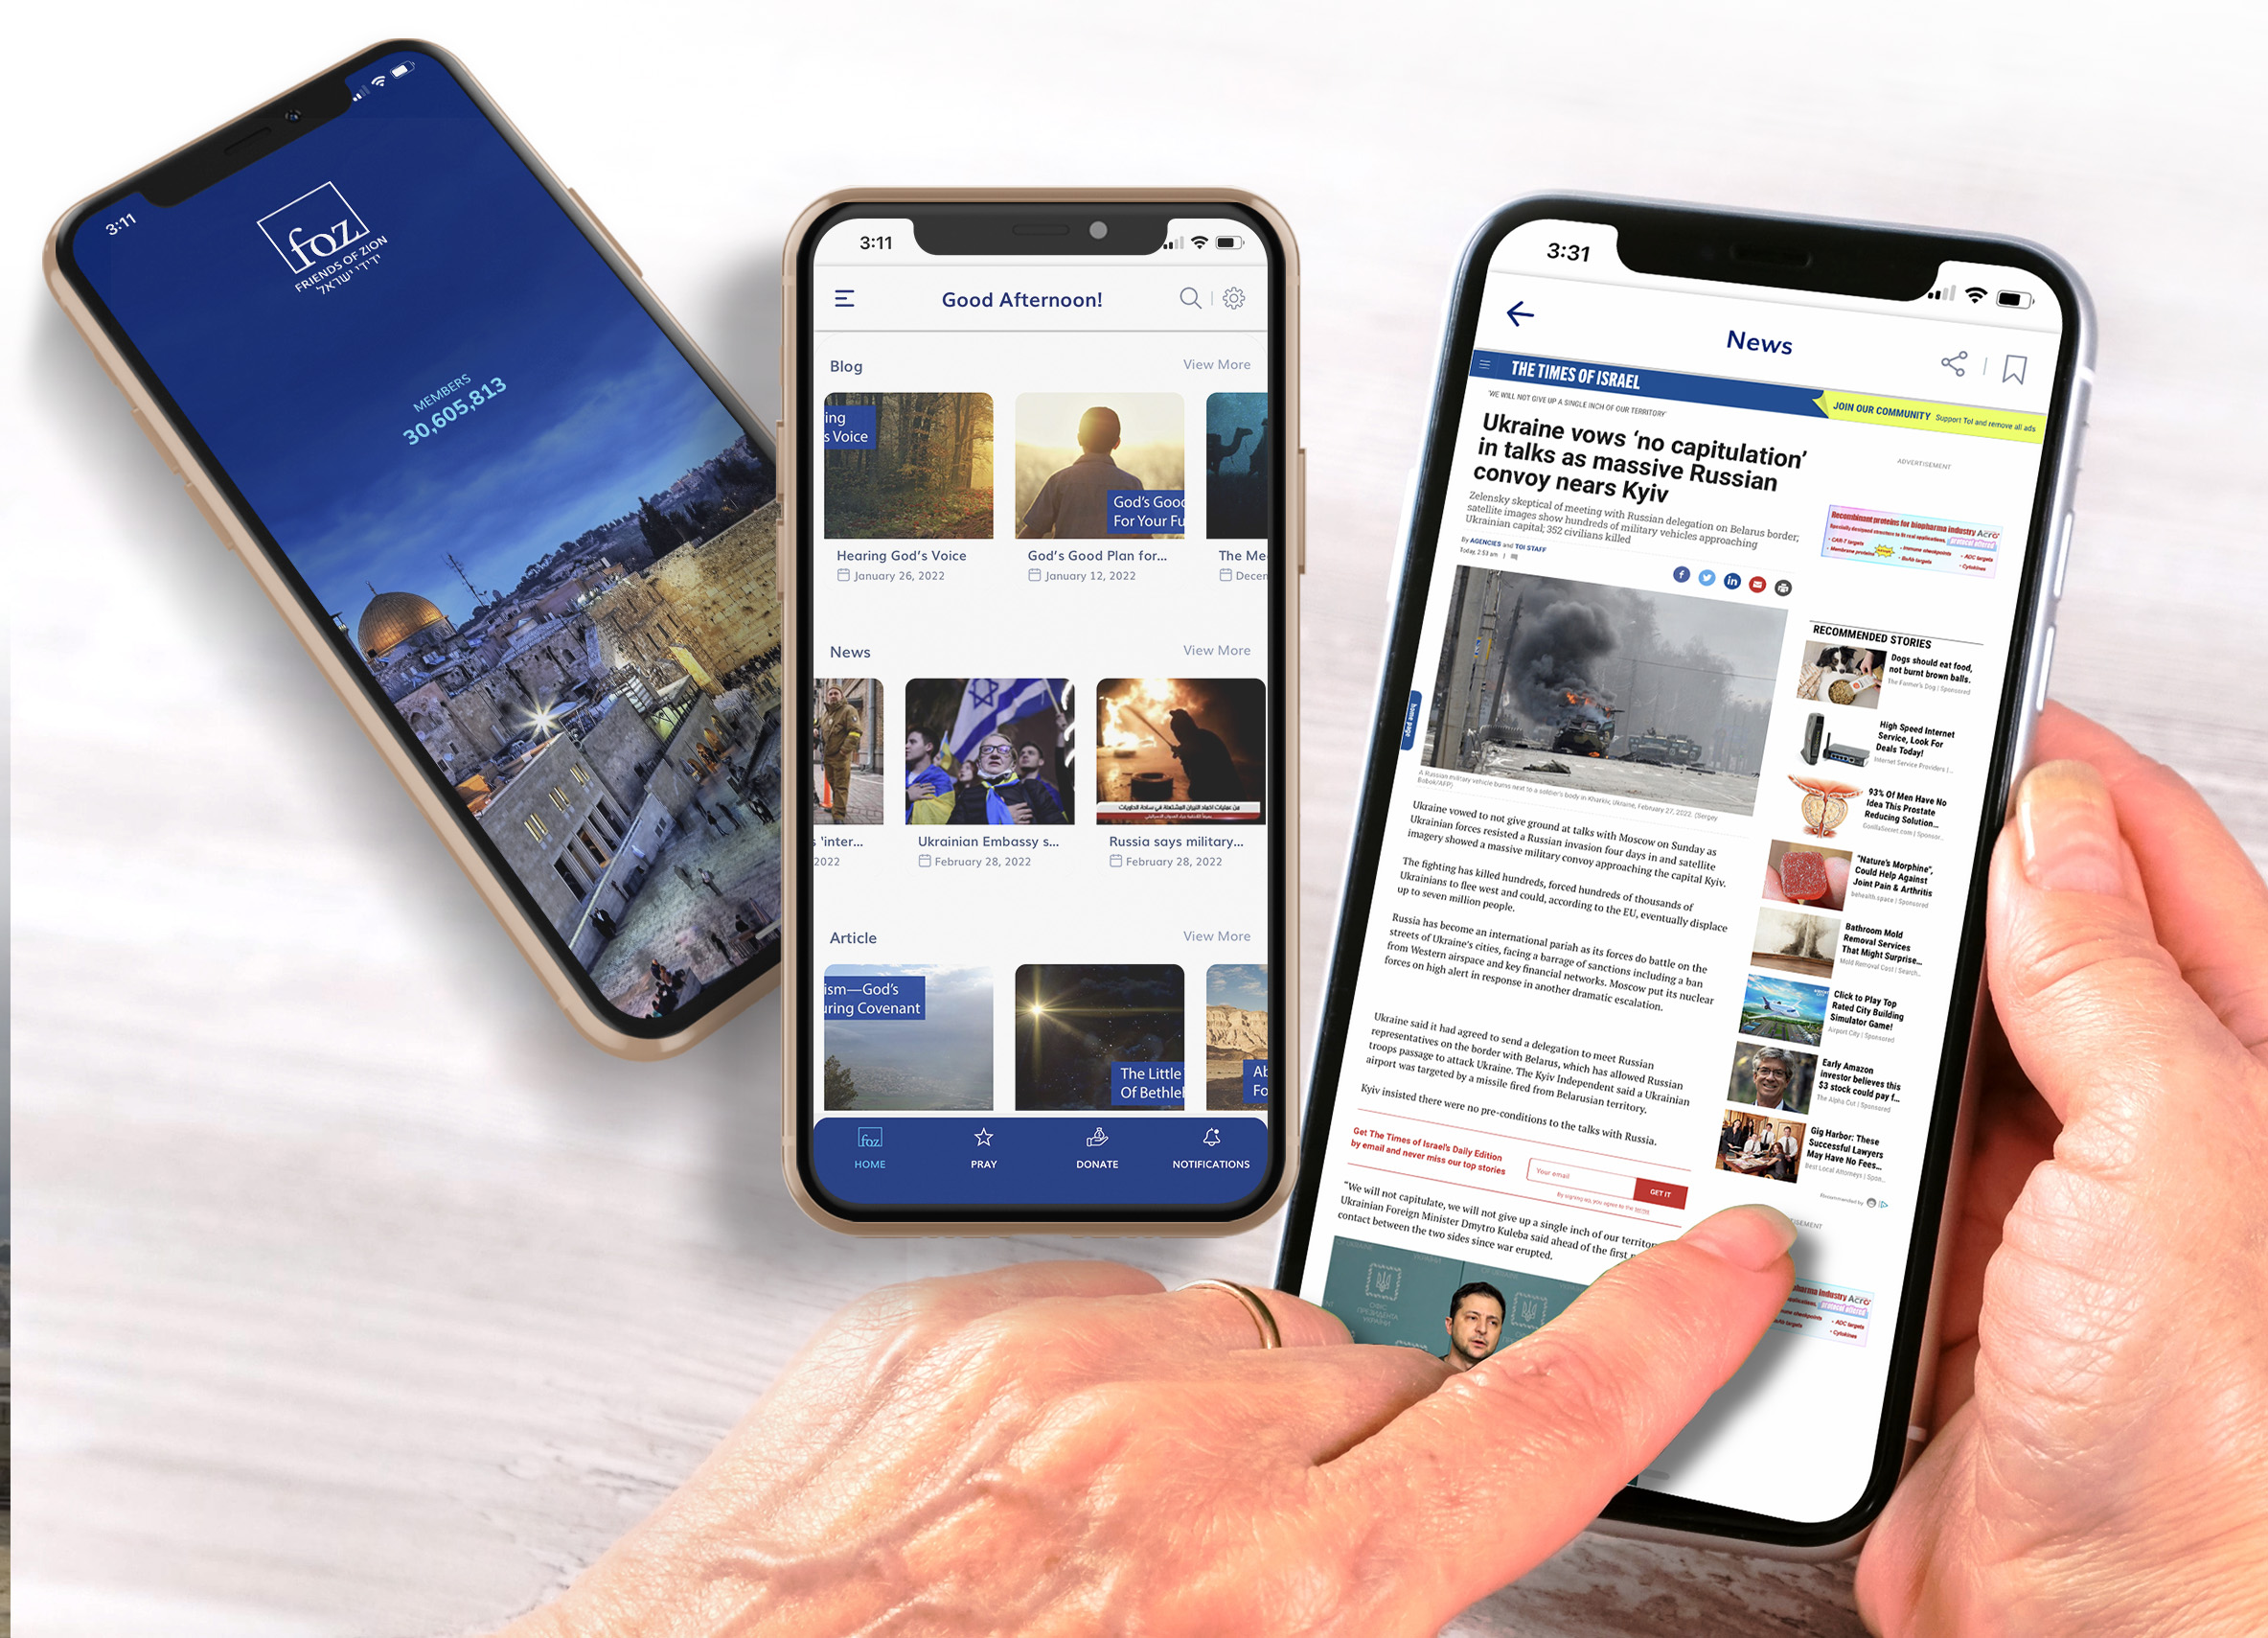
There is no better way to keep up with what is really happening in Israel and the world—the truth the liberal media won’t tell you—than with the redesigned and upgraded FOZ app. We have prepared this app to allow us to stay in touch with you and provide the most up-to-date news and prayer requests. This powerful tool will help you shape and focus your prayers, receive updates from Dr. Evans, and so much more. It is a must-have for every friend of Israel.APPLE APP ANDROID APP DONATE NOW
Good morning, I’m Dan Gartland. The Kentucky Derby is tomorrow. I got to go to Churchill Downs a few weeks ago to see every inch of the historic track, from the most exclusive seating areas to the barns where some of the most expensive horses in the sport are housed. See it all in the latest edition of our Stadium Wonders video series.
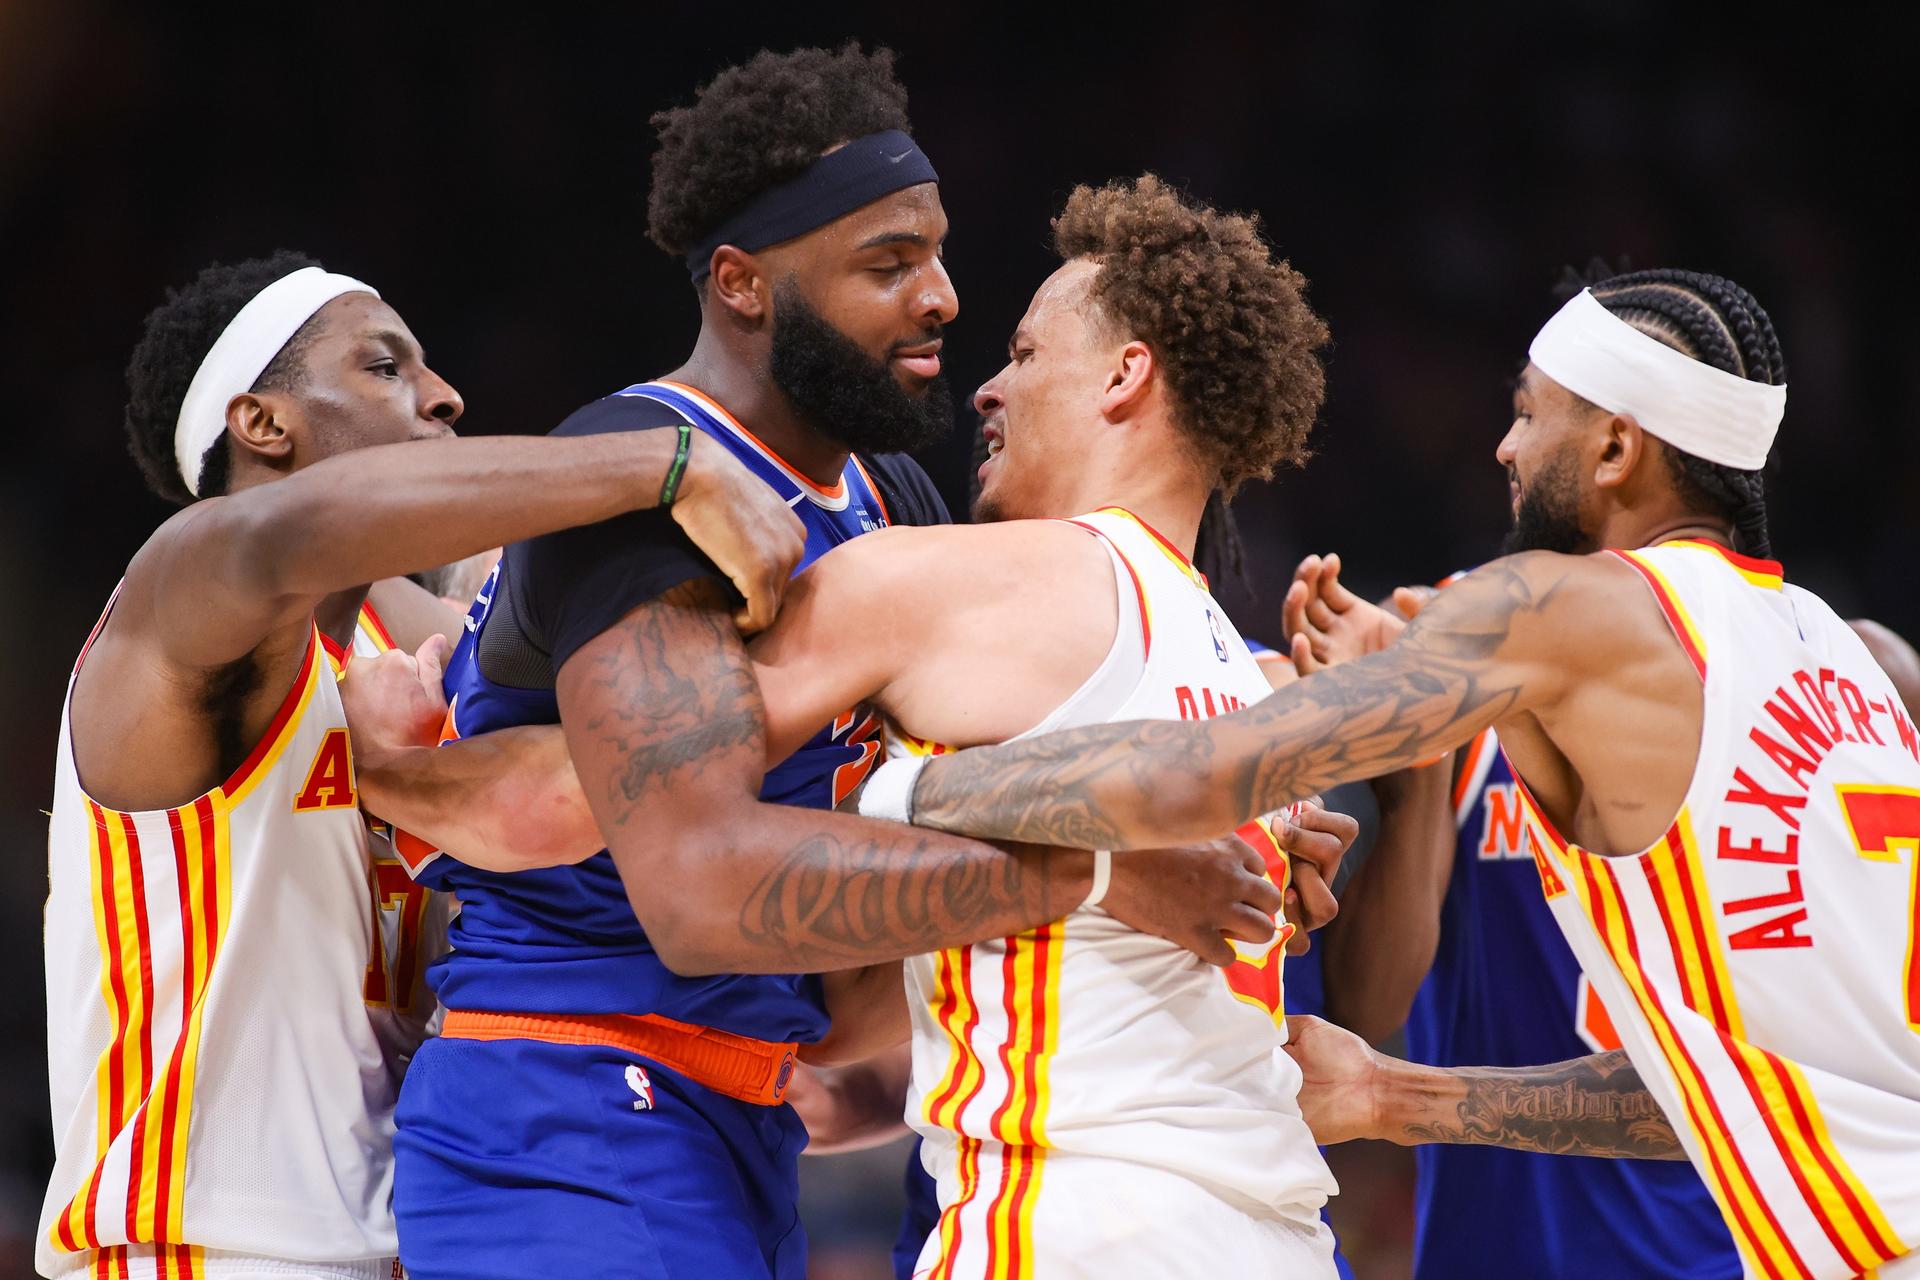
The stakes in Game 6 of the Knicks-Hawks series on Thursday night couldn’t have been clearer. Atlanta, which had previously held a 2–1 lead in the series, needed to recapture that magic and win at home to force a decisive Game 7.
It was baffling to watch. The deficit just kept getting larger and larger, and had already grown insurmountable before the second quarter was halfway over. And yet the game had to proceed as normal. The Atlanta rapper Yung Joc still performed at halftime. The PA system still played the music cues meant to entice the fans to chant “de-fense” and, most comically, the screeching hawk sound effect after an Atlanta three-pointer. Again, all while the deficit hovered around 50 points. The ESPN broadcast team of Mike Breen, Richard Jefferson and Tim Legler had to fill time like they were calling a lopsided baseball game on a Wednesday afternoon in August.
The best part of a game like this is gawking at all of the unbelievable stats and facts. Here are a few of my favorites. CONTINUE DAN’S COLUMN ON SI
In his latest notebook, Chris Mannix reports that there could be more cost-cutting moves coming from the new Trail Blazers owner. He also discusses Steve Kerr’s push to eliminate the three-point line and whether coach Jamahl Mosley is still on the hot seat in Orlando.
3. Justin Crawford’s hustle to beat out an infield single for a walk-off Phillies win. That was the first game of a doubleheader against the Giants. Alec Bohm’s walk-off sacrifice flygave the Phillies the win in the nightcap, marking the first time since 2004 that a team won both games of a doubleheader via walk-off.
In the latest installment of Where Are They Now, SI catches up with Kevin Ware, a player on Louisville’s 2013 national championship team who became known for a devastating injury during March Madness. Ware talks about his life after the injury and where his basketball journey took him after Louisville.
Join the SI Boxing Newsletter
Sports Illustrated’s Chris Mannix provides a weekly spotlight, featuring in-depth reporting and sharp commentary, on the biggest fights and stories inside the ring.CLICK TO SUBSCRIBE
We may receive compensation for some links to products and services included in this email.
Sports Publishing Solutions Inc. 625 Broadway, 10th floor New York, NY. 10012 You are receiving this email because you are subscribed to the SI:AM newsletter.
Featured: NVDA – The Options Market Feels a Little Too Comfortable.
Editor’s Note: The tech expert behind 28 triple-digit winners just uncovered a story involving Elon Musk and the White House that could be bigger than Tesla, SpaceX and xAI combined. Learn more before the “mother of all IPOs.”
Dear Reader,
Washington is about to send shockwaves through the stock market once again…
Not one but two Executive Orders are forcing the Treasury, the IRS, the Department of Homeland Security, and five other federal agencies to prepare America’s entire financial system for a radical new era.
And the man at the center of this new era is, once again, Elon Musk.
This isn’t speculation… a massive rollout has just begun across 50 states.
And what happens next involves more money than SpaceX, Tesla and xAI – COMBINED.
My name is Luke Lango. I was ranked the #1 stock picker in America in 2020. My readers have had the chance to see gains as high as AMD +13,500%… Nvidia +5,000%… Palantir +1,200%.
But I’ve never seen a setup like this one.
When the President of the United States personally clears the path for the world’s richest man’s biggest project to date… investors should pay attention.
Luke Lango Senior Investment Analyst, InvestorPlace
P.S. The last time I spotted an opportunity like this, my followers had the chance to make as much as 31,000% over a decade. This time, with the White House already onside, I think the opportunity could be even bigger. Learn more here.
FEATURED ARTICLE
NVDA: The Options Market Feels a Little Too Comfortable.
And what’s funny (not funny) is how calm the options market can look when everyone knowsit’s a live wire. Nvidia earnings tends to do that thing where the narrative is “historic numbers” and the stock response is… fine. Slightly disappointing. Then everyone who paid up for premium spends the next morning staring at IV crush like it’s a personal insult.
As I’m writing this, NVDA is hanging around the $200 area, about 8% off the 52-week high (~$216.83). Big cap, big expectations, still not “cheap” on trailing metrics (around 40.7x), but also not priced like a dying hardware company. So the setup isn’t about valuation. It’s about reaction.
Here’s the thing: the market is pretty good at pricing the number. It’s worse at pricing the mood.
Quick rewind. The last fiscal Q4 (reported late February) was ridiculous in the literal sense: $68.1B revenue (up 20% sequentially, 73% YoY). Full fiscal year revenue was $215.9B (up 65%), and non-GAAP EPS for the year was $4.77. That’s not “beat and raise.” That’s a different category.
Then management guided for roughly 77% revenue growth in the current quarter. Consensus is sitting around ~79%, which is basically Wall Street saying: “Cool, but do the thing you always do and beat the guide anyway.” That’s the bar now. It’s a moving bar, and it’s higher than most people admit out loud.
Also: hyperscalers were just over 50% of data center revenue last quarter. The combined capex track for Alphabet/Amazon/Meta/Microsoft has been floating around $700B for the year. That’s the demand pool. NVDA is still the cleanest expression of it, whether we like how crowded the trade is or not.
The part people skip: implied vs what actually happens
NVDA’s average 1-day realized move around earnings over the last five reports is about 6.32%.
And the last four one-day reactions: -5.46%, -3.15%, -0.79%, +3.25%. So if you’ve been buying the “it’s NVDA, it has to swing” story, the tape has been quietly taking money from you. Over and over. Not because the company is weak—because expectations are already inhaled.
Slight tangent, but it matters: remember the February 2025 “DeepSeek kills GPU demand” panic? That was the last time I saw people truly lean into a bearish narrative that felt sticky. The stock dropped hard post-earnings that cycle (about -8.48%). And then… inference needs kept growing. The “demand goes away” trade has had a rough life since.
So going into May 20, the question isn’t “Will they beat?” The question is “How much do you have to beat by to get paid for owning volatility?” Because if IV is elevated into the event (and it usually is), you’re not just betting on direction. You’re betting on a reaction that clears the premium. That’s harder than it sounds.
Where I’m at on structures (not a “checklist”, just how I’m framing it)
If you’re bullish but don’t love paying full freight into an IV spike, I keep coming back to a defined-risk call spread in the first full week after earnings (the May 28 expiration). Something like the $210/$230 call spread is at least the right shape: you’re expressing upside while limiting how much IV drag can ruin your day.
If you think we get the same movie again (strong print, “good but not good enough” reaction), then a defined-risk premium sell is the cleaner expression. Short straddle logic, but with guardrails: an iron condor centered near spot with wings beyond roughly that ~6–7% realized neighborhood. You’re basically saying: “I don’t need to be a hero, I just need implied to be too expensive.”
What matters is… the bear risk isn’t just “macro” or “valuation.” It’s guidance language. Supply. Constraints. Any hint that the bottlenecks migrate from gaming into data center commentary, or any tone shift that makes the next-quarter bar feel even slightly less automatic, and the reaction can get sharp fast. That’s the part I’m not casual about.
Date check: May 20 after the close (binary event, no ambiguity)
The day-before habit: price the straddle the morning of May 19 and translate it into % of spot
IV reality check: if IV percentile is up in the 70s+, I start leaning “sell structures” unless I have a very specific directional view
Watchlist between now and then:hyperscaler capex chatter + any sudden “spend digestion” talk (that’s usually where the air pocket starts)
And yeah, this is the annoying part: the market can be right about the move and still make most people wrong about the trade.
If you want, I can map the exact implied move math (and what wings would look like around it) once we see where spot and the front-week IV settle—because that’s when it stops being theory and turns into a trade you can actually live with.
May 20 is close enough that the pricing will start to get honest. Or at least… honest-ish. We’ll see.
This content is for informational purposes only and should not be considered financial advice. Investing involves risk.
The Cheap Investor is a publication of Investing Media Solutions, LLC.
Delivering World-Class Financial Research Since 1999
Six more months of energy winter… Laying mines versus finding them… The real headwind for the stock market… The AI boom is falling apart… From tech adventure to smokestack hunting… There’s a reckoning ahead…
No matter when the war ends, higher oil prices are here to stay…
Last week, the Washington Post spelled the problem out perfectly:
It could take six months to fully clear the Strait of Hormuz of mines deployed by the Iranian military, and any such operation is unlikely to be carried out until the U.S. war with Iran ends, the Pentagon has informed Congress – an assessment that means the conflict’s economic impact could extend late into this year or beyond.
So even if the conflict were to end tomorrow, it could take another six months (at least) before oil flows freely through the Strait of Hormuz. It’s like energy Groundhog Day. The little fellow saw his shadow and now we have at least six more months of energy winter.
You see, although the U.S. Navy has destroyed many of Iran’s larger ships, the country still has plenty of small, fast boats to deploy mines in the strait.
Iran has reportedly deployed two basic types of mines: The Maham 3 is an anchored mine deployed in waters up to 328 feet deep, and the Maham 7 sits on the seafloor in shallower waters. And neither of these mines explode through contact. They’re triggered by magnetic and acoustic sensors capable of detecting passing ships.
The impact of all those mines was expressed well by an April 9 Lloyd’s List report… There are more than 600 commercial ships trapped in the Persian Gulf, including 325 oil tankers. The human toll is even more staggering. An April 29 report from Ynet Global estimates there are 20,000 sailors trapped on as many as 2,000 ships.
The ultimate problem is that laying mines is much easier than figuring out where they are…
Even though Iran left navigable shipping lanes unmined for ships prepared to pay a toll, it admits it doesn’t know where all its mines have been laid. At least, that’s what it claimed when President Donald Trump requested it allow more ships to pass through the strait.
Meanwhile, Brent crude, the global benchmark for oil, has been through a distinct “war on”, “war off” cycle over the past month.
After surging to a four-year high of $118.35 per barrel on March 31, it quickly retreated to $90.38 by April 17, when folks were confident that Trump might soon end the conflict. When it became apparent that the term “ceasefire” doesn’t mean everybody will stop shooting, Brent took off again, topping $118 per barrel. It recently traded around $114, signaling we’re still in war-on mode.
But the verdict from the stock market is clear… $100-plus oil is no problem…
Yesterday, the Nasdaq Composite Index and S&P 500 Index reached new all-time highs.
The S&P 500 is now trading at 31 times earnings and 40.9 times cyclically adjusted price to earnings (“CAPE”). That’s 8% shy of the highest level in history, going back to 1871.
The highest CAPE ratio ever was 44.2 in December 1999, a few months before the dot-com peak.
The Internet has been an incredible economic boon, creating massive wealth and new opportunities, including businesses now worth trillions of dollars.
And yet, that didn’t keep the stock market from becoming insanely overvalued and risky – even for “no brainer” investments like fast-growing, cash-gushing “Internet plumbing” provider Cisco Systems (CSCO). Cisco was the No. 1 Internet-darling stock of the late 1990s. It became so overhyped and impossibly overvalued that it didn’t eclipse its March 2000 high until December 2025.
We’re seeing a similar situation play out today with the AI bubble. It will no doubt create trillions of dollars of business value in whole new industries, some of which probably don’t even exist yet.
But just like with the Internet revolution, a lot of folks are buying a bunch of stocks that are going to get murdered once the bubble deflates, as they always do.
In short, the most likely headwind for U.S. stocks isn’t oil – it’s AI…
Right now, everybody is excited about AI’s possibilities. The current AI market darlings are performing well. Only Meta Platforms (META) has failed to outperform the overall market since the March 30 bottom.
However, the biggest AI data-center builders’ balance sheets continue to deteriorate. Nobody cares about it now, but I (Dan Ferris) suspect the day will come when that matters more than anything else.
As a group, Oracle (ORCL), Microsoft (MSFT), Alphabet (GOOGL), Meta, and Amazon (AMZN) had net cash of $116 billion at the end of 2021. Today, after borrowing hundreds of billions of dollars, these hyperscalers have net debt of $223 billion. And as you can see in the chart below, their borrowing levels have been rising rapidly since the end of 2024.
They’re taking on debt to invest massive amounts of capital into AI. In 2023, their capital expenditures (“capex”) were $149 billion as a group. Over the last 12 months (“LTM”), their capex has ballooned to $482 billion. It will easily exceed $700 billion by this time next year.
That’s a lot of new debt for capex that won’t make money over any reasonable time frame, if ever.
The AI data-center boom is already starting to fall apart…
As the Financial Times reported on April 17:
Delays to new US data centres threaten to slow the rollout of AI by the world’s biggest tech companies, with almost 40 per cent of projects due this year at risk of falling behind schedule.
Major projects for Microsoft, OpenAI and other tech groups are likely to miss completion dates by more than three months, according to data shared with the [Financial Times] by SynMax, a satellite and AI analytics group.
Three months doesn’t sound like a big deal. But I doubt folks are admitting how far behind they really are. SynMax tracks construction progress through satellite imagery. It estimates that more than 60% of projects scheduled for completion next year haven’t even begun construction yet. For example, it’s seeing limited progress on Oracle-, OpenAI-, and SB Energy-related projects in Texas. Yet all three companies claim to be on schedule.
The Financial Times cited “more than a dozen industry executives” complaining of “permitting hurdles and chronic shortages of labour, power and equipment.”
The whole thing sounds exactly like the shale boom in North Dakota during the early 2010s, where oil-rig workers made six-figure salaries, fast-food places had trouble finding workers at $15 an hour, and Walmart paid nearly 2.5 times the minimum wage.
Data-center construction workers in Texas are moving from one OpenAI project to another in search of higher paychecks. That’s right… OpenAI is competing with itself for construction workers.
Wes Cummins, the CEO of Applied Digital (APLD), which builds and operates data centers, told the Financial Times:
We’re going to see a number of blow-ups and delays this year. My focus is on making sure it’s not us.
Many of the new data centers are gigawatt-scale projects…
That means they’re so big they’ll require 1 gigawatt of electricity – enough to power more than 700,000 American homes. It’s equal to 1.3 million horsepower, or the combined output of 2,000 Corvette Z06s. It’s like dropping a small city on 500 to 800 acres of land.
I suspect many permitting delays are due to local opposition. The same folks who don’t want a power plant in their backyards also don’t want data centers there. But power is the ultimate data-center bottleneck.
There isn’t enough power capacity for all the data centers planned and under construction. And even if you could build new power plants quickly enough, it’s a seven-year wait to connect new plants to the transmission grid.
That’s why hyperscalers are increasingly planning to build their own power plants. The overwhelming choice is natural gas turbines, but the big turbine builders have multiyear backlogs.
So data-center builders are getting creative. They’re using turbines originally designed for airplanes and warships, mobile gas generators strapped to semitrucks, and refurbished turbines from industrial plants.
I thought the AI boom would be all about technology…
When I started researching AI last fall, I figured I’d wind up learning about cool tech companies doing amazing things…
There are buildings going up all over the country, filled with the latest, most powerful graphics processing units, running software that does the unimaginable.
But it turns out, all those buildings are in desperate need of construction workers and electricity, including backup power from diesel generators.
So instead of searching for the latest tech company, I’ve been hunting for smokestacks: companies that have been producing oil and gas, refined petroleum products, and chemicals – in some cases for more than 100 years.
I’m still bullish on AI…
The five hyperscalers I mentioned earlier all have cash-gushing businesses with big competitive advantages and high returns on capital without massive amounts of investment. And they’re all betting big on the AI boom.
I believe this massive AI investment will yield incredible results – for consumers and professionals. Just like the Internet let a bunch of us make our living from anywhere we like and buy everything from fresh produce to custom-made suits, AI will change our day-to-day lives.
But I also have a feeling that hyperscalers will watch their balance sheets, cash flows, and hopes of an AI financial miracle deteriorate… and that the companies that make up 40% of the S&P 500 today will be replaced, perhaps with companies that mine copper, make diesel fuel, or some other essential product that can’t be replaced by intelligent software code.
Maybe I’m premature in my worries (wouldn’t be the first time!). Of the five hyperscalers I listed above, only Oracle is generating negative free cash flow today. It burned $25 billion of cash over the past 12 months. And it continues to spend more capital on data centers than it generates in operating cash flows. In other words, it’s burning cash, not earning it.
In a recent interview for the Stansberry Investor Hour podcast (keep an eye on investorhour.com for the full episode), we spoke with veteran fund manager George Noble. George was once legendary investor Peter Lynch’s assistant. He also oversaw the Fidelity Overseas Fund when it was the No. 1 fund in the country. So he knows what he’s talking about. And he’s no stranger to controversial opinions…
George spent a good part of our talk explaining why Tesla (TSLA) is worth roughly $25 to $54 per share, well below the recent price of around $395 per share. As we were wrapping up our talk, he also said he believes Oracle will go bankrupt.
The overall tenor of our conversation was that there’s a reckoning ahead for folks who are paying way too much for companies making promises they won’t be able to keep.
Two financial legends predict a paradigm shift will reset the market, cause Magnificent Seven stocks to plummet, and define the true winners of the next AI era. Fifty-year Wall Street legend Marc Chaikin and Silicon Valley insider Jeff Brown recently sat down together to share how you can access the names of SIX companies that could get left behind in the next era of AI. Click here for more details.
A critical flaw in the AI industry could soon wipe out $33 trillion from the U.S. stock market and cause a potential crash 62 times worse than the Great Depression – if it isn’t fixed fast. One small group of companies holds the answer… a breakthrough technology backed by Sam Altman, Elon Musk, Jensen Huang, the White House, and more. Click here to see how you could invest in the tech saving America from a $33 trillion crisis.
New 52-week highs (as of 4/30/26): ABB (ABBNY), Atlas Energy Solutions (AESI), Advanced Micro Devices (AMD), Amazon (AMZN), Alpha Architect 1-3 Month Box Fund (BOXX), Ciena (CIEN), Cisco Systems (CSCO), Deluxe (DLX), DXP Enterprises (DXPE), Emcor (EME), iShares MSCI Emerging Markets ex China Fund (EMXC), EnerSys (ENS), iShares MSCI South Korea Fund (EWY), Flex LNG (FLNG), Cambria Foreign Shareholder Yield Fund (FYLD), Alphabet (GOOGL), iShares Convertible Bond Fund (ICVT), Idex (IEX), KraneShares Bosera MSCI China A 50 Connect Index Fund (KBA), KraneShares Global Humanoid and Embodied Intelligence Index Fund (KOID), Keyence (KYCCF), Lumentum (LITE), Altria (MO), Nucor (NUE), Plains All American Pipeline (PAA), Pembina Pipeline (PBA), Invesco WilderHill Clean Energy Fund (PBW), Invesco High Yield Equity Dividend Achievers Fund (PEY), Invesco Oil & Gas Services Fund (PXJ), Ryder System (R), USCF SummerHaven Dynamic Commodity Strategy No K-1 Fund (SDCI), U.S. Global Sea to Sky Cargo Fund (SEA), State Street SPDR Portfolio S&P 500 Value Fund (SPYV), Tenaris (TS), Viper Energy (VNOM), and State Street SPDR S&P Semiconductor Fund (XSD).
In today’s mailbag, a reader shares his take on Microsoft’s spending plans, which we mentioned in yesterday’s Digest… Do you have a comment or question? As always, e-mail us at feedback@stansberryresearch.com.
“Microsoft will spend $190 billion on capital spending. Their old run-rate was around $25-28 billion, so we can estimate their capex on data centers is around $165B. The buildings are depreciated over 30 years and the servers [and equipment] over no more than six years according to my research [Editor’s note: Yes, generally true] – 4 or 5 years is more typical – but I will use 6 years…
“If we’re generous and say that half the data center capex is on complex buildings, infrastructure, HVAC and power generation, then that’s $80 billion, in round figures. That’s $2.7B in annual depreciation… [But] then they have operation and maintenance costs which will run in the low percentages, plus enormous power costs… MSFT’s annual depreciation in the prior fiscal year was $34B… This is a big nut to overcome… I’m not sure this will work out well at all.” – Subscriber Mark P.
Good investing,
Dan Ferris Medford, Oregon May 1, 2026
Stansberry Research Top 10 Open Recommendations
Top 10 highest-returning open stock positions across all Stansberry Research portfolios. Returns represent the total return from the initial recommendation.InvestmentBuy DateReturnPublicationMSFT Microsoft11/11/101,361.0%Retirement MillionaireMSFT Microsoft02/10/121,316.3%Stansberry’s Investment AdvisoryGOOGL Alphabet12/15/16847.9%Retirement MillionaireCIEN Ciena10/20/22840.1%Stansberry Innovations ReportADP Automatic Data Processing10/09/08819.2%Extreme ValueBRK.B Berkshire Hathaway04/01/09766.4%Retirement MillionaireALS-T Altius Minerals03/26/09643.1%Extreme ValueWRB W.R. Berkley03/15/12621.0%Stansberry’s Investment AdvisorySII Sprott01/11/18603.9%Extreme ValueLITE Lumentum04/15/21576.7%Stansberry Innovations Report
Please note: Securities appearing in the Top 10 are not necessarily recommended buys at current prices. The list reflects the best-performing positions currently in the model portfolio of any Stansberry Research publication. The buy date reflects when the editor recommended the investment in the listed publication, and the return shows its performance since that date. To learn if a security is still a recommended buy today, you must be a subscriber to that publication and refer to the most recent portfolio.
Top 10 Totals3Extreme ValueFerris3Retirement MillionaireDoc2Stansberry Innovations ReportEngel2Stansberry’s Investment AdvisoryPorter
Top 5 Crypto Capital Open Recommendations
Top 5 highest-returning open positions in the Crypto Capital model portfolioInvestmentBuy DateReturnPublicationBTC/USD Bitcoin11/27/181,929.8%Crypto CapitalWSTETH/USD Wrapped Staked Ethereum12/07/181,839.6%Crypto CapitalONE/USD Harmony12/16/191,008.8%Crypto CapitalPOL/USD Polygon02/26/21642.1%Crypto CapitalQRL/USD Quantum Resistant Ledger01/19/21479.7%Crypto Capital
Please note: Securities appearing in the Top 5 are not necessarily recommended buys at current prices. The list reflects the best-performing positions currently in the Crypto Capital model portfolio. The buy date reflects when the recommendation was made, and the return shows its performance since that date. To learn if it’s still a recommended buy today, you must be a subscriber and refer to the most recent portfolio.
^ These gains occurred with a partial position in the respective stocks. * Editor Dave Lashmet closed the first leg of this Nvidia position in November 2016 for a gain of about 108%. Then, he closed the second leg in July 2020 for a 777% return. And finally, in May 2022, he booked a 1,466% return on the final leg. Subscribers who followed his advice on Nvidia could’ve recorded a total weighted average gain of more than 600%.
Stansberry Research Crypto Hall of Fame
Top 5 highest-returning closed positions in the Crypto Capital model portfolioInvestmentDurationGainAnalystBand Protocol (BAND)0.31 years1,169%Crypto CapitalTerra (LUNA)0.41 years1,166%Crypto CapitalPolymesh (POLYX)3.84 years1,157%Crypto CapitalFrontier (FRONT)0.09 years979%Crypto CapitalBinance Coin (BNB)1.78 years963%Crypto Capital
You have received this e-mail as part of your subscription to Stansberry Digest. If you no longer want to receive e-mails from Stansberry Digestclick here.
Published by Stansberry Research.
You’re receiving this e-mail at pahovis@aol.com. Stansberry Research welcomes comments or suggestions at feedback@stansberryresearch.com. This address is for feedback only. For questions about your account or to speak with customer service, call 888-261-2693 (U.S.) or 443-839-0986 (international) Monday-Friday, 9 a.m.-5 p.m. Eastern time. Or e-mail info@stansberryresearch.com. Please note: The law prohibits us from giving personalized financial advice.
Any brokers mentioned constitute a partial list of available brokers and is for your information only. Stansberry Research does not recommend or endorse any brokers, dealers, or investment advisors.
Stansberry Research forbids its writers from having a financial interest in any security they recommend to our subscribers. All employees of Stansberry Research (and affiliated companies) must wait 24 hours after an investment recommendation is published online – or 72 hours after a direct mail publication is sent – before acting on that recommendation.
This work is based on SEC filings, current events, interviews, corporate press releases, and what we’ve learned as financial journalists. It may contain errors, and you shouldn’t make any investment decision based solely on what you read here. It’s your money and your responsibility.
















 News for you, Peter
 Today’s game
 Trending now1.