The Stock-Picking AI That Could Triple Your Money This Year
Early users could have already tripled their money every single year this AI has been live, based on the average winning trade spotted – WITHOUT having to check the news, WITHOUT watching the Fed, and WITHOUT all the stress most traders have to deal with. For now, you can try this AI yourself, completely free of charge – no email, no credit card.
A self-taught trader from rural Georgia figured out why… and he’s been flipping the script, using this hedge fund secret to make 1,140% overnight… 1,131% in 48 hours… even 325% on Tesla in a single day.
Stephen Prior, Publisher Monument Traders Alliance
Monument Traders Alliance, LLC
You are receiving this email because you subscribed to Trade of the Day. Trade of the Day is published by Monument Traders Alliance, LLC.
To stop receiving special invitations and offers from Trade of the Day, please click here. Please note: This will not impact the fulfillment of your subscription in any way.
To cancel by mail or for any other subscription issues, write us at: Trade of the Day | 14 West Mount Vernon Place |Baltimore, MD 21201 North America: 800.507.1399 | International: +1.443.353.4977 Website | Privacy Policy Keep the emails you value from falling into your spam folder. Whitelist Trade of the Day.
Please do not reply to this email as it goes to an unmonitored inbox.
Nothing published by Monument Traders Alliance should be considered personalized investment advice. Although our employees may answer your general customer service questions, they are not licensed under securities laws to address your particular investment situation. No communication by our employees to you should be deemed personalized investment advice. We allow the editors of our publications to recommend securities that they own themselves. However, our policy prohibits editors from exiting a personal trade while the recommendation to subscribers is open. In no circumstance may an editor sell a security before subscribers have a fair opportunity to exit. The length of time an editor must wait after subscribers have been advised to exit a play depends on the type of publication. All other employees and agents must wait 24 hours after publication before trading on a recommendation.
Any investments recommended by Monument Traders Alliance should be made only after consulting with your investment advisor and only after reviewing the prospectus or financial statements of the company.
Protected by copyright laws of the United States and international treaties. The information found on this website may only be used pursuant to the membership or subscription agreement and any reproduction, copying or redistribution (electronic or otherwise, including on the world wide web), in whole or in part, is strictly prohibited without the express written permission of Monument Traders Alliance, LLC, 14 West Mount Vernon Place, Baltimore, MD 21201.
Thanks for signing up for MarketBeat Daily Ratings—we’re excited to have you on board.
Every weekday, you’ll get a curated summary of new “Buy” and “Sell” ratings from Wall Street’s top-rated analysts, the latest stock news, and bonus investing content—all delivered straight to your inbox.
You’re just two quick steps away from completing your sign-up:
1. Make sure our emails go to your inbox
Gmail users: Mobile: Tap the three dots (…) in the top right and select Move to Inbox or Move to Primary Desktop: Click the folder icon at the top and select Move to Inbox or Primary
Apple Mail users: Tap our email address at the top (next to From: on mobile), then select Add to VIP
Other providers: Reply to this message and add newsletters@analystratings.net to your contacts
2. Confirm your subscription
Click this link to confirm your subscription. This verifies your account and ensures you receive your newsletters without interruption instead of getting stuck in your spam filter.
After you confirm, feel free to download our popular free report, “7 Stocks to Buy and Hold Forever” with this link.
Thanks again for subscribing—we look forward to being part of your investing journey.
Matthew Paulson Founder and CEO, MarketBeat.
P.S. If you didn’t mean to subscribe, no problem—you can unsubscribe here.
This Month’s Exclusive Story
Apple’s Hinge Cringe: Foldable Flop or Strategic Stop?
Authored by Jeffrey Neal Johnson. Article Posted: 4/9/2026.
Wall Street is watching Apple (NASDAQ: AAPL) closely as the tech giant faces mixed signals. On April 7, 2026, Apple’s share pricefell as much as 5% intraday to roughly $246, wiping a substantial amount of value off the company’s market cap, which now sits at about $3.8 trillion.
While the broader market attempts to find its footing after a recent correction, Apple is confronting its own headwinds. The main driver of the sell-off: reports that Apple’s first foldable iPhone has run into engineering problems. For investors, that raises a key question — is Apple losing its edge in hardware innovation, or is it intentionally shifting focus to higher-margin businesses?
A Crease in the Plan
Reports say the foldable iPhone failed internal durability tests. Specifically, hinges reportedly aren’t meeting Apple’s standards and the flexible displays are developing visible creases too quickly. Those issues have pushed mass production back to at least 2027, a serious setback for investors who had hoped a foldable would spark a hardware supercycle and prompt large-scale upgrades.
Louis Navellier: Don’t buy OR sell another AI stock…
Until you’ve heard this urgent AI warning from the man who called Nvidia before its 44,000% rise… According to Louis, a massive reset is coming in an obscure corner of the AI market. This $100 trillion disruption could send some of the world’s biggest AI stocks to zero… and one off-the-radar stock soaring… starting now.Click here for details and Louis’ new pick — free.
Key Points
The consistent growth of the services segment provides Apple with a robust financial foundation while maintaining high profit margins for shareholders.
New demand for high-performance computing hardware driven by artificial intelligence developers highlights Apple’s ability to adapt to emerging technology.
Strategic expansion into budget-friendly hardware segments allows the ecosystem to capture a wider range of customers and support long term growth objectives.
Meanwhile, rivals are ahead in the foldable space. Samsung (OTCMKTS: SSNLF) and Motorola (NYSE: MSI) currently dominate the market, with Samsung holding more than 50% share. By the time Apple ships its product, it may have ceded much of the high-end foldable market.
The delay leaves Apple leaning more heavily on the iPhone 17, which has posted strong sales but lacks the “wow” factor of a foldable. For a stock trading at a price-to-earnings ratio near 32X, any hint that hardware innovation is slowing can trigger quick downside.
$30 Billion in Services Revenue Provides a Cushion
Even amid iPhone concerns, Apple’s Services segment is acting as a financial buffer. Services — including iCloud and Apple Music subscriptions and App Store fees — generated a record $30 billion in revenue in the first quarter of 2026. Those offerings carry profit margins north of 70%, far higher than hardware, giving the company a steady, high-margin cash stream that helps set a valuation floor when device sales wobble.
Another bright spot is a surge in demand for the Mac Mini, driven by OpenClaw, a new platform for autonomous artificial intelligence (AI)agents. Developers building AI systems to run locally prefer the Mac Mini with the M4 Pro because its unified memory architecture — where CPU and GPU share the same memory pool — boosts performance for local AI workloads.
Demand is so strong that some Mac Mini configurations are facing shipping delays of 16 to 18 weeks. In short, while one hardware opportunity may be slipping, another is opening in AI-ready hardware.
Using Budget Laptops to Fuel Future Growth
Apple is also pursuing growth by targeting buyers who previously found its products out of reach. The MacBook Neo, starting at $599, is a strategic push into education and budget-conscious segments to expand Apple’s ecosystem.
That strategy is intentionally top-of-funnel: a lower-cost MacBook can lead customers to subscribe to iCloud, Apple TV+ and other services, increasing lifetime value even if they aren’t immediately buying $1,200 iPhones. This funnel approach supports broader user growth and helps sustain Apple’s sizable revenue base, which currently sits around $416.16 billion annually.
Patent Battles and Regulatory Speed Bumps
China remains a meaningful risk. A Chinese court recently ruled against Apple in an AI patent dispute with local company Xiao‑I, and regulatory pressure has forced Apple to pause Apple Intelligence features in the region. Those issues have weighed on the stock, contributing to its roughly 5% decline so far this year.
Still, Apple’s financial position remains robust. The company generated $54 billion in operating cash flow in the last quarter and maintains a $100 billion share buyback program announced in Q2 2025. Most analysts on Wall Street continue to assign a Moderate Buy rating, with an average price target near $297.58 — implying more than 15% upside from current levels for many experts.
Why One Product Delay Doesn’t Break Apple’s Core
The near-term outlook is neutral to bearish. The foldable iPhone delay is a legitimate concern for those looking for the next big hardware catalyst, and legal and regulatory issues in China add risk. Yet Apple’s record Services revenue and growing demand for AI-capable hardware like the Mac Mini indicate the company is evolving its business mix.
Investors should watch Apple’s next earnings report on May 7, 2026, for updates on AI product supply chains and progress resolving regulatory challenges in China. For long-term investors, Apple’s strong cash generation and moves into budget devices provide reasons for cautious optimism. While hinge problems are driving a short-term pullback, Apple’s diversified strategy may prove more resilient than a single product delay.
Thank you for subscribing to MarketBeat!
We empower everyday investors to make better financial decisions by offering real-time financial information and objective market research.
If you need help with your newsletter, don’t hesitate to contact MarketBeat’s U.S. based support team at contact@marketbeat.com.
For income investors, few things are as rewarding as receiving quarterly dividend payouts. Almost as pleasing is learning that the stocks in a yield-focused portfolio are increasing those payouts.
For shareholders of three high-profile stocks, that is precisely the case — one even announced a substantial 33% dividend increase.
Louis Navellier: Don’t buy OR sell another AI stock…
Until you’ve heard this urgent AI warning from the man who called Nvidia before its 44,000% rise… According to Louis, a massive reset is coming in an obscure corner of the AI market. This $100 trillion disruption could send some of the world’s biggest AI stocks to zero… and one off-the-radar stock soaring… starting now.Click here for details and Louis’ new pick — free.
While dividend boosts aren’t uncommon, stock price performance and dividend-yield shifts can tell very different stories. The following semiconductor lynchpin, Chinese streaming behemoth, and premium home goods retailer each tell a different tale.
Micron Boosts Its Dividend Following 300% Surge
After putting up blistering gains over the past year, Micron Technology (NASDAQ: MU) is returning to dividend increases. Shares are up about 25% year-to-date (YTD) and have gained more than 300% over the past 12 months, driven by a shortage of high-bandwidth memory chips that are critical to AI’s growth trajectory.
That demand has been an incredible tailwind. In its Q2 2026 earnings report, Micron reported revenue of $23.9 billion, surpassing estimates by almost $4 billion. The company’s guidance for the next quarter was even more impressive: at the midpoint, Micron expects revenue of $33.5 billion, which would exceed analyst expectations by more than $9 billion.
Alongside the firm’s strong performance, Micron announced a 30% increase to its quarterly dividend. The company plans to pay its next dividend on April 15 to shareholders of record on March 30.
On the surface, Micron’s indicated dividend yield—less than 0.2%—is modest. But it is notable because this is the first time in nearly four years the company has raised its dividend; the last increase was a 15% bump in mid-2022.
Micron’s return to dividend increases—and the much larger size of its latest boost—underscores how well the company has been performing. It has rewarded shareholders with roughly a 450% gain since last April’s tariff-driven sell-off.
Williams Sonoma Boosts Dividend 15% Despite Weakening Housing Outlook
Shares of Williams Sonoma (NYSE: WSM) — the owner and operator of Williams Sonoma, Pottery Barn, and West Elm — rose more than 17% YTD through early February before tumbling roughly 21% from its 2026 high.
With housing demand cooling amid still-elevated interest rates and home prices near record levels, Williams Sonoma has been pressured. The company relies on housing transactions as a key demand driver for its premium products; consumers often buy large home items alongside home purchases. Over the past several months, investor sentiment has shifted as WSM executives moderated their outlook for a 2026 housing market recovery.
In November, during the company’s Q3 2025 earnings call, CEO Laura Alber said she was “very optimistic about housing next year.” By March, on the company’s Q4 earnings call, Alber noted, “We are not building into our assumptions a meaningful housing recovery.” This shift is partly attributable to the rapid rise in oil prices driven by the conflict in Iran and the subsequent economic effects domestically and globally (Williams Sonoma operates stores in the United States, Canada, Australia, and the United Kingdom, and ships to more than 60 countries).
Higher oil prices can push up inflation, making it less likely the Federal Reserve will cut rates soon. That, in turn, keeps mortgage rates elevated, which can depress housing turnover and demand for Williams Sonoma’s products.
Still, shares are up nearly 11% over the past year, and the company continues to return capital to shareholders. Williams Sonoma recently announced a 15% dividend increase, raising its quarterly payout to $0.76 per share. The firm expects to pay the next dividend on May 22 to shareholders of record as of April 17. The stock’s indicated dividend yield now sits at about 1.5%, its highest level in nearly a year.
Tencent: Profits and Dividends Rise as Shares Fall
However, investors have pummeled the stock in 2026, sending it down more than 45% YTD. Much of the sell-off reflects rising competition: Bytedance, owner of Douyin (the Chinese version of TikTok), has rapidly expanded its Soda Music platform. Soda’s MAUs reached 120 million in September 2025, and reports indicate that figure grew to 140 million by March 2026.
Meanwhile, Tencent saw a 5% decrease in total MAUs from Q4 2024 to Q4 2025. Despite that, the company’s revenue rose about 16% year-over-year, and total operating profit increased a remarkable 53.4% year-over-year.
That growth came even as total MAUs declined, aided by a 5.3% year-over-year increase in paying users, which helped offset some user losses. But because TME’s total MAUs are shrinking, its ceiling for future paid-user growth is lower. Tencent now trades at a forward price-to-earnings (P/E) ratio of around 10x, tied for its lowest level in the past five years.
A silver lining for investors is that TME’s indicated dividend yield is near its highest level ever, roughly 2.5%, helped by the 33% dividend increase the company recently announced. The annual dividend rises to $0.24 per American Depositary Share, and TME plans to pay it “on or around” April 23 to shareholders of record on April 2.
MU’s Forward P/E Plummets as the Stock Takes Off
MU, WSM, and TME are three stocks with very different near-term performances, but all are increasing capital returned to shareholders.
Micron is among the most interesting names to watch. Even after an exceptional run, the stock’s forward P/E ratio is only about 16.87, as earnings expectations have climbed faster than the share price.
Whether the stock will face a correction if the memory shortage eases remains a key risk. For now, analysts see nearly 35% potential upsideover the next 12 months.
This Month’s Bonus Story
3 Dividend Stocks Defying the Market Downturn Amid the Iran Conflict
Reported by Nathan Reiff. First Published: 4/3/2026.
Key Points
While the S&P has dropped modestly since the start of the Iran war, some individual standouts have risen over the last month or so.
Crescent Energy and Viper Energy are two lesser-known stocks in the energy sector with potential to stand out thanks to their domestic operations.
Unum Group is unrelated to the conflict as a disability and life insurer, but it still draws interest for its dividend strength and growth potential.
The S&P 500 has fallen nearly 5% over the past month—roughly since the U.S.-Iran conflict began—yet some stocks have bucked the trend. Certain industries — airlines, for example — have been hit hard by the prospect of service disruptions and higher energy costs. Still, a number of companies — including dividend-paying names that offer passive income on top of price appreciation — may have room to run despite the turbulence.
Investors seeking momentum with income might consider Crescent Energy Co. (NYSE: CRGY), Viper Energy Partners LP (NASDAQ: VNOM), and Unum Group (NYSE: UNM).
Crescent Energy’s Domestic Position Wins Analyst Support
Louis Navellier: Don’t buy OR sell another AI stock…
Until you’ve heard this urgent AI warning from the man who called Nvidia before its 44,000% rise… According to Louis, a massive reset is coming in an obscure corner of the AI market. This $100 trillion disruption could send some of the world’s biggest AI stocks to zero… and one off-the-radar stock soaring… starting now.Click here for details and Louis’ new pick — free.
Higher oil prices can benefit some energy companies — the benchmark Energy Select Sector SPDR Fund (NYSEARCA: XLE), which tracks a large portion of the sector, is up more than 3% in the past month — but the Iran conflict doesn’t guarantee any single firm will prosper. Crescent Energy, a Permian Basin-focused exploration company, has emerged as a Wall Street favorite. Since the start of the conflict, it has received a ratings upgrade from JPMorgan Chase, higher price targets from Wells Fargo and Piper Sandler, and additional Buy-equivalent reiterations from other firms.
Analysts point to Crescent’s domestic shale operations, which could prove essential if oil shipments from the Middle East decline. Its fiscal stability and favorable geopolitical positioning help it stand out during a turbulent period.
Those potential gains from higher oil prices would add to Crescent’s recent operational progress. In the latest quarter, the company boosted production to about 268,000 BOE/d and generated roughly $239 million of levered free cash flow. With annual cash flow from its new royalties operation expected to be at least $160 million, Crescent sits at a strategic inflection point that could help it grow into a larger domestic player. Its dividend yield of about 2.5% is an added benefit that should be easier to sustain as cash flow expands.
Viper’s Royalty Focus Sets it Apart in the Energy Sector
Viper Energy is a royalties company: it does not directly produce hydrocarbons but holds royalty and mineral fee interests. Like Crescent, Viper concentrates on the Permian Basin, giving it domestic exposure that can be advantageous when international supplies are uncertain.
Analysts have adjusted their views on Viper in recent weeks, including several raised price targets, bringing the company’s consensus price target to $52.60, roughly 15% above current trading levels. Viper’s royalty model limits direct operational risk and, while it may cap some upside tied to production, it can provide steadier returns amid volatile production costs and commodity prices.
Viper’s activity over the last year has positioned it well for 2026: in 2025, the company acquiredabout $8 billion in minerals while also improving its balance sheet. The result is a dividend yield that has risen to 3.3%, alongside a significant new share repurchase program.
Big Growth Possible for an Insurer Separate From the Iran War
The sole non-energy name on this list is Unum Group, a life and disability insurer that has been affected by the broader market pullback tied to the Iran conflict. Although Unum isn’t directly linked to the geopolitical event, its relative weakness in the financials sell-off can create an attractive entry point for investors.
Management expects earnings per share (EPS) and core operations to grow about 8%–12% and 4%–7% year-over-year, respectively, in 2026. Combined with steady profitability and shareholder returns — including a dividend yield of 2.49% and nearly two decades of consecutive dividend increases — it’s clear why analysts like the company.
Unum also has upside potential near 30%, making it appealing for investors seeking growth that isn’t directly tied to the current geopolitical backdrop.
This email communication is a paid advertisement provided by StockEarnings, a third-party advertiser of MarketBeat. Why did I receive this email content?.
If you need help with your account, feel free to email our U.S. based support team at contact@marketbeat.com.
A Message from Your Corporate, Life Science, Blockchain & Big Science Community
Dear Valued Member,
Thank you for your continued commitment to our shared mission. As we reflect on another year of discovery and collaboration, we are proud to share exciting updates on the programs we have built — for you, and with you.
STEM & Technical Literacy for Professionals and Families
We know that working at the frontier of life science, blockchain, and big science demands constant learning and adaptability. That’s why our growing STEM literacy program offers hands-on workshops covering biotechnology, laboratory fundamentals, distributed ledger systems, data science, and the practical technical skills that define the industries we work in — and the world we are helping to build. Whether you are an active professional, a researcher, an entrepreneur, or a family member, these resources are designed with your real-world experience in mind.
Wellness & Healthy Living
From nutrition and fitness to mental resilience and preventive care, our health and wellness series provides evidence-based guidance tailored for the demands of high-performance professional life. The same rigor we apply to science, we apply to living well. Small daily habits can make a lasting difference — for you and your whole household.
Personal & Financial Safety
Protecting your future means more than professional achievement. Our safety workshops cover personal and home security, cybersecurity awareness, and financial literacy — including asset management, blockchain-based financial tools, investment fundamentals, and long-term wealth planning built around the unique needs of our community.
Community & Career
Connection matters deeply in industries built on collaboration and trust. Through our networking events, peer circles, and cross-disciplinary forums, members find new friendships, research partnerships, and professional opportunities that cross borders and disciplines. Our career development support — including mentorship, skills coaching, and institutional partnerships — helps professionals at every stage grow with confidence and purpose.
Together, we are building healthier, stronger, and more innovative communities — one breakthrough at a time.
With deep gratitude and continued enthusiasm,
Corporate, Life Science, Blockchain & Big Science Community Network— Sustained by Members Like You
Copyright (C) 2026 A l i e n P u p p y H a w a i i – F o r u m. All rights reserved. You are receiving this email because you opted in via our website.
Our mailing address is: A l i e n P u p p y H a w a i i – F o r u m Strother Alien Puppy Hawaii St Monroe, NE 68647 USA
That’s how often I’ve received the signal to go “all-in” on gold.
The first time was back in the 2000s…
The dot-com mania was nearing its peak, money was flooding into any and all tech stocks, and equity valuations were trading at nosebleed levels.
I was in my mid-20’s. Just starting my first business.
And although I didn’t have much capital to spare, I scrounged together as much money as I could to load up not on tech stocks… but on gold coins.
At the time, gold was despised by Wall Street.
Goldman Sachs called it “a 19th-century asset.”
One of Merrill Lynch’s top investment analysts said that it was only for “grandmothers and conspiracy theorists.”
And two of America’s leading economists at the time called it a “barren asset.”
Yet, I chose to go in at under $300 an ounce.
My second signal came in 2008 when, amidst the chaos of the financial crisis, gold prices dropped briefly below $800 an ounce… and I once again went “all-in” on gold.
And a little over a year ago, I did it again…
I moved roughly 50% of my liquid net worth into gold and Bitcoin:
Three “all-in” decisions… Each of which seemed crazy to most at the time.
But for me… it was the most obvious move to make.
Why?
It’s all thanks to an incredible secret I learned from famed economist Kurt Richebächer – the last of the true Austrian economists.
What he taught me has been incredibly accurate at predicting the price of gold over the years.
It’s helped me make an absolute killing each of the three times I went “all-in.”
And right now, it is again predicting a shocking new price for gold in the near future.
Hollywood’s New Cash King: Paramount’s $24B Power Play
By Jeffrey Neal Johnson. Originally Published: 4/9/2026.
Key Points
The massive infusion of foreign equity capital creates a robust financial foundation that significantly enhances the long-term stability of the new company.
Combining the extensive libraries of both studios produces a world class content engine capable of outperforming major global technology competitors.
This merger establishes an elite streaming powerhouse with the necessary scale and operational efficiency to capture a larger share of the global market.
A multi-billion-dollar wave of Gulf sovereign wealth capital is poised to reshape the American media landscape. Two of Hollywood’s most iconic names, Paramount (NASDAQ: PSKY) and Warner Bros. (NASDAQ: WBD), sit at the center of a monumental shift backed by an unprecedented $24 billion equity commitment.
That financing is more than a headline; it marks a meaningful change in how media empires are built and funded. The deal creates a new heavyweight contender in the battle for streaming dominance and reshapes the landscape investors must navigate.
The Strategic Power of a Clean Balance Sheet
The primary obstacle to large-scale media mergers has long been the massive debt needed to finance them. The proposed acquisition of Warner Bros. Discovery by Paramount Skydance sidesteps that issue. The company has secured firm commitments for roughly $24 billion in equity, a fundamentally different and more stable form of capital that materially improves the transaction’s outlook.
Since 2009, the Dividend Machine has posted a total return of 7,056.47% – turning a $10,000 stake into more than $700,000 while the broader market struggled through multiple downturns.
With a 93% win rate since launch, this dividend-focused strategy has kept investors cashing steady checks through every crash. Bill Spetrino has released a free report outlining how to position for income no matter what the market does next.Claim your free report and see how the Dividend Machine works
Unlike deals financed with large loans, this equity infusion strengthens the combined company’s balance sheet from day one. It avoids saddling the new entity with heavy interest payments that can stifle growth and innovation — a persistent problem in past media consolidations.
That financial flexibility is a significant competitive advantage. Future cash flow can be devoted to what matters in the streaming wars: blockbuster content, new technology, and aggressive global marketing, rather than debt service.
The strategic de-risking of the deal has already registered with investors. On April 7, 2026, Paramount shares rose 10% to close at $10.90, a clear market signal that the financing has increased confidence in the merger’s likelihood of success by removing a major financial risk.
Building a Content Kingdom to Conquer Streaming
The strategic logic behind this roughly $110 billion merger is scale: to create a media company large enough to compete in the modern streaming era. Today’s entertainment landscape is dominated by deep-pocketed tech incumbents like Netflix (NASDAQ: NFLX) and Disney (NYSE: DIS). To go head-to-head with those rivals, a vast content library and globally recognized intellectual property are essential.
This transaction pairs Paramount’s blockbuster production capabilities — films such as “Top Gun” and “Mission: Impossible” — with Warner Bros. Discovery’s sprawling, iconic library. That portfolio spans HBO prestige television, the DC Comics universe, and a deep catalog of unscripted content from Discovery.
Combined, the companies create a content arsenal few can match. The efficiencies extend beyond content: consolidating technology platforms and marketing operations can drive meaningful cost savings and improve margins. This operational efficiency, together with a world-class content engine, builds a compelling competitive moat.
With an expected combined market capitalization approaching $80 billion, the new company would have the financial scale to invest heavily and consistently in original programming and cutting-edge technology — the core levers for attracting and retaining subscribers worldwide.
The Market’s Mixed Signals: Finding the Opportunity
The market reaction has produced a nuanced landscape with potential opportunities. Paramount rallied on the financing news, while Warner Bros. shares remained relatively stable around $27.
That suggests investors are taking a wait-and-see stance on Warner Bros. ahead of the April 23, 2026 shareholder vote and regulatory hurdles. The divergence could create a value gap, offering a chance to buy Warner Bros. before any acquisition premium is fully reflected in its share price.
Analyst ratings add another layer. Despite the financing catalyst, the consensus rating for Paramount remains a Strong Sell, although the average analyst price target of $12.85 implies roughly 17% upside from current levels.
Such disconnects can occur when Wall Street models lag transformative news. Many analysts may wait for the deal to close before fully pricing in the long-term benefits of a combined company with a reinforced balance sheet, creating an opening for forward-looking investors. While recent insider sales at Warner Bros. have drawn attention, such activity is common in pre-merger periods as executives manage their holdings and is not necessarily a bearish signal on the deal’s fundamentals.
A New Hollywood Powerhouse Is Born
The $24 billion equity infusion is not just financing a transaction; it is underwriting the creation of a financially resilient media titan. With its capital structure shored up, a clear strategic purpose, and growing market recognition, the combined Paramount-Warner entity is positioned to disrupt the streaming landscape.
The deal’s equity-first structure offers a blueprint for how legacy media can adapt and thrive in an industry dominated by tech giants. The blend of iconic Hollywood assets and substantial global capital presents a compelling story and a company that investors should watch closely going forward.
Today’s Featured Content
5 Spin-Off Stocks That Could Reward Patient Investors in 2026
By Thomas Hughes. Originally Published: 3/26/2026.
Key Points
Spin-offs are a powerful tool that helps CEOs unleash growth and unlock value for investors.
Five planned 2026 spin-offs fit the bill and attract bullish analyst ratings.
The question investors must ask themselves is whether to buy the original, the spinco, or both.
Spin-offs are a powerful tool for companies, helping them streamline operations, focus on growth, and unlock shareholder value. The key question is whether a separation changes how investors evaluate the original company, the new company, or both as standalone investments.
FedEx on Track to Deliver Value-Building Savings
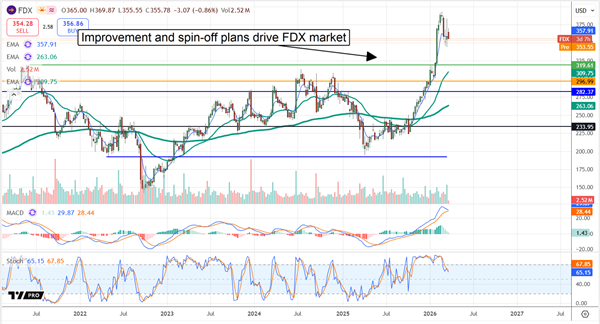
FedEx’s (NYSE: FDX) spin-off suggests both the parent and the new company could be attractive buys. The split separates the freight business from the core package-delivery operation, allowing each company to trade at freer valuations. A critical takeaway for potential investors in the freight company is that it could trade at a 50% or higher premium to the original entity. The freight business faces 2026 headwinds, including tepid demand, margin pressure, and expansion costs.
Since 2009, the Dividend Machine has posted a total return of 7,056.47% – turning a $10,000 stake into more than $700,000 while the broader market struggled through multiple downturns.
With a 93% win rate since launch, this dividend-focused strategy has kept investors cashing steady checks through every crash. Bill Spetrino has released a free report outlining how to position for income no matter what the market does next.Claim your free report and see how the Dividend Machine works
Takeaways for investors in the remaining FDX include improvements in operational quality, cash flow, and the reliability of capital returns. FedEx’s capital-return program—dividends, dividend growth, and aggressive share buybacks—remains meaningful: buybacks reduced the share count by more than 2.5% year-to-date through the end of fiscal Q3 2026. Analysts are lifting price targets ahead of the spin-off, supporting a Moderate Buy view with potential to reach new highs by mid-year.
KBR Split Enhances Focus, Unlocks Growth Avenues
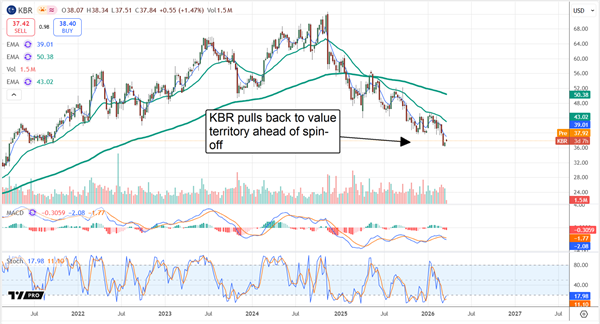
KBR’s (NYSE: KBR) split, scheduled for completion in the back half of 2026, aims to separate its Sustainable Technology Solutions business from its government-facing operations. The new company will comprise the Mission Technology Solutions group, which covers defense, security, and space applications. This move is intended to unlock value: the spinco could see a 100%–200% price gain if it trades closer to defense peers rather than the parent’s ~9x multiple. Defense specialists such as Lockheed Martin (NYSE: LMT), Northrop Grumman (NYSE: NOC), and RTX (NYSE: RTX)trade at well over 20 times earnings.
While the spinco will concentrate on defense contracts and executing its sizable backlog, the ongoing business will focus on higher-margin sustainable energy technologies. The leaner parent should benefit from faster decision-making and greater financial flexibility, enabling continued investment in growth. Analyst revisionsare mixed for 2026, but the consensus rating remains Hold and the average price target implies roughly 50% upside.
Medtronic to Spin-Off High-Growth Diabetes Unit
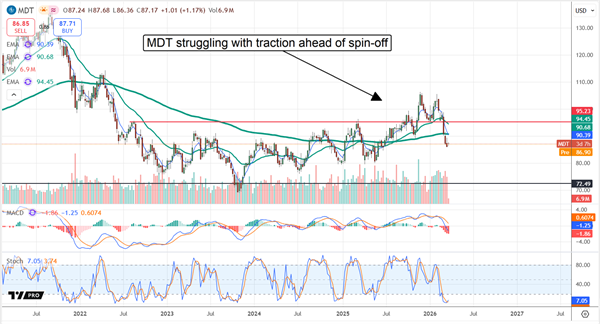
Medtronic (NYSE: MDT) plans to spin off its high-growth diabetes unit later this year—a move that may seem counterintuitive at first. The diabetes business is more consumer-oriented, while the core company is focused on hospital-based care, creating strategic and operational mismatches in a combined structure. The spin-off will create a pure-play diabetes equipment and supply company that can compete more effectively in its fast-growing market and could become a takeover candidate.
The remaining Medtronic will concentrate on higher-margin, high-growth areas such as cardiovascular devices and robotic surgery. Robotic surgery is a major growth area, led by names like Intuitive Surgical (NASDAQ: ISRG), which has sustained double-digit growth and improving operational metrics. Twenty-six analysts rate this stock a Moderate Buy. Coverage is increasing, sentiment is firm, and the consensus price target implies more than 25% upside as of late March.
Keurig Dr Pepper: Grows to Split, Unleashes Global Powerhouses
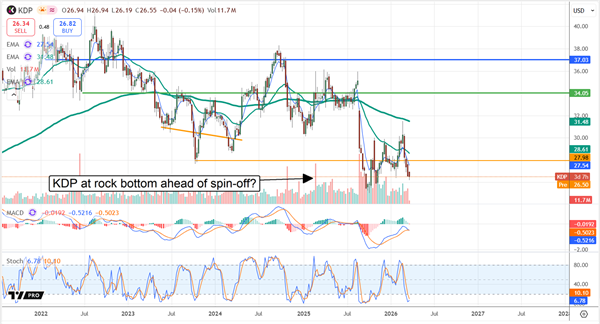
Keurig Dr Pepper (NASDAQ: KDP) has struggled for years as strengths in one segment often offset weaknesses in the other. The company plans another coffee acquisition and then to spin off the coffee business into a pure-play. That approach is expected to deliver supply-chain efficiencies and unlock growth—especially in the high-margin coffee pod market.
The ongoing business will become a soda-and-beverage pure-play, unencumbered by coffee-specific issues and with a stronger financial profile. It will be better positioned to focus on its higher-margin businesses and pursue acquisitions. The transaction is expected to be completed in April. Analysts are bullish, rating the stock a Moderate Buy and raising price targets ahead of the spin-off. The MarketBeat consensus price target implies roughly 35% upside, and the highest analyst targets add further double-digit potential.
Honeywell Splits to Enhance Focus With 2 Pureplay Businesses
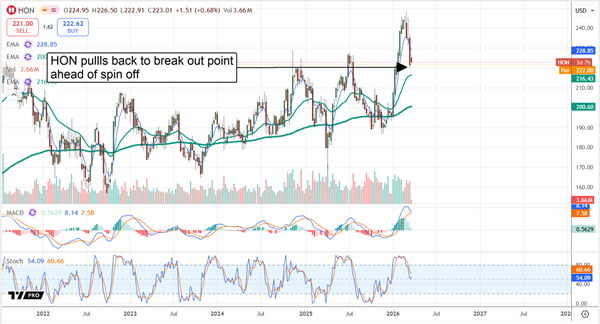
Honeywell (NASDAQ: HON) plans to separate its aerospace business into a focused pure-play unit. That aerospace company will service defense and commercial contracts, execute on a record backlog, and improve cash flow, while the original company concentrates on industrial automation. Industrial automation sits at the center of Industry 4.0—the nexus of the Internet of Things (IoT), robotics, and AI. The split should give each company a more flexible financial position and enable strategic acquisitions to sustain long-term growth.
Analyst trends suggest investors are most bullish on this name. MarketBeat data shows growing coverage, firming sentiment at Moderate Buy, and an uptrend in price targets. The consensus forecast indicated about 10% upside in late March, with sentiment and target trends skewed toward the high end and likely to remain strong through year-end.
This email communication is a paid sponsorship sent on behalf of Porter & Company, a third-party advertiser of MarketBeat. Why did I receive this email?.
If you have questions or concerns about your newsletter, please email our U.S. based support team at contact@marketbeat.com.
As you prepare for the week ahead, I wanted to bring to your attention an important matter that could significantly impact your investment success.
Upon reviewing our subscriber accounts, I noticed that your name is currently missing from our exclusive stock alert distribution list. This means that you may be missing out on valuable information and the opportunity to make well-timed investment decisions.
Our next stock alert is scheduled to be sent out tomorrow, and I want to ensure that you don’t miss out on this potentially profitable opportunity.
Joining our alert distribution list is quick and straightforward. Simply click on the link below to sign up and guarantee that you receive our future alerts:
By becoming part of our alert list, you’ll gain access to crucial insights, expert analysis, and real-time updates that can significantly influence your investment strategy.
Staying well-informed, making informed choices, and positioning yourself for financial success will become easier than ever.
Thank you for your attention, and we look forward to keeping you informed with our stock alerts!
William Bushee Vice President, MarketBeat
More Reading from MarketBeat.com
As Digital Ad Spend Hits a High, These Firms Could Reap Rewards
By Nathan Reiff. Originally Published: 4/1/2026.
Key Points
Digital ad spending could roughly triple over the next decade, and AI and other innovations may open up a range of new investment opportunities.
Capitalizing on the growth of connected TV ad sales, Magnite shares could more than double according to estimates.
DoubleVerify and Zeta Global offer crucial tools including verification and analytics services, making them essential players in the growing digital ad industry as well.
The digital ad spending market could roughly triple to about $1.6 trillion over the next decade, creating ample opportunities for companies in this fast-growing space. The landscape that was once dominated by major tech players like Alphabet (NASDAQ: GOOG) has shifted as AI-driven targeting and other innovations open room for smaller competitors to gain traction. Three companies in particular stand out for their distinctive positions in the industry—each showing demonstrable growth while trading at valuations that may be below Wall Street’s expectations.
Magnite’s CTV Dominance Could Yield Continued Strong Growth
Magnite Inc. (NASDAQ: MGNI) is a sell-side advertising platform that helps publishers monetize inventory via programmatic advertising across media channels. The company reported a strong final quarter of 2025, with total revenue of $205 million—up 6% year-over-year (YOY)—and net income that more than tripled YOY to $123 million. Management also announced a $200 million stock buyback program.
Since 2009, the Dividend Machine has posted a total return of 7,056.47% – turning a $10,000 stake into more than $700,000 while the broader market struggled through multiple downturns.
With a 93% win rate since launch, this dividend-focused strategy has kept investors cashing steady checks through every crash. Bill Spetrino has released a free report outlining how to position for income no matter what the market does next.Claim your free report and see how the Dividend Machine works
Magnite’s performance was driven largely by connected television (CTV) advertising, which grew sales at a rate of 32% (excluding political ads). The company is positioning itself as an industry leader in CTV and benefits from strong partnerships with key streaming platforms like Netflix (NASDAQ: NFLX)and Roku (NASDAQ: ROKU).
Magnite’s services are also sticky—customers tend to stay because switching to new providers is costly. Beyond the earnings strength, the company sports a price/earnings-to-growth (PEG) ratio of just 0.66, suggesting it could be undervalued relative to future growth prospects. Analysts project more than 51% in earnings gains over the next year, and consensus price targets imply more than 100% upside, with a consensus target above $24 per share.
A Critical Security Procedure Helps to Ensure DoubleVerify’s Value
Operating outside direct ad sales but essential to advertisers, DoubleVerify Inc. (NYSE: DV) provides digital media analytics, ad fraud detection, and verification services. The rise in digital ad spending boosted DoubleVerify’s business: full-year 2025 revenue rose 14% YOY to $748 million, and adjusted EBITDA margin reached 38% in the final quarter of 2025. Like Magnite, its products are sticky—DoubleVerify reported no deactivations among its top 100 customers and strong net revenue retention.
CTV impression measurement volumes are climbing rapidly, and social activation is also expanding—both trends are likely to continue fueling growth. Management guided 2026 revenue of $810 million to $826 million, representing an 8% to 10% YOY increase, and authorized a share repurchase program of up to $300 million.
DoubleVerify’s services could become even more critical if AI-generated content proliferates. More AI content may lead to greater ad fraud, increasing demand for independent verification. Analysts see more than 60% upside potential, with a consensus price target of $16.
Zeta’s Durable Growth Suggests Very Stable Demand
Zeta Global (NYSE: ZETA) is an up-and-coming player in the AI market cloud space, leveraging a large consumer database to help advertisers build and retain customers. In its latest earnings, the company demonstrated why it’s an ascendant name: shares returned more than 17% over the past year despite a slump at the start of 2026.
Revenue surged 25% YOY to $395 million in the final quarter of 2025, while full-year revenue rose 30%. Free cash flow strengthened to $165 million, up 78% YOY, and the number of super-scaled customers increased by nearly 25% over the same period.
Zeta stands out for consistency: it has posted more than four years of sequential beat-and-raise quarters, an indicator of solid demand for its products.
GAAP profitability remains a concern, but the company expects to achieve positive GAAP net income for full-year 2026 for the first time, with midpoint revenue guidance of $1.8 billion (about 35% YOY growth). Analysts also see meaningful share price upside—more than 80% potential—and the company’s new AI platform could be the catalyst that drives that growth.
More Reading from MarketBeat.com
Market Whispers: Is Molson Coors the Next Big Beverage Buyout?
By Jeffrey Neal Johnson. Originally Published: 3/30/2026.
Key Points
The recent acquisition of a popular cocktail brand highlights the company’s successful strategic expansion beyond its traditional beer portfolio.
Several key financial metrics suggest that Molson Coors is fundamentally undervalued, making it an attractive opportunity for discerning investors.
Recent share purchases by company insiders signal strong confidence in the brewer’s future prospects and its commitment to enhancing shareholder value.
A sudden jolt of investor interest has put Molson Coors Beverage Company (NYSE: TAP) in the spotlight. Shares of the brewing giant recently rose after analyst commentary identified Molson Coors as a prime takeover target. This speculation comes as the broader beverage industry buzzes with M&A activity, prompting Wall Street to take a closer look at the numbers and strategy behind one of the consumer staples sector’s most established names.
The buyout chatter isn’t random market noise; it reflects a growing recognition of the significant value embedded within this legacy brewer. For investors, that creates a compelling situation where the market may finally be waking up to a discounted opportunity. The discussion is prompting deeper scrutiny of Molson Coors’ fundamentals, its proactive strategy and the industry trends that make it an attractive acquisition candidate.
Beyond Beer: A Perfect Target in a Changing Market
Since 2009, the Dividend Machine has posted a total return of 7,056.47% – turning a $10,000 stake into more than $700,000 while the broader market struggled through multiple downturns.
With a 93% win rate since launch, this dividend-focused strategy has kept investors cashing steady checks through every crash. Bill Spetrino has released a free report outlining how to position for income no matter what the market does next.Claim your free report and see how the Dividend Machine works
The case for a Molson Coors buyout has a strong strategic foundation. The global alcohol sector is consolidating, with major companies seeking market share and entry into faster-growing categories. Potential combinations among large players — such as chatter around Pernod Ricard (OTCMKTS: PRNDY) and Brown-Forman — underscore that trend, creating a favorable environment for further deals. In this landscape, a company with Molson Coors’ brand recognition and distribution network is a valuable asset.
Importantly, Molson Coors management is playing offense with its Horizon 2030 strategy, a clear plan to adapt to evolving consumer tastes. The most visible proof of that pivot is the recent acquisition of Atomic Brands, maker of Monaco Cocktails — a strategic push into the high-margin Ready-to-Drink (RTD) market, which is projected to grow faster than traditional beer over the next five years. This move complements an existing push into beyond-beer products, including Vizzy Hard Seltzer and a distribution partnership for Topo Chico Hard Seltzer.
That expansion serves two bullish purposes. First, it strengthens Molson Coors as a standalone company by diversifying revenue away from the slow-growth traditional beer market. Second, it makes the company’s brand portfolio far more attractive to a potential suitor. An acquirer wouldn’t just be buying legacy names like Coors Light and Miller Lite; it would gain an immediate and meaningful foothold in one of the fastest-growing beverage segments — making Molson Coors a more valuable target and increasing the rationale for a buyout at a premium.
Why Molson Coors Looks Undervalued
Beyond the strategic fit, Molson Coors’ financials suggest the company is fundamentally undervalued — precisely the kind of deep value that attracts corporate buyers and value investors alike. A closer look at the numbers reveals a compelling case built on a discounted valuation, strong cash generation and a clean balance sheet.
Discounted valuation: Key metrics indicate Molson Coors is trading below its intrinsic value. Its forward price-to-earnings ratio sits at an attractive 6.84, well below many industry peers, and its price-to-book ratio is 0.79 — a P/B below 1.0 can signal the stock is trading for less than the recorded value of its assets.
Superior cash generation: Molson Coors has a low Price-to-Cash-Flow (P/CF) ratio of just 1.52, highlighting efficient conversion of revenue into cash. Strong cash flow supports strategic acquisitions, dividends and other shareholder-friendly activities, and it makes the company appealing to potential acquirers.
A solid foundation: With a debt-to-equity ratio of 0.37, Molson Coors is not over-leveraged. That manageable debt profile reduces acquisition risk compared with competitors carrying heavier debt loads.
Rewarding shareholders: Management has shown a commitment to returning capital. The stock currently offers a dividend yield of 4.5%and a four-year track record of dividend growth, signaling financial discipline and confidence in future performance.
Strong insider confidence: Recent trading shows Molson Coors insiders have been net buyers. That activity includes a notable purchase by a director in March 2026 — a strong vote of confidence from those closest to the company’s prospects.
A Win-Win Scenario: Tapping Into a Bullish Future
For investors, Molson Coors presents a compelling, two-way opportunity for gains. The investment case doesn’t hinge on a single outcome but rather on two distinct, bullish paths that could unlock significant shareholder value.
The first, more immediate path is an acquisition. A strategic buyer could act on the compelling combination of brand assets, distribution reach and undervalued cash flows, acquiring Molson Coors at a meaningful premium to its current price.
The second path is successful execution of the Horizon 2030 strategy. If the company’s pivot into higher-growth beyond-beer categories — like RTDs — accelerates earnings, the market could re-rate the stock to a much higher valuation based on its own merits. For investors seeking a defensive position that combines steady dividend income with upside from either a takeover or operational turnaround, Molson Coors offers a bullish case grounded in tangible value and strategic foresight.
Thank you for subscribing to MarketBeat!
MarketBeat empowers everyday investors to make better trading decisions by offering up-to-the-minute financial information and objective investment research.
This email message is a sponsored email sent on behalf of MarketBeat Alerts, a third-party advertiser of MarketBeat. Why did I get this email message?.
If you have questions or concerns about your newsletter, please contact MarketBeat’s South Dakota based support team at contact@marketbeat.com.
Thanks for signing up for MarketBeat Daily Ratings—we’re excited to have you on board.
Every weekday, you’ll get a curated summary of new “Buy” and “Sell” ratings from Wall Street’s top-rated analysts, the latest stock news, and bonus investing content—all delivered straight to your inbox.
You’re just two quick steps away from completing your sign-up:
1. Make sure our emails go to your inbox
Gmail users: Mobile: Tap the three dots (…) in the top right and select Move to Inbox or Move to Primary Desktop: Click the folder icon at the top and select Move to Inbox or Primary
Apple Mail users: Tap our email address at the top (next to From: on mobile), then select Add to VIP
Other providers: Reply to this message and add newsletters@analystratings.net to your contacts
2. Confirm your subscription
Click this link to confirm your subscription. This verifies your account and ensures you receive your newsletters without interruption instead of getting stuck in your spam filter.
After you confirm, feel free to download our popular free report, “7 Stocks to Buy and Hold Forever” with this link.
Thanks again for subscribing—we look forward to being part of your investing journey.
Matthew Paulson Founder and CEO, MarketBeat.
P.S. If you didn’t mean to subscribe, no problem—you can unsubscribe here.
More Reading from MarketBeat
Valuation to the Moon? SpaceX Gears Up for IPO Liftoff With a Confidential Filing
Written by Jessica Mitacek. First Published: 4/2/2026.
Key Points
Elon Musk has confidentially filed for a SpaceX IPO that could debut as early as June 2026, seeking to raise up to $75 billion.
Following a February 2026 merger with xAI, SpaceX is valued at $1.25 trillion alongside a vertically integrated model combining its dominant launch services and Starlink’s recurring subscription revenue with advanced AI-powered computing.
The company boasts a robust balance sheet with minimal debt, over $15 billion in remaining government contract obligations through 2030, and a Starlink division projected to generate $8.1 billion in pro forma free cash flow by the end of 2026.
On April 1, CNBC reported that Tesla (NASDAQ: TSLA) and Neuralink CEO Elon Musk confidentially filed an IPO for SpaceX with the U.S. Securities and Exchange Commission. The company could be listed on an exchange as soon as June.
Since 2009, the Dividend Machine has posted a total return of 7,056.47% – turning a $10,000 stake into more than $700,000 while the broader market struggled through multiple downturns.
With a 93% win rate since launch, this dividend-focused strategy has kept investors cashing steady checks through every crash. Bill Spetrino has released a free report outlining how to position for income no matter what the market does next.Claim your free report and see how the Dividend Machine works
Founded in 2002, the aerospace manufacturerand space-transport services company is best known for deploying its subsidiary Starlink’s satellites.
SpaceX is reportedly seeking to raise up to $75 billion in its IPO, which would be roughly three times the size of the largest U.S. IPO to date. That record currently belongs to Alibaba Group (NYSE: BABA), which went public in September 2014 after raising $21.8 billion.
At that valuation, Musk would become the first CEO of two trillion-dollar publicly traded companies.
Here is what potential investors and Musk enthusiasts need to know.
A Massive Valuation and Vertically Integrated Business Model
While the satellite stock space may seem as crowded as low-Earth orbit (LEO), the combined market caps of publicly traded peers pale in comparison to SpaceX. Much of the gap reflects the company’s multi-layered, vertically integrated business model.
Following the company’s Feb. 2 merger with xAI—the artificial intelligence (AI) and tech firm also led by Musk—SpaceX’s valuation was placed at $1.25 trillion. Its core launch services business has positioned the company as the world’s leading launch provider, including the SmallSat Rideshare Program, which offers cost-effective access to space by launching multiple small payloads together on a single Falcon 9 rocket.
At the same time, SpaceX has garnered attention for deploying more than 10,000 Starlink satellites into LEO since May 2019, delivering high-speed, low-latency internet globally. Starlink, unlike launch services, provides subscription-based recurring revenue that can produce the steady cash flow investors reward.
Analysts’ year-end forecasts for Starlink in 2026 include:
16.8 million subscribers, implying more than 33% year-over-year (YOY) growth
$11.3 billion in consumer revenue, implying more than 10% YOY growth, with roughly 85% recurring revenue
About 133 Starlink mission launches, up more than 11% YOY, deploying a total of 3,500 satellites—more than 23% YOY growth
$20 billion in total revenue, $14 billion in earnings before interest, taxes, depreciation, and amortization (EBITDA), and $8.1 billion in pro forma free cash flow
The merger with xAI adds another element: a potential unified balance sheet for prospective investors ahead of the IPO. The combined company gives xAI access to SpaceX’s infrastructure and cash flow, while allowing SpaceX to accelerate integration of AI-powered, space-based computing.
SpaceX’s Massive Government Contracts Provide a Baseline of Revenue
Beyond Starlink and its recurring-revenue model, SpaceX has grown into a large defense contractor.
Since 2008, the company has been awarded more than $24.4 billion in federal government contracts. Of that total, roughly $9 billion has been paid out so far, leaving about $15.4 billion in remaining obligations for missions through 2030.
Many of those contracts come from NASA and the Department of Defense, including work for the Space Force, Air Force, and several U.S. intelligence agencies.
SpaceX’s NASA work includes the commercial crew program, which transports astronauts to the International Space Station (ISS) via Crew Dragon, participation in the Artemis Program, commercial resupply services to the ISS, and development of the ISS deorbit vehicle, which is scheduled to escort the research laboratory safely into the Pacific Ocean in 2031.
Wall Street’s SpaceX Expectations
Despite the size of the IPO, SpaceX’s public valuation could be more than 90 times its 2025 revenue. Early estimates suggest a debut per-share price around the $400 level, or possibly higher.
That stock price could be justified if SpaceX maintains a low debt load. After the xAI merger, the company has emphasized presenting a clean balance sheet leading up to the IPO. That approach, combined with the company’s diversified business model, could support strong margins and healthy cash flow—unlike some of Musk’s other firms that have carried large amounts of debt.
Thank you for subscribing to MarketBeat!
MarketBeat empowers investors to make better financial decisions by delivering real-time financial information and objective investment research.
If you have questions about your account, please feel free to email our U.S. based support team at contact@marketbeat.com.
Wall Street’s 2026 playbook just changed, and so did ours. The freshly updated 10 Best Stocks to Own in 2026 report zeroes in on companies that:
Fuel the AI boom through chips, cloud infrastructure, and next-gen computing
Shower investors with cash via rising dividends and aggressive buybacks
Hold pricing power in any rate-cut scenario, guarding your downside
Inside, you’ll find everything from an under-the-radar chipmaker poised to rule edge devices to a household-name retailer sitting on $12 billion in cash—likely primed for another special dividend. Every pick has a hard catalyst that could ignite in the next 12 months.
Real Estate Investment Trusts (REITs) are often popular investments during turbulent times because they return so much capital to shareholders through dividends and buybacks.
In the AI-powered surge over the last few years, REITs have become a forgotten asset class and have lagged the market.
Now that volatility has returned, REITs could be an attractive investment, including these three with fundamental tailwinds.
There was a time when the biggest worry in markets was commercial real estate (CRE), especially for companies that own offices and workplaces now occupied less frequently as many staff continue to work from home. You likely won’t find CRE concerns leading the financial headlines as often anymore, but that doesn’t necessarily mean conditions have improved — there’s still a lot going on. Real Estate Investment Trusts (REITs) have been dragged down with the broader market over the last month, and commercial assets remain a concern for investors. However, a few REITs are flashing oversold signals on key technical indicators, and we’ve identified three that also look solid from a fundamental perspective.
Why REITs Could Be Primed for Strong Growth in 2026
REITs have been a relatively dull asset class over the past five years, with little price appreciation beyond dividend income. The Vanguard Real Estate ETF (NYSEARCA: VNQ), one of the largest broad-based REIT ETFs with more than $33 billion in assets, has lost 5.5% over the last five years; much of that decline occurred in the past month (down about 8%). Until the outbreak of the Iran conflict, REIT investors were only just above water and relied primarily on dividends for returns.
Since 2009, the Dividend Machine has posted a total return of 7,056.47% – turning a $10,000 stake into more than $700,000 while the broader market struggled through multiple downturns.
With a 93% win rate since launch, this dividend-focused strategy has kept investors cashing steady checks through every crash. Bill Spetrino has released a free report outlining how to position for income no matter what the market does next.Claim your free report and see how the Dividend Machine works
That said, there are several reasons to be cautiously bullish on REITs in 2026. Many names have fallen into oversold territory, which technical traders will watch for a rebound. And despite the interest-rate backdrop leaning toward “higher for longer,” analysts expect 2026 to be a constructive year for the sector.
JPMorgan Research projects overall FFO growth of about 6% for the sector this year. Funds From Operations (FFO) measures a REIT’s cash flow by adding amortization and depreciation to net income and then subtracting gains from non-recurring property sales. FFO typically gives a more accurate picture of cash flow than net income alone and is useful for assessing the sustainability of dividends. Because REITs are often treated as income-focused investments, steady dividend growth tends to matter more than short-term stock gains.
These 3 REITs Have Strong Fundamentals and Flashing Oversold Signals
When looking for oversold stocks, it’s important to confirm signals using several technical indicators. The Relative Strength Index (RSI) is a popular starting point because of its simple heuristics and reliability, but it should not be used in isolation. For the three names below, we pair the RSI with other tools such as the Moving Average Convergence Divergence (MACD) indicator to get a clearer picture.
Simon Property Group: Stabilized By an Affluent Customer Base
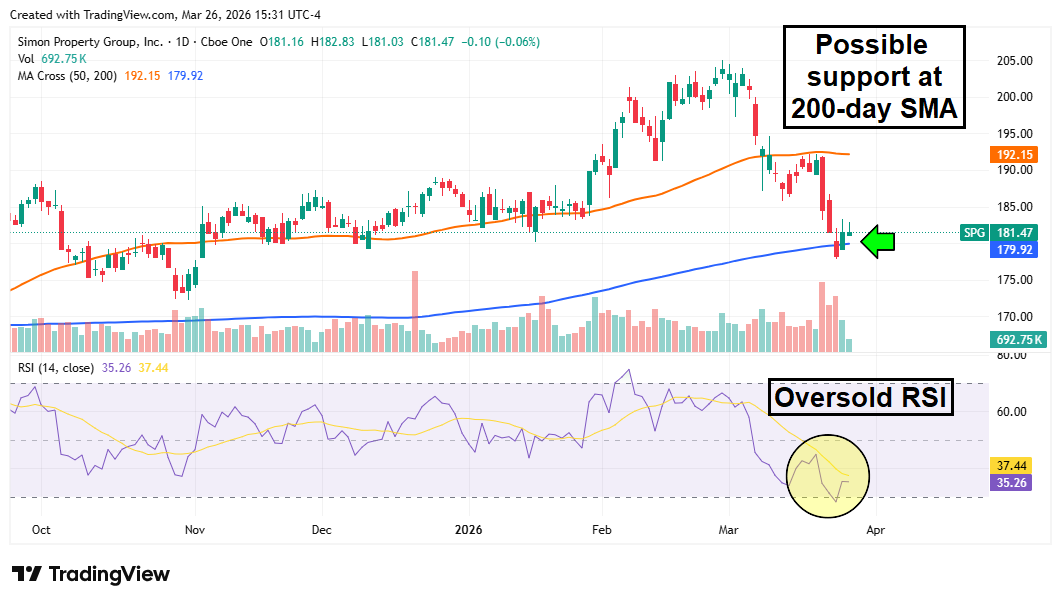
Simon Property Group Inc. (NYSE: SPG), once known primarily as a mall REIT, has repositioned itself as a “destination” operator catering to more affluent customers. While many traditional malls struggled, SPG focused on high-end centers and prime retail properties for luxury brands. That strategy appears to be paying off: in Q4 2025, management reported record annual FFO of $4.8 billion ($12.73 per share) and guided 2026 FFO to about $13.00–$13.25 per share. The company also announced a $2 billion share repurchase (roughly 3% of market cap), with portfolio occupancy above 96% and a 15% year-over-year (YOY) increase in its leasing pipeline.
Simon’s fundamentals show little sign of distress; the stock’s recent weakness likely reflects the broader market pullback rather than company-specific problems. Shares found support at the 200-day moving average just as the RSI reached oversold levels. If the stock holds above the 200-day moving average, this may be an attractive entry point for long-term investors.
Rexford Industrial Realty: Opportunities in California Industrial Zones
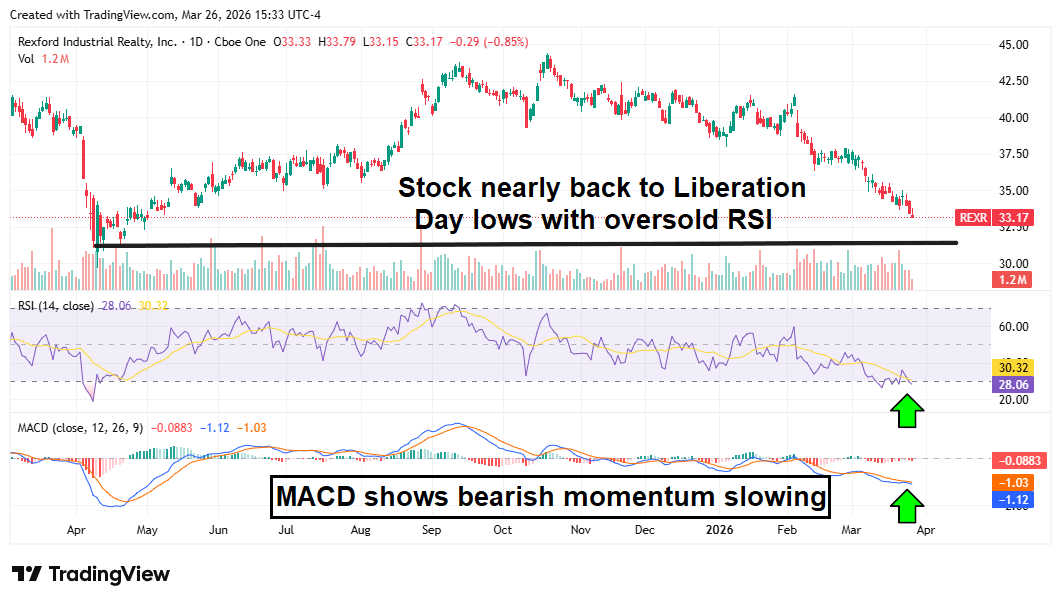
Southern California contains one of the largest infill industrial markets in the U.S., with more than 1.8 billion square feet, but zoning and regulatory constraints often limit new supply and create high barriers to entry. That supply tightness helps push rents higher, benefiting incumbent owners such as Rexford Industrial Realty Inc. (NYSE: REXR), which owns over 400 properties in the region. The stock has been a long-term underperformer over the past five years, but Rexford is in transition: former COO Laura Clark was appointed CEO, and the company authorized $500 million in new share buybacks.
The company has a near-term catalyst on April 15, when it reports Q1 2026 earnings, which could halt or reverse the recent decline. Shares are down about 16% year-to-date, including a 14% drop in the past month. The stock is approaching its April 2025 lows, and both the RSI and MACD suggest that downward momentum is slowing. A bullish MACD crossover ahead of the earnings report would be a useful confirmation of a potential momentum shift.
Vornado Realty Trust: A Contrarian Play on New York Real Estate
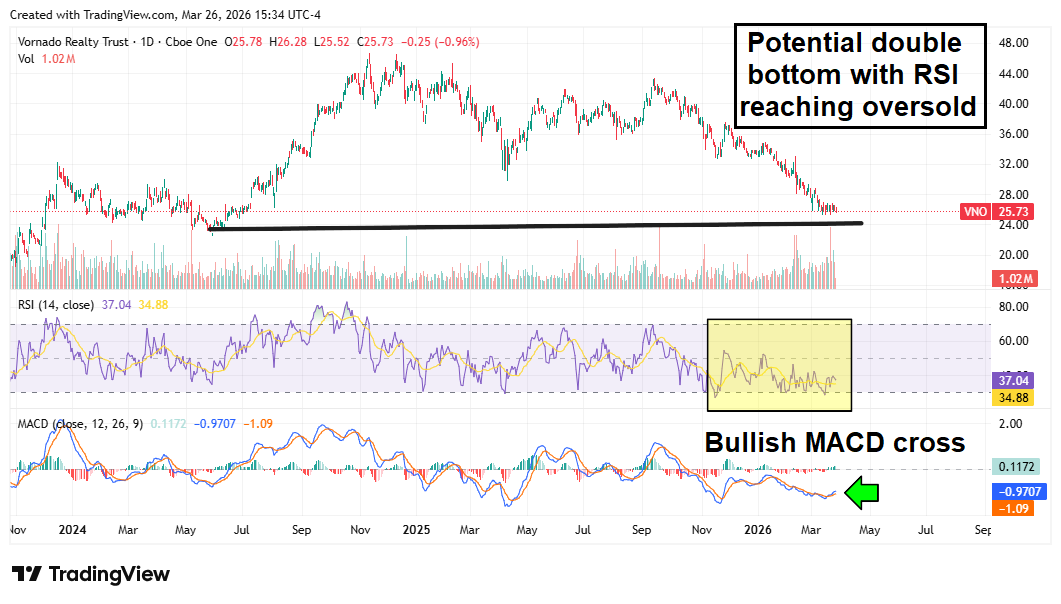
An investment in Vornado Realty Trust (NYSE: VNO) isn’t for the faint of heart — New York commercial real estate was hit hard by the pandemic and has been slow to recover. Still, Vornado reported an industry-leading 4.6 million square feet of Manhattan leasing in 2025, with particular strength in its PENN 1 and PENN 2 districts. Management also noted acquisitions of high-end properties on Fifth Avenue and East 54th Street in its Q4 2025 results. It guided 2026 FFO to be roughly in line with 2025, a cautious projection that nevertheless leaves room for upside if leasing momentum continues.
VNO shares show a chart pattern similar to REXR, with signs of a rebound forming. The RSI has spent much of the past two months in oversold territory, near spring 2025 lows. Importantly, the MACD has crossed above its signal line, suggesting that selling pressure may be easing and buyers could be returning.
Thank you for subscribing to MarketBeat!
We empower individual investors to make better trading decisions by providing real-time financial information and unbiased investment analysis.
If you have questions or concerns about your subscription, please feel free to contact our South Dakota based support team at contact@marketbeat.com.
Visa made $36 billion last year being a middleman.
Mastercard made $28 billion.
PayPal made $30 billion.
That’s almost $100 billion from three companies that don’t produce anything. They just sit between two parties who want to transact and take a cut of everything.
2 Actively Managed Defense ETFs That Can Pivot as the War Evolves
Reported by Nathan Reiff. Posted: 4/1/2026.
Key Points
Two prominent actively managed ETFs holding defense stocks have surged in recent months even as the broader market has faltered.
IDEF has wide latitude in seeking out global defense names, giving it excellent room to pivot in light of new information related to geopolitical conflicts.
ARKX is a space-focused fund that has considerable overlap with defense industry names as well.
With actively managed exchange-traded funds (ETFs) growing increasingly popular relative to traditional passive funds, investors may find these vehicles advantageous for timely investment themes, such as the ongoing conflict involving Iran. A key benefit of active funds is that managers can adjust portfolios in real time to reflect market developments, whereas many passive funds track indices that are only rebalanced periodically.
Active management typically carries higher annual fees, but it can be worth the cost if managers can generate stronger performance in a fast-moving environment. The situation in and around Iran is exactly that type of scenario: with frequent updates on U.S. objectives and strategy, and continued disruption in energy markets, defense stockinvestors need to be nimble. The active defense ETFs below may be a good starting point for those who prefer to outsource timely portfolio moves.
A Broad International Defense and Security Fund, but With Minimal Performance History
Since 2009, the Dividend Machine has posted a total return of 7,056.47% – turning a $10,000 stake into more than $700,000 while the broader market struggled through multiple downturns.
With a 93% win rate since launch, this dividend-focused strategy has kept investors cashing steady checks through every crash. Bill Spetrino has released a free report outlining how to position for income no matter what the market does next.Claim your free report and see how the Dividend Machine works
The iShares Defense Industrials Active ETF (NASDAQ: IDEF) has a broad mandate focused on companies that could benefit from increased global defense and security spending. It can hold aerospace, defense, infrastructure, and cybersecurity firms worldwide, although roughly 60% of the basket is made up of U.S.-based stocks. Other notable country exposures include South Korea, the United Kingdom and Japan.
IDEF’s holdings tend to be companies that could gain from higher government defense budgets driven by geopolitical turmoil—making it particularly responsive to conflicts such as those in Iran and Ukraine.
Despite relatively large weightings in a handful of big names, IDEF is still one of the more diversified defense ETFs available. It is also relatively inexpensive for an active fund, with an expense ratio of 0.55%. What it lacks is a long track record: IDEF launched in May 2025 and does not yet have a full year of performance history. Since launch it has returned more than 25%, despite a roughly 15% selloff in the last month amid broader market weakness.
A Space-Focused Fund With a Defense Angle
The ARK Space Exploration & Innovation ETF (BATS: ARKX) approaches defense exposure through a space-technology lens. There is significant overlap between space technology and defense—companies working on intelligent devices, autonomous mobility, reusable rockets and related innovations can find opportunities in both commercial space and defense markets.
ARKX holds fewer than three dozen positions, so it is relatively concentrated. Its expense ratio is higher than IDEF’s at 0.75% annualized.
Investors should note that ARKX is not a pure-play defense fund; it also includes broader technology and industrial companies such as Amazon.com Inc. (NASDAQ: AMZN) and Alphabet Inc. (NASDAQ: GOOG), although these appear at smaller weights compared with its core space and defense-related holdings (see the fund’s portfolio).
ARKX has a longer performance history than IDEF; it launched five years ago and posted a one-year total return of nearly 60%. Like IDEF, it has pulled back recently—by roughly 13% in recent weeks.
Because ARKX focuses narrowly on space-related firms, managers may be more likely to adjust portfolio weightings than to change the fund’s underlying investment universe in response to breaking news. Still, shifts in allocations can materially affect returns in a rapidly changing market.
Special Report
Compass Diversified’s $292M Sale Ignites Stock
Reported by Jeffrey Neal Johnson. Posted: 4/7/2026.
Key Points
Compass Diversified’s recent divestiture provides the company with substantial capital to significantly reduce its debt and improve its overall financial flexibility.
This successful transaction serves as powerful proof of management’s ability to create shareholder value through its unique business strategy.
A new activist investor has endorsed the move with a major stake, signaling strong external confidence in Compass Diversified’s future direction.
Shareholders of Compass Diversified (NYSE: CODI)saw a meaningful portfolio boost on March 30, 2026, when the company’s stock jumped more than 15% in a single trading day.
That sharp move was not speculation-driven but a direct market response to a major strategic announcement: Compass Diversified disclosed a definitive agreement to sell the Sterno foodservice business, a deal that will generate substantial cash proceeds.
Since 2009, the Dividend Machine has posted a total return of 7,056.47% – turning a $10,000 stake into more than $700,000 while the broader market struggled through multiple downturns.
With a 93% win rate since launch, this dividend-focused strategy has kept investors cashing steady checks through every crash. Bill Spetrino has released a free report outlining how to position for income no matter what the market does next.Claim your free report and see how the Dividend Machine works
The transaction marks a pivotal moment for Compass Diversified, materially improving its financial profile and validating management’s strategic plan.
The sale not only supports the company’s long-term vision but has also drawn the attention of influential new investors. Together, these developments have materially altered the investment case for Compass Diversified.
The $292.5 Million Balance Sheet Overhaul
Investor enthusiasm centers on both the size of the Sterno transaction and the planned use of proceeds. Compass Diversified agreed to sell the foodservice portion of its Sterno brand to Archer Foodservice Partners, a portfolio company of Wynnchurch Capital.
The key deal facts:
Asset Sold: The Sterno foodservice business, a leader in portable heating solutions for catering, foodservice, and the restaurant sector.
Enterprise Value: Approximately $292.5 million, which reflects the total business value, including debt.
Importantly, this is a partial divestiture. Compass Diversified will retain Sterno’s home fragrance business, which will be rebranded as Rimports and continue generating revenue. That preserves an ongoing consumer revenue stream while unlocking significant cash from the sale.
Management has said the proceeds will be used aggressively to reduce debt. After the transaction, Compass Diversified expects its senior secured net leverage ratio to fall below 1.0x — a materially stronger position that should lower interest expense, free up cash flow, and provide greater flexibility to fund operations and pursue growth.
Strategy Vindicated, Confidence Endorsed
The Sterno sale supports the bull case on two fronts: it validates Compass Diversified’s business model and it attracted a high-profile investor stake.
Compass Diversified operates like a publicly traded private equity firm: it acquires controlling interests in established middle-market companies, applies capital and operational expertise to drive growth, and eventually monetizes investments through sales. The Sterno divestiture is a clear example of that strategy working — a successful exit that delivers cash and demonstrable returns for public shareholders. The market’s immediate, double-digit reaction underscores investor recognition of that execution.
Shortly after the announcement, ADW Capital Partners filed a Schedule 13D disclosing a 9.9% beneficial stake in Compass Diversified. A 13D filing typically signals an activist position and an intent to influence strategy. The timing implies ADW views the Sterno sale as a meaningful value-unlocking catalyst. ADW’s position also includes call options, an explicitly bullish instrument that amplifies its positive view on the company’s prospects.
From Defense to Offense: Reloaded for Growth
With Sterno proceeds and a strengthened balance sheet, Compass Diversified can shift from defense to offense. Reduced leverage and improved liquidity will make the company a more opportunistic buyer in the middle market, better positioned to pursue platform acquisitions that drive long-term growth.
Analysts are starting to reflect this improved outlook. While the consensus rating remains a Hold — often a cautious stance while the market digests major news — the average 12-month analyst price target of $11.50 suggests there may still be upside from current levels. That view frames the Sterno sale as both a remedy for prior balance-sheet concerns and the launching pad for future value creation.
The Next Chapter for Compass Diversified
The divestiture of Sterno’s foodservice unit is a transformative event for Compass Diversified. It meaningfully de-risks the company’s financial profile while reinforcing its buy-build-sell strategy.
Combined with a strengthened balance sheet and the endorsement of an activist investor, Compass Diversified has reset its financial narrative and positioned itself for a new phase of growth. For investors and the broader market, the company’s recent moves make it a compelling story worth renewed attention.
This email is a paid advertisement for Decentralized Masters, a third-party advertiser of MarketBeat. Why did I get this email message?.
If you need assistance with your account, please email MarketBeat’s U.S. based support team at contact@marketbeat.com.