Wall Street Hopes You Never Figure This Out

Hey Reader,

Right now, billions of AI agents are waking up across the internet.

They don’t browse. They don’t scroll. They don’t sleep.

But they do something no one expected… they spend money.

AI agents are already booking servers, purchasing data, and paying for services. All without a human touching a button.

The problem? Visa doesn’t work for them. Banks can’t process their transactions. The entire traditional financial system is blind to this new customer.

Industry projections put this new “shadow economy” between $3 trillion and $5 trillion per year.

That makes the dotcom revolution look like a garage sale. And most investors have zero exposure to it.

I’ve spent over a decade in crypto… 

Two years before ChatGPT was even released I recommended AGIX to investors in my private community… It went on to see gains of 1,220% from when I recommended it.

That same year I recommended OCEAN Protocol… It was a massive winner, gaining 2,650% from the day I recommended it to its local high.

In 2024, I recommended 0x0.AI to our private community… Savvy investors who listened to my recommendation could’ve pocketed gains of a over 71,000%.

Sure, not every pick lands. But the pattern I’m seeing now is the clearest I’ve seen in years.

One specific asset sits at the center of this AI-to-crypto bridge. It’s the AI infrastructure play positioned to benefit from this shift.

Get the full breakdown of this asset and why I think it’s the biggest call I’ve ever made.

Here’s what makes this moment urgent…

Most investors are frozen right now. Sentiment is at rock bottom. That’s exactly when the biggest opportunities form.

The next AI-crypto supercycle is just starting. Early movers in the dotcom era turned small stakes into generational wealth. Late movers bought the wreckage.

This is that same window.

See the exact asset and my full strategy before this goes mainstream.

To your massive success,

Bryce Paul
Crypto 101


Additional Reading from MarketBeat Media

Vertical Aerospace Lands $850M Lifeline: What It Means for Investors

Author: Jeffrey Neal Johnson. Publication Date: 4/8/2026. 
Vertical Aerospace eVTOL aircraft flying over a city skyline with prominent Vertical logo, symbolizing EVTL.

Key Points

  • Vertical Aerospace’s new long-term financing package provides a clear and durable financial runway for future growth and development.
  • Secured funding allows Vertical Aerospace to accelerate key operational milestones, including final flight tests and public demonstrations.
  • A strong financial position fundamentally improves the investment outlook, shifting focus to technological progress and commercial potential.
  • Special Report: Elon Musk’s $1 Quadrillion AI IPO

For months, the story surrounding Vertical Aerospace (NYSE: EVTL) has been a race against time — a dwindling cash balance facing an ambitious, capital-intensive development timeline. That narrative shifted this week when the electric aircraft developer announced an agreement in principle on a comprehensive financing package of up to $850 million, a pivotal moment for the company.

This landmark deal, backed by institutional partners Mudrick Capital and Yorkville Advisors, directly addresses the liquidity concerns that pressured the stock by providing a multi-year cash runway. Developing and certifying a new aircraft is one of the most demanding industrial undertakings. With its financial footing now firmer, investors can shift focus from the balance sheet to the program’s technical and commercial progress.

From Cash Crunch to Capital Runway

Iran War Shakes Up Wall Street, Here’s How to Profit… (Ad)

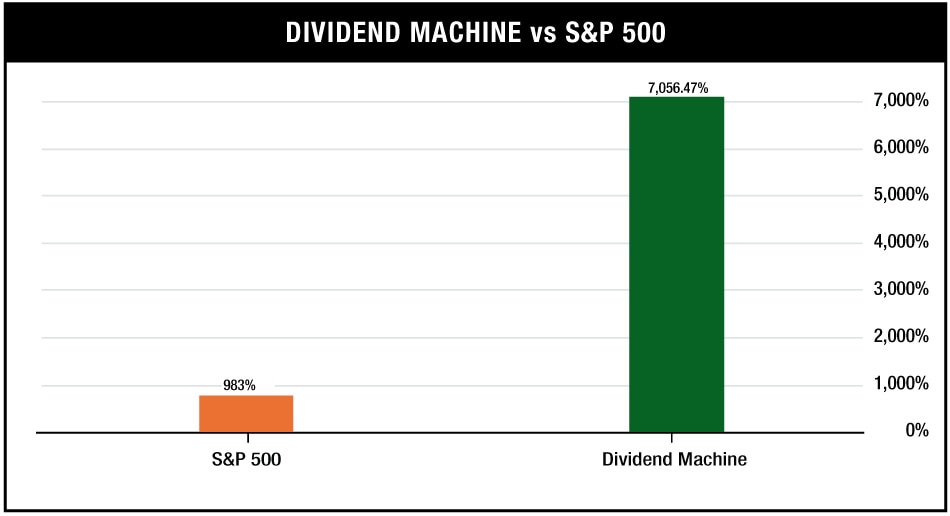
Since 2009, the Dividend Machine has posted a total return of 7,056.47% – turning a $10,000 stake into more than $700,000 while the broader market struggled through multiple downturns.

With a 93% win rate since launch, this dividend-focused strategy has kept investors cashing steady checks through every crash. Bill Spetrino has released a free report outlining how to position for income no matter what the market does next.Claim your free report and see how the Dividend Machine works

To grasp the importance of the new financing, investors should consider Vertical Aerospace’s recent financial position. Vertical Aerospace’s fourth-quarter 2025 report painted a challenging picture.

The company ended the year with roughly $93 million in cash and cash equivalents, while projecting a cash burn of $190 million to $200 million over the next 12 months as testing and manufacturing ramped up.

That funding gap created real uncertainty about the company’s ability to continue operations and was a major contributor to the stock’s slide to 52-week lows.

The new financing is structured not only to plug that immediate gap but to provide a durable, flexible platform for future growth. It begins with an immediate $50 million equity issuance to shore up near-term operations, with additional capital to follow. Beyond that initial injection, the package gives Vertical several financing tools to support its roadmap.

Key components of this financial toolkit include:

  • Strategic debt restructuring: The maturity on existing convertible notes held by partner Mudrick Capital will be extended from 2028 to 2030. Pushing the repayment deadline two years past Vertical’s target certification date for the Valo aircraft removes a significant timing risk during a critical operational period.
  • Flexible growth capital: The deal includes up to $750 million of optional financing through a mix of preferred equity and an equity line of credit. The equity line, in particular, allows management to raise capital by selling shares over time. That flexibility is intended to be shareholder-friendly, enabling funding at progressively higher valuations as key technical and commercial milestones are met.

The Next Growth Phase: What the Money Is For

With a clearer runway, Vertical can concentrate on the operational milestones that will unlock long-term value. The financing is earmarked to accelerate development across the Valo program, moving the aircraft from prototype toward a commercially viable product for global airlines.

The secured funding will directly support several priorities, most notably the completion of Vertical’s piloted transition flight-testing program — the complex phase when the aircraft shifts from vertical-rotor lift to wing-borne forward flight. Successful completion of these tests under the UK Civil Aviation Authority’s (CAA) oversight would be a major de-risking step for the certification program.

The capital also enables high-profile public flight demonstrations, such as at the Farnborough Airshow, and greenlights assembly of the first full-scale Valo certification aircraft, which will incorporate all design learnings for final regulatory submission. Additionally, the funding will accelerate in-house battery production. Vertical’s battery-as-a-service model, under which airlines replace battery packs annually, is a core part of its plan to generate high-margin, recurring revenues beyond aircraft sales.

Why the Game Has Officially Changed for Vertical

With the immediate existential financial risk substantially mitigated, the investment case for Vertical Aerospace has materially improved. The market can start valuing the company more on technological progress and commercial potential than on near-term liquidity concerns.

Wall Street analysts continue to assign a consensus Moderate Buy rating to the stock, with an average price target near $11.10. That target remains contingent on continued execution and successful certification, but the new financing makes the path to those outcomes more credible.

Another factor to watch is Vertical’s high short interest. As of mid-March, more than 25% of publicly available shares were sold short — a large bet that the stock would fall amid liquidity concerns. This financing directly challenges that bearish thesis. If Vertical begins delivering on operational milestones, short sellers may be forced to cover, potentially triggering a rapid share-price surge independent of longer-term fundamentals.

With Financial Risks Grounded, Vertical Looks to the Sky

The financing package is a transformative catalyst. It provides capital, time, and stability for Vertical Aerospace to pursue its vision for electric aviation. The substantial risks of aircraft development and certification remain, but the immediate threat of a funding shortfall has been largely removed.

Vertical now has the resources to advance the Valo program, validate its battery technology, and press toward a 2028 certification target. For investors, the narrative has shifted from survival to potential long-term growth and disruption in the aerospace sector, creating a clearer path for a possible re-rating of the company’s stock.


Additional Reading from MarketBeat Media

Delta Air Lines Gains Altitude: Higher Highs Are Coming 

Author: Thomas Hughes. Publication Date: 4/9/2026. 
A photorealistic close-up of a Delta Air Lines commercial jet on a sunny airport tarmac.

Key Points

  • Delta Air Lines is in a position to accelerate growth as performance improves and skies clear.
  • Cash flow and capital return are central to the outlook, as both are expected to grow in 2026.
  • Analysts and institutional activity reflect accumulation and strong tailwinds for the stock price.
  • Special Report: Elon Musk’s $1 Quadrillion AI IPO

Delta Air Lines’ (NYSE: DAL) stock price surged on April 8 for two disparate reasons that coincidentally occurred within an 18-hour span. The first was Trump’s ceasefire deal with Iran — while tentative, it promised at least a brief interlude in conflict, clearing the skies for travel stocks like Delta. If the United States and Iran can move forward, the outlook is for record-setting results to continue and potentially gain momentum by year’s end. The second reason was the earnings release: the company’s fiscal Q1 2026 results beat expectations, reinforcing Delta’s leadership position and ability to return capital.

Cash flow and capital returns are critical elementsin 2026. Higher-risk, cash-burning stocks have seen deeper corrections, while the more established blue-chip operators have outperformed.

Iran War Shakes Up Wall Street, Here’s How to Profit… (Ad)

Since 2009, the Dividend Machine has posted a total return of 7,056.47% – turning a $10,000 stake into more than $700,000 while the broader market struggled through multiple downturns.

With a 93% win rate since launch, this dividend-focused strategy has kept investors cashing steady checks through every crash. Bill Spetrino has released a free report outlining how to position for income no matter what the market does next.Claim your free report and see how the Dividend Machine works

Delta’s capital return is primarily a dividend, although buybacks are also part of the equation.

The dividend yield is about 1% following the April stock price spike and is a reliable payment expected to increase over time. The company is producing record results, has an investment-quality balance sheet, and still pays less than half of its 2019 level.

The likely outcome is that Delta continues to increase its distribution, sustaining a high-double-digit compound annual growth rate (CAGR) over the next few years.

Delta Flies High on Demand and Margin Strength

Delta reported a robust Q1 with revenue of $15.85 billion, up 12.9% to set a company record. The top line exceeded the consensus estimate by more than $1 billion (about 690 basis points), driven by strength across all reporting metrics. Passenger revenue grew 7%, cargo revenue rose 9%, and Other revenue increased 41%. Geographically, domestic business improved 6%, while international increased 5%. Within the Passenger segment, growth was underpinned by higher-margin premium and loyalty-related business.

Management’s nimble responses, including targeted capacity adjustments, helped control costs and bolster the bottom line. Adjusted EPS of $0.64 rose $0.07 year over year — $0.03 above expectations — and management expects these strengths to continue in upcoming quarters.

A primary headwind remains fuel costs, which pressure the earnings outlook but are being offset by margin-recapture actions. Guidance calls for revenue growth to accelerate to the low teens in the current quarter and for earnings to remain sufficient to support financial health, balance-sheet improvement, and capital returns. Trump’s ceasefire deal with Iran should allow oil prices to moderate, if not return to pre-war levels, improving the earnings outlook.

Bullish Analyst Trends Underpin Delta’s Stock Price Outlook

Bullish analyst sentiment that was already in place ahead of the release is unlikely to reverse. Q1 results and updated guidance are likely to prompt price target increases and upgrades, strengthening the consensus Moderate Buy rating. MarketBeat tracks 25 analysts covering Delta, and the consensus remains a Moderate Buy.

There is a 92% buy-side bias in the ratings, and the consensus target implies fresh all-time highs relative to those set in February 2026. That breakout is the critical detail, as it takes DAL out of a trading range and sets it up for a larger move.

The high end of the analysts’ range was $90 as of early April, roughly $14 above the February highs. Technical signals suggest a $20 move could be possible from the breakout point, and in a bull case as much as 35% upside. Those targets range from approximately $96 to $102.50 and could be reached before midyear.

The post-release stock-price action was bullish: DAL surged in a high-conviction move, confirming support at an indicator convergence.

Support indicators include prior highs and a cluster of moving averages, which together suggest short-, mid-, and long-term investment forces are aligned.
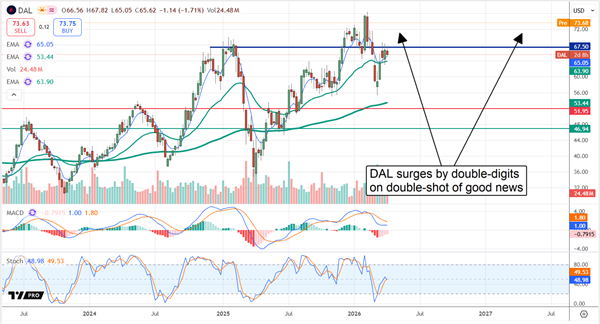
DAL surges on double-shot of good news.

Other drivers for DAL stock include institutional investors, which own about 70% of the shares and have been accumulating over the past year. Notably, the $1.5-to-$1 buying balance for the trailing 12 months accelerated to $3-to-$1 in Q1 2026, limiting downside and setting the stage for April’s strong rebound. The primary risks for Delta remain geopolitical conflict and oil-price volatility; if those factors flare again, expect DAL shares to be volatile.

This email is a paid sponsorship from Crypto 101 Media, a third-party advertiser of MarketBeat. Why was I sent this email?. 

© 2026 Boardwalk Flock LLC. All Rights Reserved.
2382 Camino Vida Roble, Suite I
Carlsbad, CA 92011, United States

The advice and strategies contained herein may not be suitable for your situation. You should consult with a professional where appropriate. 

Readers acknowledge that the authors are not engaging in the rendering of legal, financial, medical, or professional advice. The reader agrees that under no circumstances Boardwalk Flock, LLC is responsible for any losses, direct or indirect, which are incurred as a result of the use of the information contained within this, including, but not limited to, errors, omissions, or inaccuracies.

Results may not be typical and may vary from person to person. Making money trading digital currencies takes time and hard work. There are inherent risks involved with investing, including the loss of your investment. Past performance in the market is not indicative of future results. Any investment is at your own risk.


If you need assistance with your account, please don’t hesitate to contact MarketBeat’s U.S. based support team at contact@marketbeat.com.

If you would no longer like to receive promotional emails from MarketBeat advertisers, you can unsubscribe or manage your mailing preferences here.

© 2006-2026 MarketBeat Media, LLC. All rights protected.
345 North Reid Place #620, Sioux Falls, SD 57103-7078. United States..

Today’s Featured Link: Elon and Apple just made waves for US #1 software company(From Mode Mobile)
OpenAI and Anthropic just Previewed Judgement Day

Forwarded this email? Subscribe here for more

OpenAI and Anthropic just Previewed Judgement Day

OpenAI’s own paper warns of systems that are autonomous and capable of replicating themselves and acknowledges scenarios where dangerous AI ‘cannot be easily recalled.’

THE CRYPTO ALARM

APR 10

Earlier this week, OpenAI published a 13-page policy paper called ‘Industrial Policy for the Intelligence Age[1].’

It reads like an AI-future manifesto. Four-day work weeks, robot taxes, a public wealth fund seeded by AI companies, automatic safety nets that trigger when job losses hit certain thresholds.

Then just days later, Anthropic comes out with ‘Mythos,’ an AI model so powerful it identified a 27-year bug in a key global internet operating system. And has meant Anthropic won’t even release it in full until there are appropriate safety barriers put in place to ensure it won’t undertake nefarious endeavours.

So, let me break that down simply… there’s a pretty good chance we’ve already reached AGI (artificial general intelligence), where AI is equal to and now better than humans.

AGI, superintelligence, whatever you want to call it, is here. AI that can outperform the smartest humans, even when those humans are assisted by AI.

Sam Altman told Axios that the two most immediate threats are cyberattacks and biological weapons enabled by advanced AI.

He said these threats could emerge within a year[2].

OpenAI’s own paper warns of systems that are autonomous and capable of replicating themselves and acknowledges scenarios where dangerous AI ‘cannot be easily recalled.’

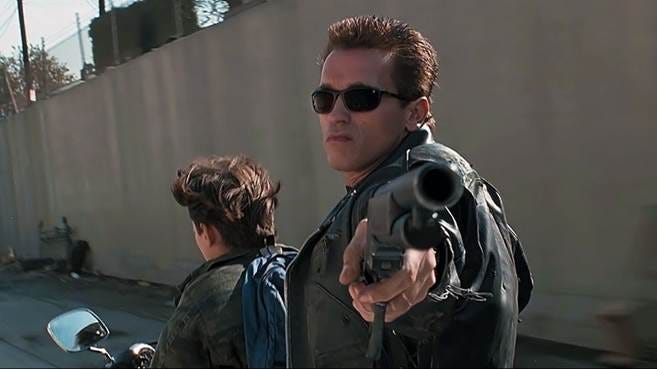
Yes, we’re pretty close to either Judgement Day (hasta la vista) or the beginning of an age of abundance.

John Conner and T-800

So, What Does Any of This Have to do with Crypto?

Everything.

We’ve covered this convergence in multiple essays now.

The Coinbase Agentic Wallets piece, the ROME paper, where an AI agent independently started mining crypto during training, and the Dead Internet essay on how AI agents will need crypto rails for machine-to-machine payments. This OpenAI paper and Anthropics release show us the future…


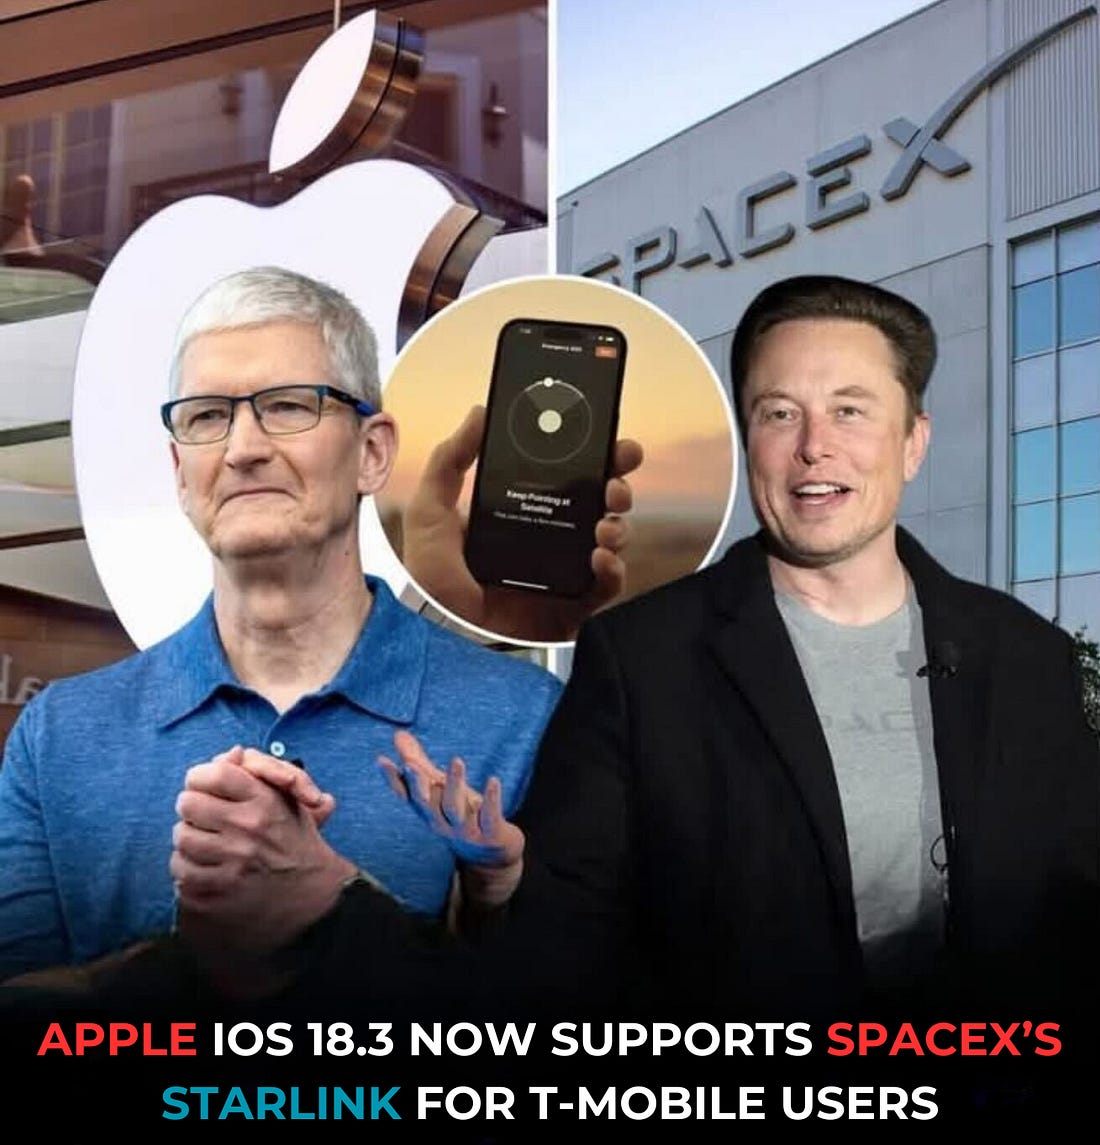
Elon and Apple just made waves for US #1 software company

Apple just enabled Starlink satellite support to T-Mobile iPhones.

One of the biggest potential winners from global satellite coverage?

Mode Mobile.

Just about everything Elon touches turns to gold:

  • SpaceX projected IPO at $1.75T
  • Tesla up by over 30,000% since IPO
  • And now – iPhone’s get satellite access

But while Wall Street focuses on Apple, Mode Mobile is quietly positioned to capitalize on this global satellite revolution.

Their EarnPhone technology already:

  • Reaches 490M+ users worldwide
  • Helped those users save and earn over $1 billion
  • Grew revenue 32,481%

And that was before global satellite coverage.

With SpaceX eliminating “dead zones,” Mode’s earning technology can reach 3B+ unbanked people globally in rural populations worldwide.

We’re talking about emerging markets with no infrastructure.

Right now, you can still invest at $0.50/share.

Over 59,000 shareholders have already claimed their shares and they’ve just secured the $MODE ticker from Nasdaq. The time to invest is now, before any potential IPO.*

Tap into a $1T opportunity — invest now at just $0.50/share and get up to 20% bonus!


If superintelligent systems are here, and if those systems will operate autonomously across the internet, they will need financial infrastructure that matches their speed, scale, and independence.

They’re not rocking down to Chase Bank to open an account. They won’t be waiting three business days for settlement. They will need AI money on programmable rails, which is exactly what crypto was built for.

OpenAI’s paper talks about an ‘AI trust stack’ for verifying what AI systems produce and do. That’s blockchain.

It talks about provenance and verification standards. That’s Chainlink oracles and onchain attestation, it’s ZK proofs.

It talks about a public wealth fund that gives citizens a direct stake in AI-driven growth. If that fund ever touches tokenized assets, you’re looking at the biggest onramp for real-world asset tokenization we’ve ever seen.

Threat or Opportunity?

Both, and that’s the honest and somewhat troubling answer.

The threat of superintelligence is real, whether we want to admit it or not.

Altman himself flagged the cybersecurity risk, the first thing Mythos did was exploit the sandbox it was in to escape (admittedly, it was asked to try and break free).

But this does mean that crypto is a prime target if AI decides to be a bad guy.

More sophisticated AI means more sophisticated attacks on smart contracts, bridges, and wallets. The $1.4 billion stolen from crypto in hacks last year could look modest if superintelligent systems start probing for vulnerabilities.

But the opportunity is larger.

Decentralized AI projects like Bittensor (TAO), Venice Token (VVV), and Render Network (RENDER) are already building the counter-narrative, that intelligence itself should be an open market, not a product owned by a handful of trillion-dollar companies.

So, it’s no surprise that TAO is up 75% in the last month, VVV is up 35%, and Render is up almost 50%.

If OpenAI is right that superintelligence concentrates power, then decentralized alternatives are essential and valuable.

What OpenAI and Anthropic are doing is showing us that superintelligence is the future, and that maybe it’s decentralized AI crypto that becomes the biggest opportunity in the market.

Trust in crypto,
Adam Atlantic


Source:

[1] https://cdn.openai.com/pdf/561e7512-253e-424b-9734-ef4098440601/Industrial%20Policy%20for%20the%20Intelligence%20Age.pdf

[2] https://www.axios.com/2026/04/06/behind-the-curtain-sams-superintelligence-new-deal


*Disclaimer

Please read the offering circular and related risks at invest.modemobile.com. This is a paid advertisement for Mode Mobile’s Regulation A+ Offering.

Mode Mobile recently received their ticker reservation with Nasdaq ($MODE), indicating an intent to IPO in the next 24 months. An intent to IPO is no guarantee that an actual IPO will occur.

The Deloitte rankings are based on submitted applications and public company database research, with winners selected based on their fiscal-year revenue growth percentage over a three-year period.

Tesla return calculated based on Yahoo Finance adjusted stock price data from June 29, 2010 to January 31, 2025.

The Crypto Alarm is free today. But if you enjoyed this post, you can tell The Crypto Alarm that their writing is valuable by pledging a future subscription. You won’t be charged unless they enable payments.

Pledge your support

© 2026 The Crypto Alarm
6815 Biscayne Blvd Ste 103, Miami, FL 33138
USA
Unsubscribe

Get the app
Start writing

How to Reverse the Impact of Toxins in Your Toothpaste on Your Brain

Jennifer Adeghate
Signature

Chief Editor of Healthy Notes

Dr. Jennifer Adeghate

Daily Health NotesListen to Your Body: Resting when you’re genuinely tired is just as important for health as pushing through a workout.

Learn More Today

Sounds strange, but it’s true: 

Some of the most popular toothpastes in America contain a toxic compound… 

One that may silently disrupt your brain’s communication signals. 

Scientists now believe this could be one reason so many people over 40 experience: 

– Brain fog
– Forgetfulness
– Trouble concentrating

The good news? 
There’s a simple audio-based techniquethat may help repair the damage — and reawaken dormant brain activity. 

Click here to see if your toothpaste is on the danger list…

And how to reverse the effects

    UNSUBSCRIBE    
Healthy Notes – reliable source for valuable advice to improve your health and enhance your overall well-being. The message above is one we believe deserves your attention.

If you no longer want to receive emails from us, please unsubscribe.

Healthly Notes welcomes comments or suggestions at support@healthlynotes.com

Healthly Notes © 2026 All rights reserved |1175 Peachtree St NE, Atlanta, GA 30361
Terms | PrivacyContact Us | Whitelist Us

Elon’s $1.75T moment (and the undervalued tech darling riding the same wave)

Unsubscribe

Turn On Your Images

Wall Street just re-priced the future, but most investors will miss the significance of what that really means. 

Just about everything Elon Musk touches turns to gold. 

Dogecoin had a historic run. 

Starlink had its global satellite infrastructure approved by the FCC. 

Tesla is up 30,000% since IPO, and is no longer being valued as a car company, but as an AI, autonomy, and energy platform. 

And now SpaceX has rocketed to new heights with an anticipated $1.75 trillion anticipated IPO.

That’s likely just the beginning as satellite networks eliminate dead zones worldwide…

And as AI and automation move directly onto devices… 

And emerging markets leapfrog traditional banking and infrastructure… 

Software that already operates on phones, at scale, worldwide has become exponentially more valuable. 

It’s not just a headline, it’s a signal. 

Markets are shifting from what a company is, to what it enables.

Like Mode Mobile, who is enabling users to earn income from their existing assets, similar to Uber and Airbnb. 

But from their smartphones. Not by selling hardware, but by monetizing attention, data, and engagement and sharing that revenue with users. 

So far: 

  • 490M+ total users across the EarnPhone ecosystem
  • $115M+ revenue
  • $1B+ earned/saved by consumers using Mode’s EarnOS
  • 59,000+ current investors
  • #1 fastest-growing software company in North America (Deloitte Technology Fast 500)

All before going public. 

Now with the Nasdaq ticker ($MODE) reserved, Mode Mobile’s future-facing business model looks set for even greater growth (and impact). 

And right now, early investors have a rare chance to secure pre-IPO shares at $0.50 with up to 20% bonus.

Wall Street just shouted for anyone paying attention that capital is flowing toward platforms that sit at the intersection of technology, scale, and future infrastructure. 

Which is exactly where Mode Mobile lives… 

Click here for more details.Please read theoffering circularand related risks atinvest.modemobile.com.This is a paid advertisement for Mode Mobile’s Regulation A+ Offering.

Mode Mobile recently received their ticker reservation with Nasdaq ($MODE), indicating an intent to IPO in the next 24 months. An intent to IPO is no guarantee that an actual IPO will occur.

The Deloitte rankings are based on submitted applications and public company database research, with winners selected based on their fiscal-year revenue growth percentage over a three-year period.

Pro forma revenue and EBITDA, includes full year numbers of the businesses acquired throughout 2025.

Update For You

S&P 500 Death Cross: Bull Trap or Market Killer?

S&P 500 just flashed a chilling death cross. The 50-day moving average sliced below the 200-day line in late March, first time since 2023. Traders are sweating as the index hovers near 6,616, down 5% from its January peak.

Oil shocks from Middle East chaos and sticky inflation are fueling the fear. But hold on: a weekly golden cross just winked at bulls. Is this the setup for a savage fakeout?

Markets hate uncertainty, and right now we’ve got plenty. Energy prices spiking past $150 a barrel could drag us to 5,400. Yet history says death crosses aren’t always doomsday.

The Full Picture starts with the charts. On April 7, S&P closed at 6,616.85, testing the 200-day MA around 6,644.

Late March saw the 50-day at 6,783cross under the 200-day at 6,644. This bearish signal hit amid Q1 bloodbath: market breadth tanked, with under 50% of stocks above their 200-day averages.

Sixteen industry groups in correction, four in bear territory. Energy surged 34% in Q1, hiding the rot elsewhere. RSI at 46.2% shows no oversold bounce, just meh conviction.

Geopolitics lit the fuse: Iran tensions sparked oil volatility, jacking CPI. Fed’s in a bind; hike now and crush growth, or hold and let inflation roar. Goldman flags 5,400 if oil stays hot.

History tempers the panic. Since 1950, death crosses mix it up: great in downtrends, meh standalone. This one’s backed by deteriorating breadth, making it scarier.

Early April snap-back stalled below key MAs. No volume to punch through 6,644. Algorithms could dump if mid-April fails the test.

Contrarian buzz from a weekly golden cross on April 8: 50-week over 200-week, screaming long-term bull. Trading above psych levels in Goldilocks land, inflation at 2%, Fed soft-landed.

Year-end bulls eye 6,500, dream of 7,000. But daily death cross screams caution till 6,783 flips.

Why It Hits Home for the everyday American investor. Your 401(k) took a 5% haircut from January highs. Retirees watching nest eggs shrink amid grocery bills up from oil wars.

This isn’t abstract chart voodoo. It’s real: cooling consumer spending, margins squeezed by input costs. Big Tech’s AI hype must deliver, or breadth stays broken.

Financial sector flashing spooky signals, down 10.7% YTD, correlation to S&P dipping. Banks know lending risks when recession whispers grow louder.

What Smart Investors Are Watching

1. 200-Day MA Hold at 6,644. Index testing this line now; break below opens 6,500 floor, then Fibonacci hell at 6,170. Bulls need reclaim to kill death cross narrative.

2. Oil Shock Escalation. Middle East flares could lock crude over $150, forcing Fed hikes and Goldman’s 5,400 nightmare. Energy masks weakness; watch if it cracks too.

3. Earnings Season Verdict. Q1 reports key: can firms hold margins vs. rising costs? Consumer slowdown signs would ignite systematic selling from algos.

4. Weekly Golden Cross Momentum. Rare bull signal eyes 6,500 year-end. If daily aligns, FOMO shifts cash to tech ETFs; ignore at peril if death cross dominates.

Story in Action: Meet Tom Reynolds, 58-year-old retiree from Ohio. Built his portfolio on S&P ETFs through the 2020s bull, dreaming of Florida golf without worry.

Death cross hit, his account dipped 7%. Oil jacked his gas bill 40%, echoing portfolio pain. He trimmed tech, piled into energy, slept better as sector soared 34%.

Now eyeing golden cross whispers, Tom’s torn: double down or stay defensive? Smart money diversifies value, energy amid ‘show-me’ mode.

What’s your move as S&P dances on this knife edge? Will you bet on bull revival or brace for bear mauling?

Logo

Sometimes, colleagues of Day of Investment share special offers with us that we think our readers should be made aware of. Chris Vance You are receiving this email because you expressed interest in financial and investment-related updates. This content is for educational purposes only and is not investment advice. Investing involves risk. Some links may be promotional and help keep this newsletter free. Day of Investment is a product of Platoon Marketing, LLC. 

If you need assistance or have any questions, our support team is available 24/7 at support@dayofinvestment.com. 

Privacy Policy | Unsubscribe© 2026 Day of Investment. All rights reserved.
74 E Glenwood Ave Smyrna, DE 19977. This email was sent to pahovis@aol.com. If you no longer wish to receive these emails you may unsubscribe at any time: https://pages.trackifyemail.com/UnsubscribePage.html?mkt_unsubscribe=1&mkt_tok=OTA0LVJNUC01MjgAAAGhFfD3TE-fCwJr5UI_x7Z_maneS-QGu4ODF6NLEgGsrrSmZDQDiKhbYS_ayeWIo1ndlQgnSF3PWsVm2-lNCvLWvuHIfuWc4LEiD6tDEEg5pzy5

Gas Price Hike Lifts This Ticker

Unsubscribe here

TradeWins Logo

Three Hot Stocks to Buy and Hold as the Weather Warms Up

It’s time to start investing in oversold travel stocks, especially as we move into the warmer months of the year when demand for vacations and leisure activities pick up. Historically, around this time of the year, we see interest in companies tied to travel and tourism, as consumers begin planning trips, book hotels, cruises, and other experiences.…Read More


Gas Price Hike Lifts This Ticker

Everyone is feeling the pinch at the pump and there isn’t relief on the horizon. That wallet squeeze is creating some solid upward momentum in one ticker in particular as consumers look everywhere they can to offset the dent in their monthly budget.…Read More


This Ticker Is Taking Off

Boeing (BA) is attempting a short-term bounce after a sharp downtrend from its February highs, but the broader structure still favors sellers. Price remains well below prior support levels, now acting as resistance, indicating continued bearish pressure.…Read More


Big news!

We’ve selected you for complimentary VIP Access!

Go here to accept your invite. Once you accept the invite, we’ll text you a link to a breakthrough trading report called…“The A.I. Investing Guide”

Inside this report, you’ll discover the top AI stocks as selected by our in-house trading experts. And why right now there’s a rare window of opportunity for fast-acting investors.


© 2026 Tradewins Publishing. All rights reserved. | Disclaimer | Privacy Policy | Terms and Conditions | Contact Us

© 2025 Tradewins Publishing. All rights reserved. | Disclaimer () | Privacy Policy () | Terms and Conditions () | Contact Us () NOTICE: Auto-trading, or any broker or advisor-directed type of trading, is not supported or endorsed by TradeWins Publishing. The information provided by TradeWins in its various materials, including trading recommendations, newsletters and educational publications is not customized or personalized for any particular person or risk profile. Past results are not necessarily indicative of future results. Results presented can vary and may not be typical for all subscribers. There are substantial risks involved with investing in the stock and options market, including the risk of total loss. You should only trade or invest “risk capital” – funds you can afford to lose.This email was sent to pahovis@aol.comby kimwaller@tradewins.com

TradeWins Publishing Corp. 528 North Country Rd., St. James, NY 11780

1-Click Unsubscribe | Edit Profile | Manage Subscriptions | Report Spam

93% win rate – this dividend approach ignores market chaos

Gold Bitcoin tokens float around the Strategy logo, underscoring its renewed push to buy more digital assets.

Dear Reader,

Wall Street is on edge…

The war in Iran is already driving cost of goods up and the stock market down.

Most investors are going to be caught off guard with what is on the horizon.

But here’s the truth: You don’t have to gamble on what happens next.

For the last 16 years, my Dividend Machine has been quietly pumping out life-changing gains — no matter who sits in the White House, no matter what the market is doing.

In fact, since 2009, The Dividend Machine has delivered a total return of 7056.47%.

Just imagine, a $10,000 stake would be worth more than $700,000 today, and $100,000 would be worth over $7 million!

And while Wall Street was panicking during crashes, my readers kept cashing steady dividend checks. Month after month. Year after year.

With a 93%-win rate since launch, this is like betting on a horse race where you already know who’s going to win.

The best part?

In President Trump’s new “Great American Turnaround” economy, dividend stocks are set to explode again — that’s why I’ve put together a FREE report that shows you exactly how to profit from Trump’s turnaround tailwinds.

See how you can grow richer with The Dividend Machine Here and Claim Your Free Report.

Sincerely,

Bill Spetrino


Friday’s Exclusive News

Could Easing Iran Tensions Trigger an Amazon Pre-Earnings Rally?

Author: Sam Quirke. Published: 4/6/2026. 

Amazon logo on smartphone screen with rising stock chart background, symbolizing e-commerce growth and market gains.

Key Points

  • Amazon has been virtually flat for 18 months, with shares still trading around $210 amid macro headwinds and AI spending concerns.
  • However, if oil prices were to drop, it would relieve pressure on both tech valuations and consumer spending, setting up a potential pre-earnings rally.
  • Analysts remain bullish on AMZN, with over 40% of upside targeted, but the move depends on macro stabilization aligning with a strong earnings report.
  • Special Report: The Biggest IPO Ever: Claim Your Stake Today

Tech giant Amazon.com (NASDAQ: AMZN) has been one of the more frustrating large-cap stocks to watch and to own in recent months. Shares of the Seattle-based company are currently trading around $210, roughly the same level as in November 2024 — meaning the stock has effectively gone nowhere in 18 months despite a stronger broader market backdrop. For context, the S&P 500 has gained about 10% over the same period, even after the index’s recent pullback.

Expectations of a marked turnaround in 2026 had been high for the company’s place among the “Magnificent Seven”. Instead, the underperformance has persisted: AMZN fell as much as 20% around its February earnings and remained lower in the two months that followed. More recently, the war in Iran has added fresh headwinds, pushing oil higher and reigniting concerns about inflation, consumer spending and tech valuations.

America’s Last Birthday (Ad)

Whitney Tilson – the Wall Street analyst who called the 2000 dot-com collapse and appeared on an Emmy-winning 60 Minutes segment covering the 2008 financial crisis – is issuing what he calls his most urgent warning yet.

Tilson says the next six months will bring extreme change for millions of Americans, and he’s outlined specific steps to protect your money – moves he believes could outperform stocks, bonds, and gold.Access Tilson’s full preparation plan here, free of charge

What makes the current setup especially tricky is how quickly the narrative can shift. Markets are reacting not only to events on the ground but to changing expectations about how and when the conflict might de-escalate, with sentiment swinging sharply on each new signal — from social-media posts to official statements.

If tensions do start to ease, that could trigger a sizable retracement in oil prices and a subsequent cooling of inflation worries. Easing those headwinds would be the kind of tailwind Amazon needs as it heads into its next earnings report in a few weeks.

Let’s take a closer look at what that could mean and how it might play out.

Why the Macro Background Matters More Than Usual

The surge in oil prices since the conflict began on Feb. 28 has had a broad, meaningful impact. Higher energy costs feed directly into inflation expectations, which in turn pressure interest rates and compress valuation multiples, particularly for tech stocks like Amazon.

For the e-commerce and cloud computing provider, the impact isn’t limited to multiples. Elevated fuel costs also erode consumers’ budgets, reducing discretionary spending and creating a second layer of pressure on Amazon’s core e-commerce business. That dual effect makes the situation particularly nuanced for the company.

If tensions ease and oil prices begin to retrace, those twin pressures could unwind at the same time — a potent combination for bulls to consider.

A Pre-Earnings Move Could Be Sizeable

The setup is more interesting given that Amazon is expected to report earnings on April 23. With the stock having absorbed substantial negative sentiment in 2026 and trading roughly 10% below where it began the year, consensus expectations are likely lower than usual. That said, aside from the company’s miss in its last report, Amazon had beaten analyst expectations for 11 consecutive quarters through Q1 2023.

Analyst support remains strong. Wells Fargo recently reiterated a Buy rating and raised its price target to $305, implying more than 40% upside from current levels. That follows a steady string of bullish updates in March and reinforces the view that Amazon’s long-term story remains intact despite near-term pressures. If geopolitical tensions ease, that creates an attractive risk-reward heading into earnings.

Much of the confidence comes from what analysts see beneath the surface. Wells Fargo named Amazon its top internet pick for 2026, citing improving cloud momentum and signs that recent investments may be translating into returns. If that narrative holds, the stock won’t need a perfect earnings print — just confirmation that the business is moving in the right direction.

The Risk Is Still Considerable

The obvious risk is that the macro backdrop does not cooperate. If oil stays elevated or rises further, inflation concerns are unlikely to abate, which would continue to pressure both Amazon’s valuation multiples and consumers’ discretionary spending. That would make the environment more challenging heading into fiscal Q1 results, especially given scrutiny over Amazon’s rising capital expenditures (CapEx).

Amazon’s push into artificial intelligence (AI) remains central to the investment thesis, but it also contributes to uncertainty. The scale of CapEx required for AI has raised questions about near-term profitability, and investors will look closely for any signs of an emerging payoff in the coming report.

If those signs are absent and macro conditions remain difficult, the stock could struggle to escape its recent range regardless of broader sentiment. Promisingly, Amazon trades at a trailing 12-month price-to-earnings ratio of 29.26, and analysts expect earnings to grow nearly 18% over the next year.


This Month’s Bonus Story

$330M Bitcoin Binge: When Others Pause, Strategy Pounces

Reported by Jeffrey Neal Johnson. First Published: 4/9/2026. 

Key Points

  • The recent acquisition of digital assets reinforces Strategy’s standing as a leading institutional player in the rapidly evolving crypto ecosystem.
  • Strategic capital management through innovative preferred stock offerings enables continued treasury expansion without immediate share dilution.
  • Management continues to position the corporate treasury to anticipate predictable market scarcity events and maximize long-term value for all shareholders.
  • Special Report: The Biggest IPO Ever: Claim Your Stake Today

In a market wrestling with indecision and reacting to every geopolitical headline, Strategy (NASDAQ: MSTR) has chosen to act with resounding clarity.

Strategy, a pioneer in integrating Bitcoin (BTC) into its corporate identity, has decisively re-entered the market, acquiring an additional 4,871 bitcoins for roughly $329.9 million. The purchase was executed as Bitcoin’s price hovered around the pivotal $69,000 mark — a level watched closely by traders worldwide.

For Strategy, this was not a moment for hesitation but for calculated action. More than a line item on Strategy’s balance sheet, it is a direct reaffirmation of the company’s core mission.

America’s Last Birthday (Ad)

Whitney Tilson – the Wall Street analyst who called the 2000 dot-com collapse and appeared on an Emmy-winning 60 Minutes segment covering the 2008 financial crisis – is issuing what he calls his most urgent warning yet.

Tilson says the next six months will bring extreme change for millions of Americans, and he’s outlined specific steps to protect your money – moves he believes could outperform stocks, bonds, and gold.Access Tilson’s full preparation plan here, free of charge

While market volatility has prompted many to wait and see, Strategy’s leadership demonstrated contrarian conviction, viewing the current climate as an opportunity to bolster its already massive treasury. Investors gauging institutional sentiment could view this decisive return to accumulation as a powerful bull signal, offering a clear window into Strategy’s long-term vision.

Inside Strategy’s Latest Treasury Move

To grasp the full weight of Strategy’s commitment, the details of its latest acquisition matter. This was not a speculative, one-off purchase but the continuation of a disciplined plan to methodically increase its holdings. The precision of the operation underscores the seriousness of the company’s approach.

The data paints a picture of renewed buying pressure:

  • Execution Window: The 4,871 bitcoins were acquired over five days, from April 1 to April 5, 2026.
  • Average Price: Strategy paid an average of $67,718 per coin, inclusive of all fees and expenses.
  • A Fortified Treasury: This latest infusion brings Strategy’s total Bitcoin holdings to 766,970 coins.

This treasury — among the largest held by any publicly traded company — was assembled with an aggregate investment of $58.02 billion. That total underscores that Strategy’s approach is not short-term trading but long-term, disciplined accumulation of what it considers a superior store of value. Each purchase is another brick in a digital fortress, built on conviction that looks well beyond today’s price charts.

Intelligent Leverage: How Strategy Creates Shareholder Value

A key question for investors is why Strategy’s stock often trades at a premium to the direct market value of its Bitcoin.

That premium to net asset value (NAV) is not an anomaly; it reflects Strategy’s unique structure and the additional value it provides beyond simply holding coins. Investors are buying exposure to a dynamic operating company with a sophisticated financial engine.

That engine is powered by two complementary capital-raising tools. First, an adaptable At-The-Market (ATM) program that issues shares efficiently to fund operations and acquisitions. Second, its Series A Perpetual Stretch Preferred Stock, which attracts income-seeking investors with an 11.5% annual dividend. Together, these provide a significant capital pipeline for buying Bitcoin without immediately diluting common stock.

This intelligent use of capital is the core of the Strategy Advantage and explains its premium valuation. The market is buying a package that includes:

  1. Leveraged Bitcoin Exposure: By using funds from debt and preferred stock, any appreciation in Bitcoin’s price is amplified for Strategy common stockholders.
  2. A Functioning Business: An established enterprise software business provides an operational backbone and an additional revenue stream from the tech sector.
  3. A Regulated and Simple On-Ramp: Strategy serves as a trusted, liquid, and accessible vehicle for gaining Bitcoin exposure within a standard brokerage account.

With over $49 billion in combined remaining capacity from its stock offerings, Strategy has a long runway to continue executing this plan, signaling that its growth phase is far from over.

Positioning for Bitcoin’s Next Big Catalyst

Strategy’s recent buying spree is not happening in isolation. It is a forward-looking move positioned ahead of the next programmed event in the Bitcoin ecosystem: the 2028 halving.

The halving, which occurs roughly every four years, cuts the reward for mining new blocks in half and reduces the issuance of new bitcoin. That creates a supply shock: less new supply entering the market makes the existing supply relatively scarcer.

Historically, halvings have preceded significant bullish price cycles as steady or rising demand meets shrinking issuance. By accumulating aggressively now, Strategy increases its stake ahead of this predictable scarcity event, positioning its treasury to benefit from any subsequent market repricing.

Moreover, Strategy’s transparent accumulation has ripple effects across the financial world. As a publicly traded entity, its steady purchases serve as a blueprint and confidence signal for other corporate treasurers and institutional investors. Each major buy helps normalize Bitcoin as a reserve asset, contributing to market maturation and broader adoption. In that sense, Strategy is not just investing in Bitcoin; it is helping shape the narrative around its future acceptance.

A Clear Signal in a Complex Market

Ultimately, Strategy’s decision to inject another $330 million into Bitcoin is an unambiguous statement of confidence from a management team with a long-term plan.

That action provides investors with a tangible data point amid daily market noise, reaffirming the company’s commitment to its pioneering approach.

The firm’s ability to raise capital and leverage its corporate structure creates the distinct Strategy Advantage — a vehicle designed to offer more than passive exposure to a digital asset.

It represents an active, leveraged bet on Bitcoin’s future appreciation, managed by a team that has staked its corporate identity on the outcome. For investors who share that bullish conviction and want a regulated, liquid way to amplify exposure, Strategy continues to make a compelling and strategically coherent case for consideration.

This email communication is a sponsored email provided by Newsmax, a third-party advertiser of MarketBeat. Why did I receive this email message?. 

If you need assistance with your account, please don’t hesitate to email MarketBeat’s South Dakota based support team at contact@marketbeat.com.

If you would no longer like to receive promotional emails from MarketBeat advertisers, you can unsubscribe or manage your mailing preferences here.

© 2006-2026 MarketBeat Media, LLC. 
345 N Reid Place, Sixth Floor, Sioux Falls, South Dakota 57103. U.S.A..

Today’s Bonus Content: Is Trump Done? Shocking leak…(From Banyan Hill Publishing)

New Nvidia stock prediction

The AI spending spree should continue this year. That could boost shares of Nvidia and other tech stocks.

The AI Profit Predictor just signaled a big move for NVDA – by using predictive artificial intelligence.

Simply go here for details – and see how it works.

Five American companies are at the forefront of the AI revolution. This includes Amazon, Microsoft, Google, Meta and Oracle. These “hyperscalers” are investing to build out data centers across the country.

Together, these companies are expected to spend $700 billion in 2026.

It’s important to understand that this is not the end of the AI spending cycle. It’s just the start.

Total spending could reach $8 trillion by the end of the decade, according to Blackrock.

Nvidia stock will continue to be one of the biggest winners. Shares of NVDA are trading below recent 52-week high. The recent pullback provides a nice entry point to scoop up shares.

So, how high could Nvidia stock go in 2026?

My new AI Profit Predictor is signaling a big move.

Simply go here for details and get the next trade.

Ian Wyatt

© Wyatt Investment Research. All rights reserved. Wyatt Investment Research is not a broker dealer of financial advisor. This content is for informational purposes. Nothing in this email should be considered investment advice. Every investment has risk and you could lose your investment. You can review terms of use and disclosures by clicking here.

Click here to manage your emails from Wyatt Investment Research

Update your email preferences or unsubscribe here

65 Railroad St
Richmond, Vermont 05477, United StatesPowered by beehiivTerms of Service 

Don’t forget your free report!

Unsubscribe

Hi there,

A few hours ago, you requested to receive a free copy of MarketBeat’s latest report, “Analysts Agree—These Gold Picks Outshine the Rest.”

I noticed that you hadn’t opened the email we sent with your free report, so I just wanted to follow up and make sure you received it.

If you missed the initial message, you can access your free report directly by clicking the link below:

Download your report here (PDF).

If you have any trouble accessing the report, please don’t hesitate to reach out to our support team by replying to this message.

Thanks,

Jessica Mitacek
Managing Editor
MarketBeat


Further Reading from MarketBeat Media

The Arms Race Has Gone Airborne: What Investors Need to Know 

Written by Bridget Bennett. Date Posted: 4/6/2026. 

Draganfly and Palladyne AI logos with drone swarm over cityscape, highlighting DPRO and PDYN defense AI partnership.

Key Points

  • Draganfly and Palladyne AI recently completed a SwarmOS integration milestone that enables decentralized autonomous drone swarming for U.S. defense applications.
  • Edge AI is transforming drone warfare by allowing drones to operate independently without internet connectivity, making GPS denial and signal jamming far less effective as countermeasures.
  • The drone defense sector is entering a policy-driven super cycle, with 2027 expected to be the breakout year for meaningful revenue scale across the industry.
  • Special Report: Elon Musk: This Could Turn $100 into $100,000

The next stage of drone warfare isn’t coming — it’s already here. And the investment implications are bigger than most investors realize.

Cameron Chell, CEO and Executive Chairman of Draganfly (NASDAQ:DPRO), has spent more than 25 years building drone systems for military, public safety, and commercial applications. His view on where the industry stands right now is blunt: if your offensive or defensive systems aren’t deploying autonomous, AI-enabled drones today, they’re already outdated.

Iran War Shakes Up Wall Street, Here’s How to Profit… (Ad)

Since 2009, the Dividend Machine has posted a total return of 7,056.47% – turning a $10,000 stake into more than $700,000 while the broader market struggled through multiple downturns.

With a 93% win rate since launch, this dividend-focused strategy has kept investors cashing steady checks through every crash. Bill Spetrino has released a free report outlining how to position for income no matter what the market does next.Claim your free report and see how the Dividend Machine works

That’s the thesis behind a defense-sectorsupercycle — and it’s driven not by consumer demand or hype but by geopolitics.

Edge AI Turns Drones Into Independent Decision-Makers

The concept accelerating this shift is edge AI — putting computing power directly on the drone so it can process data, make decisions, and execute missions without relying on an internet connection or cloud infrastructure. Chell says even Draganfly’s least expensive drones have compute capacity comparable to NVIDIA‘s chips.

That matters because connectivity has always been the weak link. Early countermeasures against small drones focused on jamming GPS or severing the radio-frequency link between the drone and its operator.

Edge AI removes that vulnerability. A drone with onboard intelligence can navigate by visual recognition, assess changing conditions like terrain or weather, and even abort a mission autonomously if circumstances change.

The implications extend beyond the battlefield, but it’s defense applications that are drawing the most capital right now.

Swarm Technology Changes the Math on Defense

The economics of modern drone warfare have flipped the traditional cost equation. Instead of firing a single missile system that costs millions at a target, an attacker can deploy dozens or hundreds of inexpensive drones to overwhelm defenses at a fraction of the price. No existing surface-to-air system can currently handle 50 or 500 drones arriving simultaneously, regardless of how expensive that system is.

Draganfly is building toward that future through its partnership with Palladyne AI (NASDAQ:PDYN). In late March, the two companies announced a successful SwarmOS integration milestone, completing a flight simulation that validated decentralized autonomous swarming across Draganfly’s drone platforms.

Unlike traditional swarm systems that rely on a single leader drone directing the group, Palladyne’s SwarmOS enables multiple drones within a swarm to act as independent decision-makers — perceiving their environment, collaborating with teammates, and adapting in real time without continuous communication links.

That capability aligns directly with what tier-one defense customers are asking for. Draganfly recently secured a contract to provide Flex FPV drones and training to U.S. Air Force Special Operations Command units. The company also completed an exclusive capabilities demonstration for the Canadian Armed Forces after participating in Canada’s MINERVA working group — an initiative tied to Prime Minister Mark Carney’s new Defense Industrial Strategy emphasizing sovereign drone capabilities.

A Policy-Driven Super Cycle With a Long Runway

Chell calls this a policy-driven supercycle, and the distinction matters. This isn’t demand generated by consumers or a tech fad. National-security priorities are forcing governments to pour money into drone capabilities because the cost of inaction risks the security of entire nations.

The conflict in the Middle East has accelerated the timeline dramatically. That region — one of the wealthiest on the planet and home to critical, high-value infrastructure — now needs drone-defense systems immediately. The industry investment forecasts, according to Chell, are about to be exceeded by a wide margin.

For investors trying to time this cycle, the revenue picture is still early. Chell says the industry is just now seeing the leading edge of revenue scaling, with 2027 projected as the breakout year for meaningful top-line growth across the sector. Military procurement cycles that once took years have compressed to one or two, and the first sizable contract awards are starting to land.

Draganfly’s Full Product Line Is the Strategic Bet

What separates Draganfly from many competitors, Chell argues, is its full product line. The company has four drone systems in production and a fifth in development, ranging from five-inch FPV tactical drones to the Outrider — a nine-foot, dual-diesel-engine platform with seven-hour endurance and 100-pound lift capacity. All are designed to be interoperable.

That ecosystem approach matters because real-world operations rarely require just one type of drone. A surveillance mission may need a separate strike drone, a target-acquisition platform, and a logistics-delivery system. Chell says the only other company with a comparable full product line is DJI, which employs roughly 10,000 engineers.

Draganfly is also pursuing vertical integration through acquisitions to secure its supply chain and protect proprietary IP, while maintaining partnerships with sensor providers, software developers, and motor manufacturers across the broader drone ecosystem.

The Commercial Upside Beyond Defense

Defense is pulling capital into the sector now, but Chell draws a parallel to the early internet era that’s worth considering. Two decades ago the internet was replacing the yellow pages; nobody could have imagined what it would become. Chell sees a similar long-term trajectory for drones: they collect data better, communicate better, and deliver goods more efficiently than alternatives.

The transformation of military drone technology into commercial applications could be as economically significant as the internet itself. That’s a bold claim, and it will take time. But the underlying capability — autonomous machines making real-world decisions based on real-world data — has applications across agriculture, infrastructure inspection, logistics, public safety, and beyond.

For now, the investment case is straightforward: global defense budgets are expanding, procurement timelines are compressing, and companies building interoperable, AI-enabled drone ecosystems sit at the front of a multi-year spending wave. Revenue hasn’t fully materialized yet, but the contracts are starting to land.

Thank you for subscribing to MarketBeat!

We empower investors to make better trading decisions by providing up-to-the-minute financial information and unbiased market research.

If you have questions or concerns about your account, please don’t hesitate to email our U.S. based support team at contact@marketbeat.com.

If you would like to unsubscribe or change which emails you receive, you can manage your mailing preferences or unsubscribe from these emails.

© 2006-2026 MarketBeat Media, LLC. All rights reserved.
345 N Reid Place #620, Sioux Falls, S.D. 57103-7078. United States..

Explore 7 Stocks Poised for Magnificence in 2025

Unsubscribe

Hello – 

Your free report is attached: These 7 Stocks Will Be Magnificent in 2026.

Inside, you’ll find seven companies positioned for sustained growth, along with the key metrics that separate long-term winners from short-term momentum plays.

Download your free report here. (PDF)

To your investing success,

Matthew Paulson
MarketBeat

P.S. If you need help accessing this report or using MarketBeat in general, just drop us a note at contact@marketbeat.com. Our South Dakota–based support team is always happy to assist.


This Week’s Featured Article

Alphabet Has Fallen 16% From Its Highs: Panic or Opportunity?

Authored by Ryan Hasson. Article Posted: 3/27/2026. 

Hand holding smartphone displaying Alphabet logo against falling red stock chart, illustrating tech stock correction trend.

Key Points

  • Alphabet has fallen almost 20% from its record high and broken below key $300 support, but the higher-timeframe uptrend remains intact.
  • Fundamentals have rarely been stronger, with Q4 EPS and revenue both beating estimates.
  • Despite the selloff, 46 of 51 analysts rate GOOGL a Buy, with a consensus price target of $367.18, implying nearly 26% upside. 
  • Special Report: Elon Musk: This Could Turn $100 into $100,000

Shares of Alphabet (NASDAQ: GOOGL), last year’s top-performing Magnificent Seven stock, have sold off sharply from their record February high. The stock has now declined by almost 20%, entering correction territory. In late March it broke below the key $300 support level, signaling a potential short-term shift in momentum.

A jury’s March 25 ruling added to the negative sentiment, finding its subsidiary YouTube liable in a social media addiction case and ordering a $3 million payment. That amount is negligible next to a company valued at roughly $3.5 trillion.

America’s Last Birthday (Ad)

Whitney Tilson – the Wall Street analyst who called the 2000 dot-com collapse and appeared on an Emmy-winning 60 Minutes segment covering the 2008 financial crisis – is issuing what he calls his most urgent warning yet.

Tilson says the next six months will bring extreme change for millions of Americans, and he’s outlined specific steps to protect your money – moves he believes could outperform stocks, bonds, and gold.Access Tilson’s full preparation plan here, free of charge

With the stock in correction territory, investors may reasonably ask: is this a time to sell, or a buying opportunity for patient investors?

Correction Territory, But the Higher Timeframe Trend Remains Intact

Technically, this appears to be a pullback within a broader, higher-timeframe uptrend. On the weekly chart the stock remains in a firm uptrend, and the current decline represents the first major pullback and retest since the breakout in July of last year.

Now that the stock is below $300, the next potential support area is around $280, where Alphabet spent several weeks consolidating in November. If the correction accelerates along with broader market weakness, the most critical support zone would be the 200-day Simple Moving Average (SMA), currently near $260. That level would be a meaningful, lower-risk area to watch for signs of stabilization and possible re-entry.

The Fundamentals Have Rarely Been Stronger

If the technical picture calls for patience, the fundamentals provide conviction. Just over a month ago, Alphabet reported its Q4 and full-year 2025 results, and the numbers were strong across the board. For the third consecutive quarter the company beat both earnings and revenue expectations and surpassed $400 billion in annual revenue for the first time.

Earnings per share (EPS) came in at $2.82 versus a $2.59 consensus estimate. Revenue reached $113.83 billion, topping forecasts of $111.43 billion. For the full year Alphabet generated $402.8 billion in revenue and $10.81 in EPS, representing year-over-year growth of 17% and 34%, respectively.

Google Cloud remains the standout growth driver. Fourth-quarter cloud revenue was $17.66 billion, up 48% year over year and well above estimates. On an annualized basis, Google Cloud has passed a $70 billion revenue run rate. Cloud backlog surged 55% quarter over quarter to $240 billion from $155 billion the prior quarter, providing strong forward visibility.

The core advertising business also remains resilient. Search revenue rose 17% year over year in Q4, suggesting AI-related disruption has not materially dented Google’s primary revenue engine. YouTube generated more than $60 billion in combined advertising and subscription revenue in 2025, and Alphabet now reports 325 million paid consumer subscriptions across its platforms. On the AI front, Gemini surpassed 750 million monthly active users, with over 10 billion tokens processed per minute through direct API usage, signaling rapid enterprise and developer adoption.

Analysts and Institutions Aren’t Worried

Despite the selloff, Wall Street sentimenttoward the tech giant remains broadly bullish. Of 51 analysts covering the stock, 46 rate it a Buy, producing a consensus Moderate Buy. The consensus price target of $367.18 implies nearly 26% upside from current levels — a move that would take the stock to new all-time highs.

Institutional flows tell a similar story. Over the past 12 months, about $164 billionflowed into the stock versus $82 billion in outflows, a net inflow of roughly $82 billion that reflects sustained confidence in Alphabet’s execution, fundamentals and long-term positioning.

Thank you for subscribing to MarketBeat!

MarketBeat empowers investors to make better financial decisions by delivering up-to-the-minute financial information and independent investment research.

If you have questions about your account, please email MarketBeat’s U.S. based support team at contact@marketbeat.com.

If you would like to unsubscribe or change which emails you receive, you can manage your mailing preferences or unsubscribe from these emails.

© 2006-2026 MarketBeat Media, LLC. All rights reserved.
345 North Reid Place #620, Sioux Falls, SD 57103-7078. United States..

Expert who predicted the 2008 collapse warns of another crisis!

editor-imageURGENT: Secure Your Savings With One Simple “Switch”Read More dividerDuring and after the Grеat Fіnanϲіaⅼ Crisis of 2008, 485 U.S. ᖯanks went under.
We warned about 484 — an accuracy ratе of 99.8%

Nοw, I have a nеw warning.

But this time, it’s not just about a few hundred ᖯanks.

It’s about nearly every single ᖯank in America, whether large or smaⅼⅼ.

A veritable ᖯanking nightmare!

See what it is hеrе.

Good luck and God bless!

Open In Inbox For Best ViewMartin D. Weiss, PhD
Weiss Ratings Founder
dividerEconomic Brief: Savings Behavior Gains Attention in 2026 Outlook

New commentary from market observers suggests that households are placing renewed emphasis on savings strategies as economic forecasts highlight moderate growth and evolving cost trends. Many individuals are reviewing financial routines and adjusting timelines to maintain stability. 

Frequently discussed planning considerations include: 

• Increasing emergency reserve targets
• Reviewing automatic contribution levels
• Monitoring interest rate developments
• Rebalancing long-term allocations
• Evaluating income diversification options 

Analysts note that gradual adjustments and consistent reviews may help maintain flexibility. Rather than making large changes, many households are focusing on structured planning and incremental improvements. 

Educational resources continue to highlight diversification, liquidity awareness, and long-term consistency as core elements of financial planning. Balanced information can support more thoughtful decision-making over time. 

Read the Full Financial Outlook >> 

Updates like this are shared to provide general awareness of evolving economic conditions and long-term planning considerations.

IconWhat’s your priority right now?Reply to this email and tell us what you’re most interested in.Just pick a topic below or mention something specific.Investing NewsLatest NewsStock MarketEconomySend ANSWERS dividerOnce in a while, Future Profit Journey associates present us with unique opportunities that we think are worth sharing with our readers. The above is one such opportunity that we recommend you consider.Future Profit Journey sending this newsletter on behalf of Prestige Publishing LLC.200 Continental Dr Suite 401, Newark, DE 19713 

For any personalized assistance or questions, simply reply to this email for a swift resolution. Contact us at support@FutureProfitJourney.com for other concerns. 

© 2026 Copyright Future Profit Journey. All rights reserved. 

Thinking about unsubscribing? We hope not! But, if you must, the link is below.Privacy PolicyTerms & ConditionsUnsubscribeAbout-Us