The Complicated Reality Behind High Gas Prices


Read Online  |  May 6, 2026  |  E-Paper  | 🎧 Listen

“Impatience is a great obstacle to success.”

— Napoleon Bonaparte
Ivan Pentchoukov
National Editor

Good morning! It’s Wednesday. Here are today’s top stories:

  • The United States gets almost no oil via the Strait of Hormuz, which has been choked off by Iran. So why did gas prices go up? The reality is complicated.
  • Companies that legally sell recreational marijuana to adults are being sued in Illinois and Connecticut for allegedly not warning customers of the possible health problems caused by the drug.
  • Secretary of State Marco Rubio said that China’s human rights violations remain a key concern for the Trump administration and will be on the agenda during the president’s upcoming visit to Beijing.
  • The United States, with its Gulf partners, is proposing a United Nations Security Council resolution to reopen the Strait of Hormuz.
  • 🍵 Health: Learn about the dangers of seed oils and discover a recipe for healthy homemade mayonnaise. 
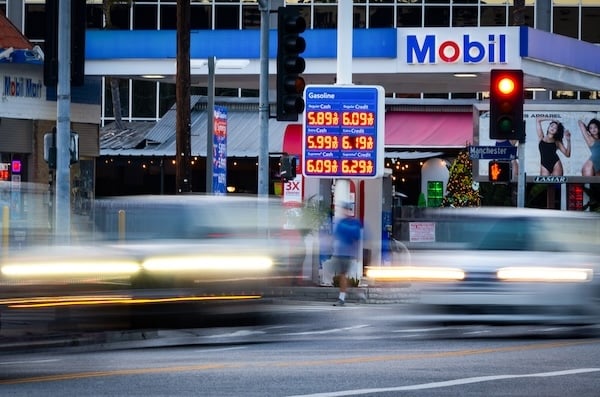
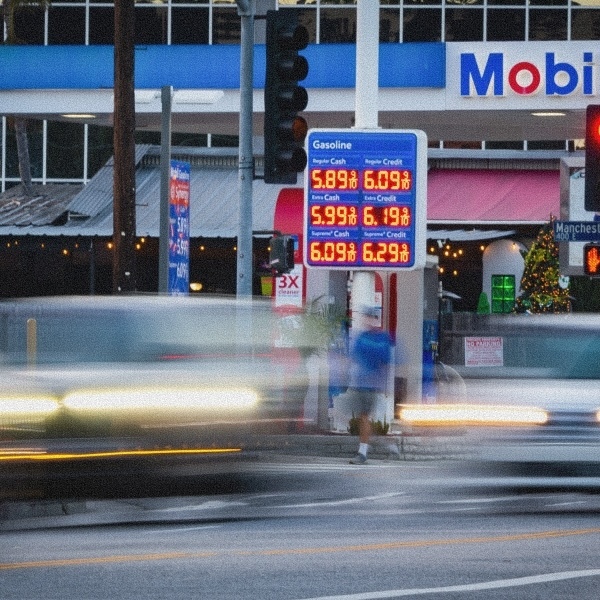
Traffic moves past a gas station in Los Angeles on March 11, 2026. (John Fredricks/The Epoch Times)

The Complicated Reality Behind High Gas Prices

Average gas prices in the United States have gone up by almost 40 percent since March 1. The reason appears straightforward: Iran has blocked the Strait of Hormuz in response to the U.S. military operation that decapitated its regime and degraded its military. Hundreds of tankers trapped behind the strait cannot deliver their oil, depriving the world of 7 percent to 10 percent of its supply.

Although that explains drastic price increases and even shortages in Europe and Asia, the United States gets almost no oil through the strait. In theory, the country should be energy-independent, as it is a net petroleum exporter.

But in reality, the United States is highly intertwined with the global oil market, and there is little chance it could disentangle itself from it, according to experts who spoke to The Epoch Times.

“Oil is a fungible commodity that can be shipped anywhere in the world, and that is why everyone is impacted by the events,” said Patrick De Haan, petroleum analyst with gas price tracker GasBuddy.

Countries facing shortages are willing to pay top dollar for U.S. oil.

“There’s huge demand to export the product,“ said Paul Sankey, an oil market analyst and president of Sankey Research. “So that draws the prices up.”


If the U.S. government were to impose limits on oil exports, it would likely cause more problems than it would solve, the experts said. (More)

POLL
(Olena Yakobchuk/shutterstock)

AI Power or AI Risk?

A public clash between Elon Musk and Sam Altman has intensified debate over artificial intelligence—its reliability, its control, and whether rapid development is outpacing safeguards. As AI systems become more integrated into daily life, we invite you to share your views.


The results will be featured in an article published this Saturday. (Take the Survey)

POLITICS

  • Several Republican state senators who opposed a redistricting plan backed by President Donald Trump lost primary election challenges on May 5 to candidates endorsed by the president.
  • Seeking to make a return to the U.S. Senate, former Sen. Sherrod Brown (D-Ohio) decisively defeated Ron Kincaid in the Democratic primary. Sen. Jon Husted (R-Ohio), who was unopposed in the GOP primary, will meet Brown in the Nov. 3 midterm election to fill the remaining two years of the Senate term vacated by Vice President JD Vance.
  • Former presidential candidate Vivek Ramaswamy glided to victory in the Ohio GOP primary election for governor, solidifying the predicted Nov. 3 General Election showdown between him and the uncontested Democratic nominee, Dr. Amy Acton.
  • Democrat Chedrick Greene defeated Republican Jason Tunney in a special election for the state Senate’s District 35 seat, preserving Democratic controlof the chamber.

LATEST NEWS

  • U.S. exports climbed to a record high, driven by surging shipments of crude oil and other petroleum products during the first month of the war in Iran, new government data released on May 5 show.
  • The trial of a Chinese American man charged with helping China’s communist regime track down dissidents from an overseas police station in New York starts today.
  • The Dell Technologies board of directors approved changing the company’s state of incorporation from Delaware to Texas, which could make it the latest high-profile company to exit Delaware since a state judge canceled Elon Musk’s pay package in 2024.
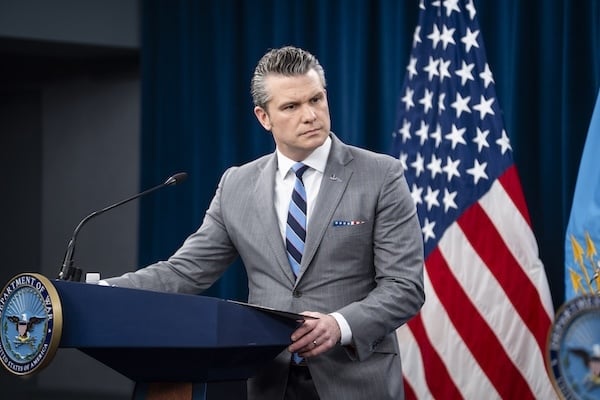
Secretary of War Pete Hegseth during a press briefing at the Pentagon in Arlington, Va., on April 24, 2026. (Madalina Kilroy/The Epoch Times)

WORLD

  • War Secretary Pete Hegseth said on May 5 that the ceasefire with Iran remains in force despite events in the Persian Gulf in recent days. At a Pentagon briefing, Chairman of the Joint Chiefs of Staff Gen. Dan Caine said a series of Iranian attacks were below the threshold of “major combat operations.”
  • President Donald Trump announced that he was briefly pausing Project Freedom, the mission of assisting commercial ships through the Strait of Hormuz, to give the Iranian regime time to finalize a deal.
  • Iran’s Foreign Minister Abbas Araghchi is in Beijing for talks with his Chinese counterpart Wang Yi.
  • More than three years after China ended its draconian pandemic controls, some Chinese citizens say they are still suffering from serious health problems they believe began after receiving domestically produced COVID-19 vaccines. Several individuals also say they have seen a rise in deaths among younger people from sudden heart attacks or strokes. Chinese authorities have not acknowledged a broader vaccine injury issue. But an analyst who recently spoke to The Epoch Times said the lack of answers—and lack of support—has turned fear into anger.
  • An explosion at a fireworks factory in central China has claimed at least 26 lives, local authorities said on Tuesday, prompting the regime’s top leader to call for a speedy investigation into the cause.


OPINION: The Car You Own May Soon Decide If You’re Allowed to Drive It—by Mollie Engelhart (Read)
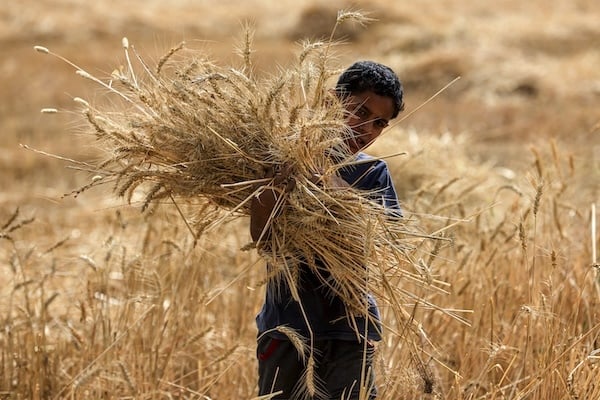
A boy walks with collected ears of wheat during the harvest season in the Marajah village of the Mishkhab District, north of Iraq’s central city of Najaf, on May 5, 2026. (Ahmad Al-Rubaye / AFP via Getty Images)

📸 Day in Photos: Cruise Ship Crew Members Evacuated, Transport Strike, and Battle Reenactment (Look)

🎙️ Podcast: Chinese Man Arrested, Sentenced to Prison for Trying to Smuggle 2,200 Ants Out of Kenya—Facts Matter(Listen)

💛 Inspiration: Tajik dances are often steeped in hidden meaning, with movements conveying narratives about daily life, natural phenomena, or deeply held beliefs. (Watch)

🎵 Music: Mozart – Andante And Allegretto (Listen)

👁️ (Sponsored) Still Using Eye Drops? 5 Reasons They’re Not Solving Your Dry Eye Problem — Eye drops may offer temporary relief, but they don’t always address the root cause. Discover 5 overlooked reasons symptoms return*—and the simple shift people are making for longer-lasting comfort.

HEALTH
(Terri Ward/The Epoch Times)

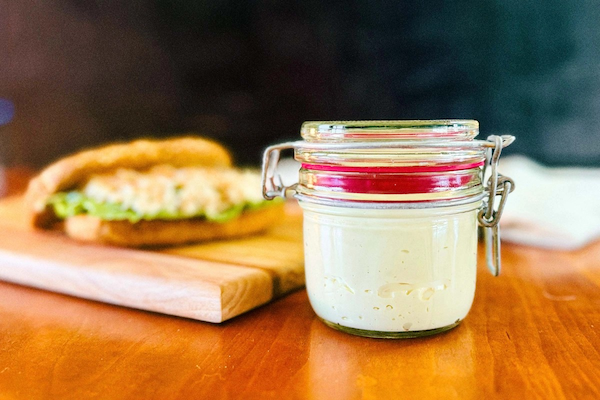
Homemade Mayonnaise Without Seed Oils–Plus an Herbed Variation 

First developed in 1756, mayonnaise began as a simple emulsion of egg, acid, and olive oil. Today, it has become one of the biggest delivery vehicles for refined seed oils in the American diet—even when the front label says, “Made with olive oil.” Turn that jar around, and you’ll often see soybean oil, canola oil, or both in the ingredient list alongside olive oil.

Seed oils are highly processed vegetable oils extracted from seeds such as soybeans, canola, corn, sunflower, safflower, grapeseed, rice bran, and cottonseed. These oils are high in omega‑6 fatty acids, including linoleic acid. While the body needs some omega‑6, modern diets deliver far more than we’re designed to handle, often crowding out anti‑inflammatory omega‑3 fatty acids.

In modern diets, seed oils are nearly everywhere, from restaurant frying oil to packaged snacks, salad dressings, and many “healthy” foods. Seed oils undergo heavy chemical refining, and in restaurants, they are often heated to high temperatures and reheated repeatedly. When seed oils are overheated and reheated, they break down, forming harmful compounds, including oxidized fats and toxic aldehydes. These damaged molecules can increase oxidative stress and place a burden on the body.

Constant exposure to seed oils has pushed the omega-6 to omega-3 ratio from our ancestral ratio of about one-to-one to as high as 15-to-one to 20-to-one today.


Some research suggests that replacing other fats—mostly saturated fats—does not raise inflammation markers. However, these studies usually tested seed oils in controlled settings with relatively low overall seed oil intake. They did not examine the ultra‑processed, fried‑food‑heavy pattern many people follow day to day. More recent research links a higher omega-6-to-omega-3 ratio to an increased risk of death from all causes. (More)
Today's Recipe

🎲 Games

Spot the Difference is our readers’ favorite. Play it here.
Play Spot the Difference

Play more games at Epoch Fun ➞

Play Word Wipe
Play Sweet Shuffle
Play Freecell
Play Blossom Word
Play Today’s Hurdle
Play Hidden Object

♥️ Support our mission and donate.

🎧 Prefer to listen? Get the Morning Brief podcast.

💬 Feedback? Reply to this email or write to ivanmb@epochtimes.nyc

👋 New to Morning Brief? Subscribe.

💡 Got a news tip? Connect with us confidentially.

▶️ Follow The Epoch Times on Facebook, X, Instagram, or Truth Social

📫 Forward this email to a friend and tell them to subscribe. (Here)

☕ Show us your love with coffee, mugs, stickers, and clothes. Check out the shop.

💼 Own a business? Reach millions of engaged readers by advertising in our newsletters.

Thanks for reading 🙏

Have a wonderful day!

—Ivan Pentchoukov, Madalina Hubert, and Kenzi Li.

Copyright © 2026 The Epoch Times, All rights reserved. 

Our mailing address is: The Epoch Times, 129 West 29th Street, Fl 8, New York, NY 10001 | Contact Us


Our Morning Brief newsletter is one of the best ways to catch up with the news. Manage your email preferences here or unsubscribe from Morning Brief here.

*Disclaimer: The opinions expressed in this advertisement are exclusively those of the advertiser and do not represent our views or positions. This material is promotional in nature and should not be mistaken for news, research or editorial content.

🎧 The Complicated Reality Behind High Gas Prices


May 6, 2026  |  Read Online  |  Send Feedback

Good morning. Here’s your Wednesday playlist:

Morning Brief

MORNING BRIEF

The Complicated Reality Behind High Gas Prices

🎧 Listen on Apple Podcasts

What could make your listening experience better? Send us a line at podcasts@epochtimes.us

New to our newsletter? Subscribe here to listen to our reporters on the ground. 

Prefer a different podcast platform? Pick one here.

🎙️ MORE PODCASTS

The nation’s pressing topics deciphered by our journalists from the podcast desk.

FACTS MATTER

Chinese Man Arrested, Sentenced to Prison for Trying to Smuggle 2,200 Ants Out of Kenya

In several previous episodes we exposed cases of Chinese nationals being apprehended at U.S. airports trying to smuggle in a variety of suspicious biological material: roundworms, E. coli bacteria samples, as well as a type of fungus that can be used to decimate food crops.   🎧 Listen →   

THE REPORT

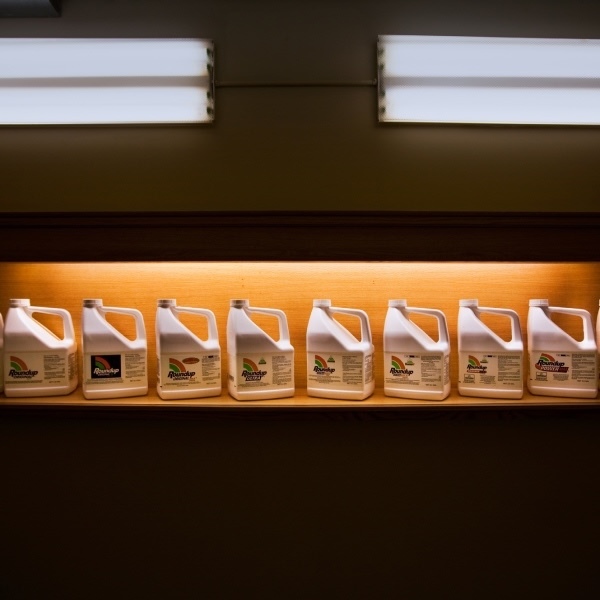
Monsanto Weed Killer Case Could Upend Billions in Compensation

The court must decide whether the EPA’s position that glyphosate needs no cancer warning shields companies from state lawsuits.   🎧 Listen →   

Thanks for tuning in!

Today’s newsletter was put together by Ivan Pentchoukov, Lina Skorbach and Kenzi Li. Send them your feedback at podcasts@epochtimes.us.

📅 Podcast Schedule:

☝ Click on the links above to pick your favorite podcast platform.

Did someone forward this newsletter to you? Subscribe here.

Copyright © 2026 The Epoch Times, All rights reserved. 

Our mailing address is: The Epoch Times, 129 West 29th Street, Fl 8, New York, NY 10001 | Contact Us

The Audio Room newsletter is one of the best ways to receive the most up-to-date information. Manage your email preferences here or unsubscribe from The Audio Room here.

The Year We Stopped Trusting Our Eyes

AI Scams

The Year We Stopped Trusting 

Our Eyes

Why AI-powered deception is the defining consumer threat of 2026 

and what’s being done about it

The New Normal

Three years ago, an online scam still came with tells. The grammar was off. The logo was stretched. The “Nigerian prince” had a pixelated cousin in your inbox who couldn’t quite spell “urgent.” If you slowed down, you could spot it.

That window has closed.

In April 2026, the U.S. Department of Justice announced the coordinated takedown of nine scam centers and at least 276 arrests across Dubai, Thailand, and the U.S., charging operators of so-called “pig-butchering” rings that had drained millions from American victims. The defendants weren’t lone hackers in basements. 

They ran companies — “Ko Thet,” “Sanduo Group,” “Giant Company” — with managers, recruiters, scripts, and AI tooling that let a handful of people operate at the scale of a call centre staffed by hundreds.

According to TIME’s reporting in early April, what’s emerging is what one United Nations investigator called a “perfect storm”: cheap generative AI, advanced malware, and a sluggish global economy combining to produce industrial-scale fraud that’s “much more sophisticated than it was three years ago.” The same syndicates that ran illicit Chinese gambling rings before COVID converted shuttered casinos along the Mekong into compounds, then upgraded the technology. Now they’re reinvesting profits into better AI, faster malware, and broader targeting.

The scale numbers are sobering. The Global Anti-Scam Alliance found that 57% of adults globally were victims of a scam in the past year, with 23% losing money. Javelin Strategy & Research pegged combined U.S. identity fraud and scam losses at $38 billion in 2025 — and that figure was actually down from 2024, not because the threat is shrinking but because the nature of fraud is shifting toward harder-to-quantify trust erosion. The FBI’s IC3 logged $16.6 billion in cybercrime losses in 2024 alone, up 33% year-over-year.

And the volume of synthetic content fuelling all this? Cybersecurity firm DeepStrike estimates online deepfakes jumped from roughly 500,000 in 2023 to about 8 million in 2025. A 16x increase in two years.

Here’s the part that matters for everyone reading this: 74% of people surveyed said they were confident they could spot a scam. Most of them are wrong. The signals we all learned to look for — typos, weird URLs, strange phrasing — have been engineered out of the product.

What This Actually Looks Like in Your Inbox

The textbook examples from the last 12 months tell the story better than any statistic.

The fake recruiter. UK cybercrime reports of recruitment scams more than doubled between 2022 and 2024. Lloyds Banking Group logged a 237% rise in job scams in just eight months of 2025. Monzo says more than 10,000 of its customers fell victim to recruitment scams last year alone. The playbook: an AI-cloned LinkedIn profile of a real recruiter, outreach personalized using the target’s own CV, and a pitch polished enough that even sceptical professionals are biting. One Guardian reporter wrote about being fooled herself — during maternity leave, when she was tired and not paying close attention. She lost an hour and her pride. Others have lost their savings.

The fake candidate. The flip side is just as ugly. Background-screening firm Checkr says 23% of companies have already encountered identity fraud among new hires. Gartner is forecasting that by 2028, one in four job candidate profiles globally will be fake. Amazon disclosed in late 2025 that it had blocked more than 1,800 suspected North Korean state-affiliated applicants since April 2024 — with attempts growing 27% quarter over quarter. Ferrari was targeted by a deepfake WhatsApp impersonation of its CEO. Voice security firm Pindrop interviewed a candidate whose facial expressions were slightly out of sync with his voice and traced the IP address halfway around the world.

Pushpaganda. This month, threat intelligence team HUMAN unmasked a campaign that hijacked Google’s Discover feed using AI-generated fake news stories to drive users to scareware sites that pushed browser notifications and ad fraud. At its peak, 240 million bid requests across 113 domains in seven days. Google has since patched it. Others will be coming.

Pig-butchering at scale. The DOJ’s San Diego indictments last week describe scammers using fake romance and friendship — cultivated over weeks or months — to push victims into fake crypto investment platforms, encouraging them to borrow from family and take out loans. The scammers showed off their own “returns.” Once victims transferred funds, the money was gone. Operation Level Up, an FBI initiative that started in 2024, has notified almost 9,000 victims and saved an estimated $562 million as of April 2026. That’s just one program in one country.

The common thread: AI didn’t invent any of these scams. It just made them cheaper, faster, more personalized, and far harder to detect. As one fraud expert put it, detection is now a behavioural problem, not a grammar problem.

What Private Industry is Doing

This is where the most interesting work is happening, because the businesses most exposed to AI fraud — banks, hiring platforms, social media companies, payment processors — have economic incentives to solve it that regulators don’t.

A short list of what’s emerging:

  • Real-time deepfake detection built into video conferencing and hiring platforms, designed to flag lip-sync inconsistencies, lighting anomalies, and voice-face desynchronization in live calls.
  • Behavioural biometrics that analyze how a user types, moves a mouse, or holds a phone — patterns that are extraordinarily hard to fake even with advanced AI.
  • Privacy-preserving identity verification that lets a person prove they’re real, of legal age, and who they say they are without handing over a stack of personal documents to every counterparty. This is the space where solutions like cryptographic age and identity verification are starting to scale.
  • Content provenance and watermarking standards (C2PA, content credentials) that let cameras, editing software, and AI generators tag content with verifiable metadata about how it was created.
  • Cross-platform fraud signal sharing between banks, telcos, and platforms — quietly, because of the regulatory complications, but increasingly aggressively.

What links these is a recognition that detection alone won’t win. Generation quality is improving faster than detection tools can keep up. Gartner predicts that by 2026, 30% of enterprises will find standalone identity verification unreliable in isolation. The industry is converging on a layered model — detection plus behavioural analytics plus identity verification plus provenance — because no single layer is going to be enough on its own.

What We Are Looking At

Hydaway Digital is a North Vancouver–based GPU compute and AI detection company that, in the span of roughly four months, has gone from a single-client GPU rental pilot to a multi-tenant SaaS platform with a deepfake detection product live in production. 

At a moment when both compute scarcity and synthetic-media fraud are hitting their structural inflection points. Hydaway deserves a serious look.

Company: 

Tickers:

Headquarters:

Sector/Industry:

Recent Share price:

52 week range:

Market Cap:

Shares Outstanding:

1 year return:

Beta:

Recent Financing:

Hydaway Digital

TSXV:HIDE – OTCQB:HIDDF – FSE:C88

North Vancouver, British Columbia

Technology/AI Infrastructure & Software

C$0.60

C$0.21-C$1.03

C$72.09 million

35.93 million

+604%

-1.65

C$1.2M private placement at C$0.25 (Feb 2026); units include 1-yr warrants at C$0.40 with $0.75 acceleration trigger

What Hydaway has actually done — the news flow

This isn’t a story about a company “exploring opportunities.” Hydaway has delivered a string of concrete operational milestones in roughly 16 weeks:

  • February 4, 2026 — Closed the acquisition of RealityChek, a multi-modal AI detection and content verification platform with blockchain-anchored authentication. Consideration: 6,000,000 shares at a deemed price of $0.14 (total $840,000), plus up to 1.86 million milestone shares tied to platform performance.
  • February 5, 2026 — Closed a $1.2 million private placement at $0.25 per unit (each unit including a one-year warrant at $0.40, with acceleration if shares trade above $0.75 for five consecutive days).
  • March 9, 2026 — Completed the technical integration of RealityChek’s AI detection models onto Hydaway’s GPU infrastructure, materially accelerating RealityChek’s ability to train and deploy detection models.
  • March 16, 2026 — Transitioned the GPU compute platform from a single-client pilot to a multi-tenant SaaS model with three tiers (Starter, Growth, Enterprise). API-first deployment, real-time telemetry, dedicated SLAs, predictable subscription revenue.
  • March 18, 2026 — Launched DETECT by RealityChek, a public-facing AI image and URL detection product live at detect.realitychek.com, powered by Hydaway’s GPUs.
  • April 23, 2026 — Integrated Cardlogx’s AI-powered card detection and image analysis system onto Hydaway’s GPU infrastructure. Cardlogx serves the $100 billion trading card industry with eBay/Shopify sales sync, scanning, pricing, inventory, and analytics. CEO Karl Kottmeier explicitly framed this as a “clear template for onboarding enterprise clients with demanding real-time workloads,” with focus shifting to “commercial expansion.”

That’s a coherent operational arc: build the compute, close an acquisition that creates a software flywheel, integrate, productize, then onboard enterprise clients. Each step de-risks the next. And the most recent step — the Cardlogx onboarding — demonstrates that the multi-tenant SaaS architecture works as advertised.

Two AI tailwinds, one company

Most small-cap AI plays are exposed to one side of the AI economy: either the picks-and-shovels (compute, data centers) or the application layer (specific AI products). Hydaway is exposed to both through a single integrated stack. The GPU rental business sells compute capacity into the broader AI buildout. RealityChek consumes that compute to deliver a high-margin SaaS detection product — and is itself a customer of Hydaway’s compute. Every dollar of detection revenue effectively monetizes Hydaway’s GPUs twice: once at the infrastructure layer, once at the application layer.


Check out Hydaway hereVisit our site!

Sources:

Section I — The new normal

DOJ takedown: 276 arrests, nine scam centers, Dubai/Thailand/China/U.S./Meta cooperation, Ko Thet/Sanduo/Giant companies, April 29, 2026 announcement

“Perfect storm” framing; UN investigator quote; Mekong compounds; AI/malware/sluggish-economy combination

Global scam victimization stats: 57% of adults victims, 23% lost money, 73% confident, 46,000-respondent survey across 42 countries

$38 billion combined U.S. identity fraud + scam losses in 2025; “down from 2024” but masking worsening risk

FBI IC3: $16.6 billion in cybercrime losses in 2024, +33% YoY

  • FBI Internet Crime Complaint Center (IC3)2024 Internet Crime Report. https://www.ic3.gov/AnnualReport/Reports/2024_IC3Report.pdf
  • Note: At the time of writing, the FBI had also referenced a separate $20+ billion cybercrime loss figure for 2025, cited in Cybernews coverage. If you want to use the more recent number, that’s available — let me know.

Online deepfakes: 500K in 2023 → 8M in 2025 (16x growth)

  • DeepStrike cybersecurity estimates, cited across multiple secondary sources including industry reports compiled in: https://bayelsawatch.com/deepfake-statistics/
  • Caveat: This is widely cited but the original DeepStrike methodology is not always linked. For a fact-checked publication, you may want to sub in the Mordor Intelligence “Fake Image Detection Market” data — which puts the market at $1.42B in 2025 growing to $7.43B by 2031 (31.73% CAGR) — as a more rigorously sourced anchor for “the volume of synthetic content is exploding.” https://www.mordorintelligence.com/industry-reports/fake-image-detection-market

Section II — What this looks like in your inbox

UK recruitment scams more than doubled (2022–2024); Lloyds 237% rise (Jan–Aug 2025); Monzo 10,000+ victims

Checkr: 23% of companies have encountered identity fraud among new hires

  • Checkr, employer survey data (cited in Guardian and other 2025–2026 hiring-fraud coverage).

Gartner: by 2028, 1 in 4 job candidate profiles will be fake

  • Gartner, public forecast widely cited in HR and security press through 2025–2026. Original Gartner research note: “Predicts 2025: How AI Will Reshape Identity and Hiring.”

Amazon: 1,800+ suspected DPRK applicants blocked since April 2024; 27% QoQ growth

Ferrari deepfake WhatsApp CEO impersonation

  • Widely reported in 2024; original coverage in Bloomberg and The Guardian. (Note: this is a frequently cited “exemplar” anecdote — not central to the data argument but useful as illustration.)

Pindrop voice/face desync candidate detection anecdote

  • Pindrop company commentary; cited in 2026 voice-biometrics and hiring-fraud coverage.

Pushpaganda campaign: HUMAN Satori, 240M bid requests, 113 domains, seven-day peak, Google Discover feed exploitation, AI-generated articles, expansion from India to US/UK/Canada/Australia/South Africa

Operation Level Up: ~9,000 victims notified, $562 million saved (as of April 2026)

  • U.S. Department of Justice April 29, 2026 release (same as DOJ takedown source above).
  • FBI Operation Level Up program description (initiated January 2024).

Section V — What private industry is doing

Real-time deepfake detection vendors (Pindrop, Reality Defender)

  • Company materials and 2025–2026 industry coverage.

Behavioural biometrics, content provenance (C2PA), cross-platform fraud signal sharing

  • General industry consensus. C2PA (Coalition for Content Provenance and Authenticity)standards: https://c2pa.org

Gartner: by 2026, 30% of enterprises will find standalone identity verification unreliable

  • Gartner, “Predicts 2024: Identity-First Security.” (Widely cited in identity-verification industry press.)

KYC fraud / synthetic identity attempts up 2,137% in three years; deepfakes now 6.5% of all fraud

  • Mordor Intelligence, Fake Image Detection report (cited above).

This source list compiled May 5, 2026. URLs verified as of that date. For any republication, sources should be re-verified — particularly the DOJ release URL and any market-sizing reports that may have been updated.

Disclaimer — Editorial Content

This article concerns Hydaway Digital Corp. (TSXV: HIDE) (OTCQB: HIDDF) (FSE: C88) and is published by NewsAMP Media Corp. (“NewsAMP,” “we,” “us,” or “our”) for general informational and educational purposes only. This is not paid promotional content. NewsAMP has not been compensated by Hydaway Digital Corp., its affiliates, or any third party to produce or distribute this communication. NewsAMP does not hold any shares, options, warrants, or other securities of Hydaway Digital Corp., and has not received securities of any kind as consideration for this content.

Readers should nevertheless be aware of the following relationship and affiliation disclosures: Any common ownership, directors, officers, employees, contractors or principals shared between NewsAMP Media Corp. and Hydaway Digital Corp. or its subsidiaries, including but not limited to RealityChek. One or more principals of NewsAMP Media Corp. also hold roles at Hydaway Digital Corp. and/or its subsidiaries, which represents a material conflict of interest. Readers should treat this article accordingly. These relationships, where they exist, represent a material conflict of interest that may affect the objectivity of the content even in the absence of monetary compensation.

NOT INVESTMENT ADVICE

NewsAMP Media Corp. is not registered or licensed by any governing body in any jurisdiction to provide investment advice or make investment recommendations. NewsAMP is not a registered investment adviser, exempt market dealer, broker-dealer, securities dealer, financial planner, or investment professional. Nothing in this article constitutes, or should be construed as, investment, financial, legal, tax, or accounting advice, or a recommendation to buy, sell, or hold any security or other financial instrument. The information provided is general and impersonal, and is not tailored to any particular reader’s investment objectives, financial situation, risk tolerance, or particular needs.

Always do your own research and consult with a licensed investment professional before making any investment decision. This communication should not be used as the basis for making any investment.

NO OFFER OR SOLICITATION

This communication is not, and should not be construed to be, an offer to sell or a solicitation of an offer to buy any security in any jurisdiction. The content is not directed at, and is not intended for distribution to or use by, any person in any jurisdiction where such distribution or use would be contrary to applicable law.

SOURCE OF INFORMATION

The information in this article is collected from public sources, including but not limited to the profiled company’s website, news releases, continuous disclosure filings on SEDAR+, third-party news outlets, and publicly available market data. While we make reasonable efforts to ensure accuracy at the time of publication, NewsAMP makes no representations or warranties regarding the accuracy, completeness, timeliness, or reliability of any information contained in this article. The information is not independently verified beyond review of the public sources cited, and may become inaccurate or outdated after publication. NewsAMP undertakes no obligation to update this article.

You should assume all information in this article requires independent verification, and you are encouraged to review the company’s continuous disclosure filings on SEDAR+ (https://www.sedarplus.ca) before making any investment decision.

FORWARD-LOOKING STATEMENTS

This article may contain “forward-looking statements” or “forward-looking information” within the meaning of applicable Canadian and U.S. securities laws. These include statements about future events, business plans, financial performance, market conditions, regulatory developments, and similar matters. Forward-looking statements are based on assumptions that may prove incorrect and are subject to known and unknown risks, uncertainties, and other factors that may cause actual results to differ materially from those expressed or implied. NewsAMP undertakes no obligation to update forward-looking statements. Readers should review the relevant issuer’s continuous disclosure filings on SEDAR+ for a full discussion of risk factors.

RISK OF INVESTING

Investing in securities is inherently risky. Investing in small-cap, micro-cap, and early-stage issuers — including securities listed on the TSX Venture Exchange and the Canadian Securities Exchange — involves a high degree of risk, including the risk of total loss of capital. Securities of such issuers may be illiquid, highly volatile, and unsuitable for many investors. Past performance is not indicative of future results. You should only invest money you can afford to lose entirely, and only after consulting a registered investment professional licensed in your jurisdiction.

NO ENDORSEMENT

The publication of this article does not constitute an endorsement of Hydaway Digital Corp. or its securities by NewsAMP Media Corp. Any opinions expressed are those of the author at the time of writing and do not necessarily reflect the views of NewsAMP Media Corp.

INDEMNIFICATION / RELEASE OF LIABILITY

By reading this article, you acknowledge that you have read and understood this disclaimer in full, and you agree and accept that NewsAMP provides no warranty in respect of this communication or the profiled company and accepts no liability whatsoever. To the greatest extent permitted under applicable law, you release and hold harmless NewsAMP Media Corp., its affiliates, assigns, and successors from any and all liability, damages, injury, and adverse consequences arising from your use of or reliance on this communication. You further agree that you are solely responsible for any financial outcome related to or arising from your investment decisions.

INTELLECTUAL PROPERTY

All trademarks used in this communication are the property of their respective trademark holders. Other than NewsAMP.ca and any other trademarks owned by NewsAMP Media Corp., NewsAMP is not affiliated with, connected to, or endorsed by, the trademark holders unless otherwise stated.

GOVERNING LAW

This disclaimer is governed by the laws of the Province of British Columbia and the federal laws of Canada applicable therein. Use of NewsAMP’s services is also subject to our Terms and Conditions (https://newsamp.ca/page/terms-and-conditions) and Privacy Policy (https://newsamp.ca/page/privacy-policy).

CONTACT

Email: info@newsamp.ca

Phone: 778-549-1838

Copyright (C) 2026 NewsAmp Media Corp. All rights reserved.
You are receiving this email because you opted in via our website.

Our mailing address is:
NewsAmp Media Corp 704-595 Howe St PO Box 35 Vancouver, BC V6C 2T5 Canada

View in browser | Update your preferences| Unsubscribe

UFC Champ Ilia Topuria Joins Gutfeld!

FOX News Streaming on FOX One
Ilia Topuria on Gutfeld!

UFC CHAMPION ILIA TOPURIA ON GUTFELD!

From his rise to the top of the UFC to what fans can expect next, the reigning UFC Lightweight Champion steps into the spotlight ahead of the highly anticipated Freedom 250 White House fight.

START STREAMING

Facebook
Instagram
X
TikTok
FOX One

   Follow Us:

Do you have a question? Click here to visit our Help Center. 
Please do not reply to this message. 

Unsubscribe | Manage Preferences | Terms of Use | Privacy Policy

™ and © 2026 Fox Media LLC. All rights reserved. 

Fox Digital Services LLC | PO Box 900, Beverly Hills, CA 90213-0900

SpaceX IPO Confirmed: Claim Your Stake Today

 SystemTradingClear, systematic insights and strategic market analysis to inform confident investing decisions.SpaceX IPO Confirmed: Claim Your Stake Today – Ad

Elon Musk is about to take SpaceX public in what’s set to be the biggest IPO ever. But there’s no need to wait for the company to go public. You can claim your stake today. The New York Times predicted it “will unleash gushers of cash for Silicon Valley and Wall Street.” Continue Reading ➔Joby Aviation, Celestica, Snap, Rambus, And Nvidia: Why These 5 Stocks Are On Investors’ Radars Today

U.S. stocks finished Monday on a mixed note, with the Dow Jones Industrial Average slipping 0.1% to 49,167.79. Continue Reading ➔Discover 3 Stocks Projected to Dethrone Nvidia (NVDA) – Ad

Futurist and Stock Analyst, Eric Fry, published a brand-new research report naming three outsider stocks have the power to completely disrupt the “seemingly invincible” Mag 7. For the time being, this research report is available through this page – at no charge. Get your free copy right here.US attempt to open Strait of Hormuz tests fragile Iran war ceasefire

DUBAI, United Arab Emirates (AP) — The Iran war risked reigniting after the the Strait of Hormuz for commercial shipping, though a seemed to be holding Tuesday even after the United Arab Emirates said Iran fired missiles and drones at it. Continue Reading ➔Top 3 Health Care Stocks That Could Lead To Your Biggest Gains This Month

Oversold stocks in health care sector present buying opportunity. RSI compares stock’s strength on up/down days & predicts short-term performance. Top oversold stocks: KNSA (28) NNOX (28.2) RNA (28.4). Continue Reading ➔He Called Nvidia in 2016. Here’s His Next Call. – Ad

Today, Louis Navellier says a new AI computer called “Golden Dawn” – 283 trillion times more powerful than today’s data centers – is about to create the same kind of opportunity. He’s identified the one little-known company best positioned to profit, and he’s revealing it – down to the ticker – before May 5. Watch his free presentation now.A humanoid robot sprints to victory in Beijing, beating the human half-marathon world record

BEIJING (AP) — A humanoid robot that won a for robots in Beijing on Sunday ran faster than the human world record in a show of China’s technological leaps.  Continue Reading ➔Federal Reserve faces unorthodox leadership change: Warsh enters, Powell remains

WASHINGTON (AP) — President Trump’s pick to lead the Federal Reserve, , has said he wants to bring “regime change” to the central bank, but if confirmed by the Senate he will find a Fed already transformed by the . Continue Reading ➔Insiders Are Buying These 6 Stocks Aggressively – Ad

Follow the smart money. This report reveals stocks seeing strong insider buying-often a signal of confidence and potential upside. Discover where executives are investing their own capital and which companies could be positioned for moves the market hasn’t priced in yet. 

Access the Report HereBy clicking the link above you will automatically opt-in to receive emails from FinStrategist and agree to Privacy PolicyFord’s 2,200 HP All-Electric Mustang Just Blitzed Past Previous Quarter-Mile Record

Ford’s racing division sets record for the fastest electric car on quarter-mile track with 2,200 hp Mustang. Continue Reading ➔Rekor Systems Shares Jump On New Contract, Strong Momentum

Rekor Systems stock rises after $16.8M Oklahoma deal, strong momentum, and upcoming earnings on May 11.Continue Reading ➔SpaceX ‘Dark Energy’ Replaces Foreign Oil – Ad

For years, we’ve been told SpaceX is a rocket company. But according to new satellite images from 300 miles above the Earth’s surface, there is something very strange going on at SpaceX right now that has nothing to do with space. It could soon replace our need for foreign oil forever and ignite a $10 trillion boom for the stocks involved. Learn more.Amazon’s Next Gold Mine Is Worth $1.3 Trillion: Transport Stocks Begin Paying For It

BofA’s Justin Post says Amazon Supply Chain Services opens a $1.3 trillion logistics TAM. Each 1% share = $13B in revenue. Transports stay under pressure. Continue Reading ➔Scaramucci: Trump Is Trying To Sink Vance Because ‘Trump Wants To Be the Last Republican President’

Anthony Scaramucci says that President Trump’s battles with Pope Leo XIV are intended to box in Vice President Vance by turning Vance’s Catholic identity into a political vulnerability. Continue Reading ➔Strait of Hormuz Closed Again, Iran Says ‘Under the Strict Management and Control of the Armed Forces’

Iran’s military announced that the strait had “returned to its previous state” and “is under the strict management and control of the Armed Forces.” Continue Reading ➔Wall Street’s Most Accurate Analysts Give Their Take On 3 Industrials Stocks With Over 4% Dividend Yields

Investors turn to dividend-yielding stocks for stability in turbulent markets. Benzinga provides latest analyst ratings and news for high-yielding stocks in the industrials sector. Continue Reading ➔Zelenskyy slams Russia’s ‘utter cynicism’ as strikes kill 5 in Ukraine before brief truce takes hold

KYIV, Ukraine (AP) — Russian drone and missile strikes targeting Ukraine’s power grid during the night killed at least five people and wounded 39 others, Ukrainian authorities said Tuesday. Continue Reading ➔Jim Cramer Calls RTX A ‘Monster’ Right Here, Aurora A ‘Worthy’ Spec

Cramer recommends buying RTX stock. Aurora, he added, is a worthy spec: “I’m not sure when they can ever make any money…” Continue Reading ➔

Information, charts, or examples contained in this email are for illustration and educational purposes only and not for individualized investment management. This message contains commercial elements, such as advertising and partner offers for which we may receive affiliate compensation. We only send these offers to those who have opted into our newsletter.

If you wish to no longer receive these offers, click on the unsubscribe link at the bottom of this email. Past performance is not indicative of future results. For these reasons, we strongly suggest trading in a DEMO/Simulated account.

The information provided by us is for educational and informational purposes only. We make no representations or warranties concerning the products, practices, or procedures of any company or entity mentioned or recommended in this email and have not determined if the statements and opinions of the advertiser are accurate, correct, or truthful.

If you use, act upon, or make decisions in reliance on information contained in this email or any external source linked within it, you do so at your own peril and agree to hold us, our officers, directors, shareholders, affiliates, and agents without fault.

2967 Dundas St. W. #990, Toronto, ON M6P 1Z2 | Phone Number: 917.672.7040

© 2026 Musth | SystemTrading | All rights reserved. 
UNSUBSCRIBE

5 Mega-Caps Top Q1 2026 Earnings, Still Climbing

DividendStocks.com Newsletter

Unsubscribe

Nobody Understands Why Trump Is Invading Iran (here’s the answer) (From Banyan Hill Publishing)


5 Mega-Cap Stocks That Beat Q1 2026 Earnings and Are Still Climbing

Written by Ryan Hasson on May 4, 2026 

Conceptual illustration of a digital cloud connected to a city skyline by glowing data streams.

Key Points

  • Alphabet, Amazon, Apple, Qualcomm, and Caterpillar all reported Q1 2026 earnings beats, with cloud, AI, and services growth driving results well above consensus estimates.
  • AI infrastructure demand emerged as a common thread, with Google Cloud up 63%, AWS up 28%, and Caterpillar’s power generation revenue surging 41% on data center orders.
  • Caterpillar posted its largest earnings beat in five quarters, with a $63 billion backlog up 79% year over year, prompting significant price target increases from Morgan Stanley and JPMorgan.
  • Special Report: Famous historian sounds alarm on America (From Porter & Company)

This earnings season has delivered a clear message: the companies leading this market are not just holding up in a challenging macro and geopolitical environment, they are accelerating and growing at an impressive pace.

Five of some of the the most closely watched names in the market all reported Q1 2026 results this past week, and all five delivered beats that went well beyond the headline numbers. Alphabet (NASDAQ: GOOGL), Amazon (NASDAQ: AMZN), Apple (NASDAQ: AAPL), Qualcomm (NASDAQ: QCOM), and Caterpillar (NYSE: CAT) each offered something different, but together they paint a picture of a market where the strongest businesses are widening the gap. And for investors looking ahead, the case for continued outperformance across all five remains fairly compelling.

The NASTY TRUTH about the SpaceX IPO (Ad)

In nearly every major IPO, roughly 95% of the gains are captured before retail investors can place a trade. It happened with Facebook, Uber, and Airbnb – hedge funds and underwriting banks buy in cheap, then help set the public opening price.

Dr. Mark Skousen, Macroeconomic Strategist at The Oxford Club, says he has identified a backdoor that lets regular Americans take a pre-IPO position in SpaceX right now. Nearly 15,000 readers have already accessed the details.Click here to see how the SpaceX backdoor works before June

Alphabet: The AI Platform That Keeps Pulling Away

Alphabet delivered what may have been the defining earnings report of the season. Q1 revenue of $109.9 billion grew 22% year over year, the fastest growth rate since 2022. That figure, unsurprisingly, comfortably topped the $107.1 billion consensus. The company’s EPS of $5.11 grew a staggering 82% year over year, which of course, crushed the consensus estimate.

But the headline that mattered most was Google Cloud, which posted $20.03 billion in revenue, up 63% year over year and well above the $18.4 billion estimate. That wasn’t simply just a beat, it was a clear statement from the company. It builds on the impressive acceleration from 48% growth in Q4 2025, and it marked the first time Google Cloud has crossed the $20 billion quarterly threshold.

The cloud backlog nearly doubled quarter over quarter to over $460 billion, a number that suggests the growth runway extends well beyond anything current models reflect.

Management raised its full-year CapEx guidance to $180 billion to $190 billion, a statement of conviction that AI infrastructure demand is accelerating, not plateauing.

From a technical perspective, although the mega-cap stock is up almost 140% over the prior 12 months, it’s still holding up convincingly and yet to extend from key moving averages. Now fresh from a breakout above prior resistance, post-earnings, if the stock can consolidate above $360 it could present a new round of potential long-term entry points,

Amazon: AWS Hits Its Fastest Growth in 4 Years

Amazon delivered arguably its strongest all-around quarter in years. Total revenue of $181.5 billion grew 17% year over year and topped the $177.2 billion consensus. Its EPS of $2.78 nearly doubled the $1.64 analyst estimate.

Similar to GOOGL, the headline for Amazon was AWS, which grew 28% year over year to $37.6 billion, its fastest growth rate in 15 quarters and ahead of the 26% consensus. Operating income hit $23.9 billion, producing a 13.1% margin that CEO Andy Jassy described as the highest in Amazon’s history.

The chips business, comprising Trainium, Graviton, and Nitro, crossed a $20 billion annualized revenue run rate, growing at triple-digit percentages year over year. More tokens were processed through Bedrock in Q1 2026 than in all prior years combined.

Q2 guidance of $194 billion to $199 billion points to continued momentum for the retail and tech giant.

The stock is trading above prior resistance of $260, and similar to GOOGL, if it can consolidate and put in a fresh base above prior resistance, turning into newfound support, the bulls might look for new entry points and continuation to the upside.

Ticker Revealed: Pre-IPO Access to “Next Elon Musk” Company (Ad)

We’ve found The Next Elon Musk… and what we believe to be the next Tesla. 

It’s already racked up $26 billion in government contracts.

Peter Thiel just bet $1 Billion on it.👉 Unlock the ticker now and get it completely free.

Apple: A Record March Quarter Across Nearly Every Metric

Apple delivered its best March quarter in company history, and the numbers made that clear across almost every line of the report. Revenue of $111.2 billion grew 17% year over year, beating the $109.66 billion consensus. EPS of $2.01 grew 22% year over year, setting a new March quarter record. Services revenue hit an all-time high of $30.98 billion, up 16%. iPhone revenue of $56.99 billion grew 22%, another March quarter record, with CEO Tim Cook describing the iPhone 17 lineup as the most popular in the company’s history, achieved despite navigating supply constraints throughout the quarter. Gross margin of 49.3% came in above both guidance and the 48.4% consensus estimate.

The board authorized a fresh $100 billion share buyback and raised the quarterly dividend 4% to 27 cents per share, marking 14 consecutive years of dividend growth. Q3 guidance of 14% to 17% revenue growth crushed the 9.5% analyst estimate by a wide margin.

From a technical point of view, the setup is bullish and constructive. Prior to earnings, the stock had spent almost 5 months consolidating near its 52-week high in a bullish formation.

Post-earnings, the stock retested its 52-week high and failed to clear it, but still closed out the session strong.

If AAPL can consolidate near this breakout point in the days and weeks ahead, it could be the beginning phases of a broader, higher timeframe breakout forming.

Qualcomm: 2 Catalysts in 1 Week, and a Bigger Story Developing

Qualcomm’s week deserves some context. Before the earnings report even arrived, the stock had already surged on a report that the company is partnering with OpenAI and MediaTek to develop next-generation smartphone processors, a potential design win that would represent a significant new revenue stream. The earnings report then added a second catalyst.

Revenue of $10.6 billion and non-GAAP EPS of $2.65 both came in above expectations. The segment worth focusing on was Automotive. QCT Automotive revenue of $1.3 billion grew 38% year over year, crossing a $5 billion annualized run rate for the first time in company history, with management guiding that figure to exceed $6 billion annualized by fiscal year-end. Q3 automotive growth is expected to further accelerate to approximately 50% year over year.

The handset segment faced a cyclical headwind from Chinese OEMs drawing down inventory in response to memory supply pressures, but management was direct: Q3 is the bottom, and sequential growth resumes in Q4. And then there was the disclosure that many on the Street missed. Qualcomm confirmed it expects to ship initial custom silicon to a leading hyperscaler in December, its first concrete data center revenue milestone.

For a company that has long been viewed through a handset lens, the automotive trajectory and the emerging data center opportunity together represent a meaningfully different business than the one many investors have been pricing.

Caterpillar: The Industrial AI Play Nobody Saw Coming

Caterpillar might have been the most unexpected earnings story of the week. Q1 revenue of $17.4 billion grew 22% year over year, well ahead of the $16.5 billion consensus. Adjusted EPS of $5.54 beat the $4.62 estimate by nearly a full dollar, the largest earnings beat in five quarters for the company. But neither of those numbers was the one that stopped analysts in their tracks. That was the backlog: $63 billion, up 79% year over year, with all three major business segments contributing.

Power Generation revenue surged 41%, driven almost entirely by demand for Caterpillar’s large reciprocating engines and turbines from hyperscale data center operators building out AI infrastructure. Construction Industries jumped 38%. Tariff costs of approximately $600 million came in well below the $800 million estimate, protecting margins more than the market had modeled.

The analyst reaction was swift. Morgan Stanley doubled its price target to $915 and upgraded the stock. JPMorgan raised its target to $1,125, calling the print a resounding beat. Management raised its long-term revenue growth target to a 6% to 9% compound annual rate through 2030 and increased its power generation sales target to more than 3x the 2024 baseline by 2030. For investors who had filed Caterpillar away as a cyclical industrial play with limited upside, this quarter likely demanded a rethink. It is quietly becoming one of the most direct and underappreciated beneficiaries of AI infrastructure spending in the entire market.

Read this article online ›

Recommended Stories

MarketBeat All Access is the premier all-in-one stock research solution that helps you identify the best stocks, monitor your portfolio, and keep track of the market.

Did you enjoy this article?

I liked this article.
I did not like this article.

Thank you for subscribing to DividendStocks.com’s daily newsletter for dividend and income investors that covers ex-dividend stocks, new dividend declarations, dividend stock ideas, and the latest market news.

If you have questions or concerns about your account, don’t hesitate to email our U.S. based support team at contact@marketbeat.com.

If you no longer wish to receive email from DividendStocks.com, you can unsubscribe.

Copyright 2006-2026 MarketBeat Media, LLC. All rights reserved.
345 N Reid Place #620, Sioux Falls, South Dakota 57103. U.S.A..

Further Reading: Here’s the BIG PROBLEM with the SpaceX IPO(From The Oxford Club)

🦉 The Night Owl Newsletter for May 5th

UnsubscribeThe #1 stock to buy BEFORE the June S-1 filing (From Behind the Markets)

Shopify’s Valuation Crisis Creates Opportunity in 2026

Written by Thomas Hughes

A Shopify-branded tablet point-of-sale display and green tote bag sit on a retail counter.

The most pressing problem with Shopify (NADAQ: SHOP) stock is its valuation. The stock commands a significant premium, trading at over 120X trailing earnings, but it is well-deserved and prices in a robust outlook. The company self-funds growth, sustains a high-20% growth pace, and points to compounding results in the upcoming year.

Looking ahead, the forward estimates are robust, placing this stock in the low teens by 2035, suggesting a solid upside. In this scenario, Shopify’s stock could rise by 70% or more simply to align with broad market trends, and that’s not counting its emerging position as an AI-powered eCommerce leader.

The company is leaning hard on its 20 years of eCommerce data, using it to power agentic and assistant AI tools internally and for its customers. Internal uses increase productivity and throughput while the client-facing ones enable quick, easy, scalable online business construction, maintenance, client acquisition, sales, and payments. Execs say the advantage puts them in a category of one and expect results to compound in 2026.

Shopify Accelerates Growth in Q1: Guides Hot

Shopify had a robust quarter, which is saying something for a company that has sustained high growth for many years. The Q1 results reflect an acceleration compared to the prior quarter and the prior year, with revenue up 34.3% and outpacing the consensus by 250 basis points (bps). Strength was driven by all geos, merchant sizes, and channels, with gross merchandise volume up 34.7%, monthly recurring revenue up by 16.5%, and strength in both subscriptions and merchant services. Subscriptions were weakest, rising by only 21%, but were compounded by services penetration, which increased by nearly 40%.

Margin was another area of strength, despite the contraction in GAAP results, caused by a non-cash one-off. The company experienced gross margin pressure but navigated the environment well, with gross profit growth trailing revenue growth by only 210 bps, and operational strengths offsetting the difference. Operating income increased by 88% and, equally important, the free cash flow margin was maintained at 15%.

Guidance is a bullish catalyst for this market, though it was insufficient to immediately support the price action after the release. The company forecasts revenue in the high-20% range compared to the consensus 26.75%, with a mid-teens free cash flow margin. Among the sticking points are increased spending, which is cutting into the profitability outlook. The caveat is that investment in operations and AI has been paying off for the business and is likely to continue doing so.

Bullish Analysts Enter Wait-and-See Mode

The analyst response was ultimately bullish for the stock price, although near-term headwinds have emerged. No analyst revisions were issued immediately after the release, but several commentaries were, highlighting slowing growth and increased spending.

The critical detail is that the group of 44 provides a high conviction in the Moderate Buy rating, as there is a 77% Buy-side bias, coverage has been increasing, and the price target trend is positive as of early May. Consensus forecasts a 40% upside relative to critical support targets, with the high-end adding double-digits.

Institutions are a concern for Shopify investors in 2026. The group owns nearly 70% of the stock and has been distributing aggressively, with activity ramping sequentially into Q1 2026. The pace is also high, about $3.5-to-$1, and central to the stock price action over the past few quarters. The good news is that early Q2 activity reverted to accumulation, helping cement the market floor. However, there is a risk that institutions sell into any rally that forms.

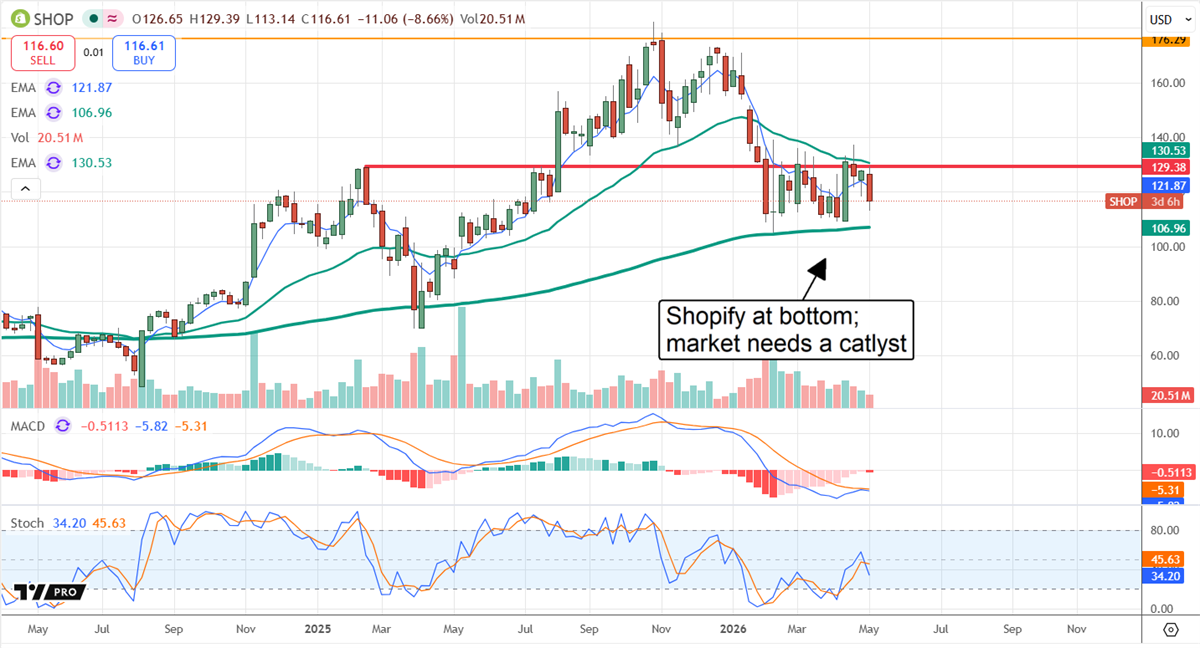
Shopify Stock Is at Rock Bottom in 2026

Shopify stock may struggle to advance until later this year, but it is not expected to fall significantly either. The market shows clear support at the 150-week exponential moving average, a trigger point for long-term buy-and-hold investors, including institutional traders. The likely outcome is that Shopify trends sideways within its existing range, possibly retreating to the $110 level or slightly lower before rebounding within it.

SHOP chart displaying the stock at a bottom and in need of a catalyst.

Catalysts in 2026 include the buyback authorized at the end of FY2025. Worth $1 billion, it underscores management’s confidence in the company’s financial position and has begun providing shareholders with leverage. While incremental, sequential share count reduction will add up over time and help lift this market. Future catalysts include the potential to accelerate returns, such as additional buyback authorization and dividends. Risks include increased competition from names like Amazon (NASDAQ: AMZN) and Mercado Libre (NASDAQ: MELI), which continue to take commerce share in developing and emerging markets. READ THIS STORY ONLINE

Ticker Revealed: Pre-IPO Access to “Next Elon Musk” Company (Ad)

Ticker Revealed: Pre-IPO Access to 'Next Elon Musk' Company

We’ve found The Next Elon Musk… and what we believe to be the next Tesla. 

It’s already racked up $26 billion in government contracts.

Peter Thiel just bet $1 Billion on it.👉 UNLOCK THE TICKER NOW AND GET IT COMPLETELY FREE.

Palantir Drops After a Blowout Q1—What Investors Should Know

Written by Chris Markoch

Palantir Technologies logo displayed against a dark blue background with abstract data network graphics.

Palantir Technologies (NASDAQ: PLTR) delivered a blockbuster Q1 2026 earnings report after the market closed on May 4. But 85% year-over-year (YOY) revenue growth and a Rule of 40 score of 145%, among other highlights, weren’t enough to cheer investors. PLTR dropped 7% the day after the report.

The predictable concern was the company’s valuation. The company delivered earnings per share of 33 cents. That was 5 cents above projections for 28 cents. The number was also 153% higher YOY. On a GAAP basis, the earnings beat was even more impressive. GAAP EPS of 32 cents was 325% higher YOY.

To put that in even more perspective, Palantir chief executive officer, Dr. Alex Karp, made this observation in his letter to shareholders, “Indeed, we generated nearly as much in profit in the first quarter of the year as we did in revenue only twelve months ago.”

This is key to reconciling the PLTR price. Analysts are projecting earnings growth of around 43% in 2026. The company is on pace to do far better than that. But critics of Palantir’s valuation only need to be right once. And at least the day after earnings, momentum was on their side.

Government and Commercial Growth Both Accelerate—A Rare Double

As in the past several quarters, Palantir registered strong growth on both the government and commercial sides of its business. U.S. commercial revenue grew 133% YOY to $595 million, and U.S. government revenue grew 84% YOY to $687 million.

It’s hard to understate the importance of this growth, as Palantir critics often continue to miss the massive growth story that’s occurring on the commercial side of the business. The company was born through its business with the U.S. government, but it’s become much more than that.

As the numbers show, both sides of the business continue to grow and grow strongly. In fact, Palantir raised its full-year outlook for both revenue and earnings. That’s impressive after the quarter it just posted.

Wall Street Is Raising Targets While Burry Shorts the CEO

The real signal for Palantir investors comes from the analyst community. Dan Ives of Wedbush was quick to reiterate its Outperform rating and $230 price target for PLTR. Rosenblatt Securities also reiterated a Buy rating and raised its price target from $200 to $225.

It’s worth noting that some analysts have been lowering their price targets on the stock. But in all cases, it would confirm a range-bound state that has been in place for much of this year. There’s also more news from one of Palantir’s favorite bears, Michael Burry, who says he is now outright shorting PLTR. However, Burry said he’s not just shorting the stock based on valuation, he’s “shorting the business model. I am shorting the entire premise upon which the company rests. I am shorting the CEO.”

This is a continuation of a feud that’s existed between Burry and Karp since the end of 2025 when Burry announced he had taken out put options against PLTR. The stock is down over 20% in 2026, and institutional selling outpaced buying in the first quarter. Some would say that proves Burry right. Others would reference a broken clock.

Is Palantir Being Punished for Its Past Success?

The reality of Palantir in 2026 is different than it was just a few years ago. Investors who expect the stock to climb 550% in the next five years, as it has in the last five years, will likely be disappointed. The company has a lot of growth priced into it.

But that doesn’t mean it’s not worth a premium valuation. Institutions will continue to own PLTR, and analysts (with some exceptions) continue to raise their price targets. It’s possible that PLTR will continue to chop around for 2026 while investors sort out the winners and losers in the AI software space.

But just as was the case in 2021 and 2022, that patience is likely to be rewarded for retail investors, many of whom are content to hold the stock after taking out their initial investment.

The Eye Test Still Matters—And Palantir Keeps Passing It

Palantir is a victim of the self-fulfilling prophecy. At this point, the critics have nothing more to say other than valuation, and they’re confident that at some point, that will be reflected in the stock price.

I’m not going to argue math with anyone. That’s like debating metrics like expected batting average or WAR+ with baseball purists.

But in sports, as in investing, the eye test still matters. Palantir isn’t going to make the cut for investors who focus solely on valuation. There are plenty of other stocks that they can own and still sleep at night.

However, the eye test is compelling. Look at it this way. If you had one player to send to the plate for one at-bat in a “gotta have it” moment, there are a lot of players who come to mind that wouldn’t check the boxes as a great hitter. But will you bet against them in the moment? Probably not.

That analogy works for Palantir on two levels. Palantir not only met the moment, it crushed it. Furthermore, it suggested that there’s even stronger growth to come, which almost doesn’t seem possible. And it would be dubious, except that Palantir has continued to do surprise quarter after quarter.

But it also illustrates what Palantir means to its customers on both the commercial and business sides. They rely on Palantir’s Ontology to deliver the insights that they can’t get in any other way.

It’s not a valuation darling. Its business model is misunderstood and, in some cases, misrepresented. But investors who are waiting for PLTR to get the analysts’ stamp of approval will be kept waiting. Meanwhile, the stock is likely to move higher over time. READ THIS STORY ONLINE

The #1 stock to buy BEFORE the June S-1 filing (Ad)

The #1 stock to buy BEFORE the June S-1 filing

When the SpaceX IPO launches, most retail investors will be locked out. The banks, funds, and insiders get in early – while everyone else waits on the sidelines.

But one small infrastructure supplier – a critical piece Musk can’t scale the Colossus network without – is still trading well under institutional radar. A new briefing reveals the name and ticker at no cost.GET THE SPACEX INFRASTRUCTURE STOCK NAME AND TICKER HERE

TSLA: 3 Reasons the Stock Could Hit $400 in May

Written by Sam Quirke

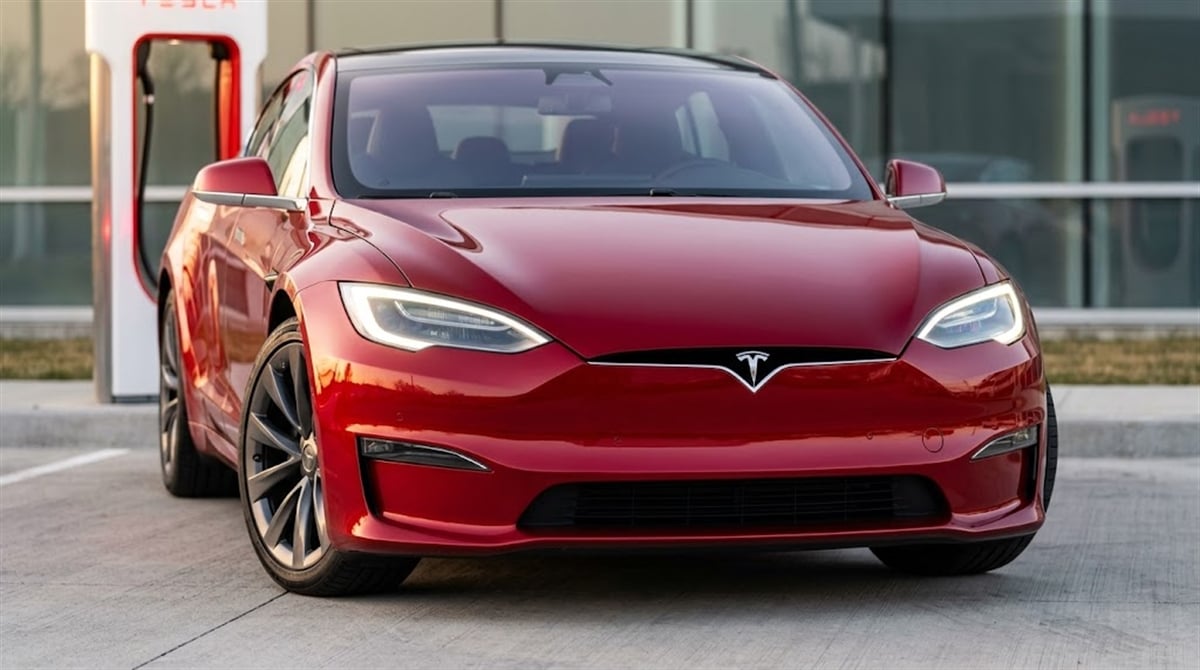
A red Tesla Model S electric sedan parked at a Tesla Supercharger station.

Having initially traded down following last month’s earnings report, shares of Tesla Inc (NASDAQ: TSLA) are once again pointing north. The stock is currently trading around $390, putting it within touching distance of $400. This means that Tesla has not only recovered the ground it lost following April’s report but has actually pushed past its pre-earnings price, a clear sign that sentiment has swung to the bulls’ side.

That kind of price action matters, especially given the multi-month downtrend that had been gathering pace. As we head into the start of summer, it’s looking more and more like Tesla has flipped the narrative back in its favor, and the path toward $400 looks increasingly clear. Let’s take a look at the bull case and the top three reasons in particular that Tesla should be back trading above that level in the coming weeks.

Reason #1: The Earnings Reset Has Reopened the Bull Case

As MarketBeat noted at the time, Tesla’s latest earnings report didn’t need to be perfect. It just needed to be good enough to stabilize the story and remind investors of the company’s underlying strength—which is exactly what it did.

Margins improved, profitability held up better than many had feared, and the company’s Services revenue grew strongly. Taken together, these factors helped shift the focus away from short-term concerns around demand and pricing pressure and back toward Tesla’s ability to generate sustainable earnings.

More importantly, the report addressed one of the key bearish arguments that had been building in recent months. That is, Tesla’s core business was losing momentum in a way that could not be easily offset by exciting, but as yet unrealized, future ambitions. 

Instead, what the results showed was a business that is adjusting, not collapsing. This distinction is crucial. When a stock is under pressure, the first step toward a recovery is removing the worst-case scenario from the table. Tesla has done that, and in doing so has diminished, if not completely removed, one of the stronger headwinds that was pushing the stock down in recent weeks.

Reason #2: The Growth Story Is Now Bigger Than Cars

If the earnings report stabilized the downside, then Tesla’s evolving growth narrative has been driving the upside. Thanks in large part to clear messaging on this in last month’s report, the company is increasingly being viewed through the lens of artificial intelligence, autonomy, and robotics rather than just as an electric vehicle manufacturer. This is a shift Tesla has been trying to achieve for months now, and it looks like it’s finally starting to stick.

Developments around full self-driving, the ongoing buildout of its robotaxi ambitions, and progress in areas like Optimus are all contributing to a broader story that extends well beyond car sales. Tesla continues to invest heavily in these areas, and the path to clear returns is becoming clearer. That’s helping to reposition the shift in investors’ minds from a theoretical pivot to an actual strategic plan.

In terms of what this means for the stock, the key point is that the company’s growth potential is expanding rapidly. While Tesla’s automotive business remains important, it’s no longer the sole driver of the valuation, and arguably isn’t even the primary driver of valuation anymore.

Investors are instead starting to price in the potential for entirely new revenue streams, which is creating room for the stock to move higher—hence why $400 could soon become the new floor.

Reason #3: Momentum and Sentiment Are Now Aligned

Perhaps the most important factor in the near term is the alignment between price action, sentiment, and positioning. Tesla’s recovery from last week’s post-earnings dip has been decisive, especially when you consider the stock had been selling off continuously since December.

The setup is, for now at least, looking less like a short-term bounce and more like the start of a fresh uptrend. At the same time, analyst sentiment is moving in the same direction. Recent updates over the past two weeks have seen HSBC upgrade the stock to a Buy rating, while Tigress Financial, Deutsche Bank, and President Capital all reiterated bullish positions. The updated price targets are also supporting the case for further upside from here, with President Capital’s fresh $428 target in particular suggesting that a move beyond $400 is imminent.

Add in a broader risk-on backdrop that’s driving equities to all-time highs, with investors increasingly happy to lean back into growth names like Tesla, and the setup becomes even stronger. The stock has quickly moved from the defensive to the offensive, and while it still needs to deliver, $400 now looks like the next step rather than an ambitious target. READ THIS STORY ONLINE

5 Space Stocks Set to Watch as the New Space Race Heats Up (Ad)

5 Space Stocks Set to Watch as the New Space Race Heats Up

With NASA’s Artemis missions underway and launch costs falling dramatically, the space economy is evolving into a long-term infrastructure play with contracts and recurring revenue to match.

A new free report highlights five publicly traded companies across launch, satellites, defense, and space-based intelligence – from a rocket company expanding into spacecraft manufacturing to a real-time satellite intelligence firm selling data to governments and corporations.READ THE FREE REPORT AND DISCOVER ALL FIVE SPACE ECONOMY STOCKS

More Stories

The Night Owl is a financial newsletter that provides in-depth market analysis on stocks of interest to individual investors. Published by MarketBeat and Early Bird Publishing, The Night Owl is delivered around 9:00 PM Eastern Sunday through Thursday. If you give a hoot about the market, The Night Owl is the newsletter for you.

The Night Owl Newsletter.

View as a Web Page

If you have questions or concerns about your account, please feel free to contact our U.S. based support team at contact@marketbeat.com.

Unsubscribe

© 2006-2026 MarketBeat Media, LLC. All rights reserved.
345 N Reid Pl. #620, Sioux Falls, S.D. 57103. United States of America..

Featured Link: Ticker Revealed: Pre-IPO Access to “Next Elon Musk” Company(From Banyan Hill Publishing)

The Bull Market’s Dangerous Disconnect

Stansberry Research Logo
Stansberry Digest

Delivering World-Class Financial Research Since 1999

The next phase in the Persian Gulf… Highs for stocks – and gas prices… A small housing thaw… Homebuilders aren’t following… A dangerous disconnect… An inflection point for semiconductors…


The new state of play…

Despite ammunition flying both ways between the U.S. military and the Islamic Revolutionary Guard Corps yesterday, “right now, the ceasefire certainly holds,” Secretary of Defense Pete Hegseth said earlier today.

The U.S. is not “restarting major combat operations at this point,” Joint Chiefs of Staff Chair General Dan Caine said today. But the military isn’t backing down from a fight, either… And it’s leaving open the possibility of ramping up attacks in Iran.

Meanwhile, Project Freedom – the name given to the U.S effort to escort stranded commercial ships out of the Persian Gulf – “is defensive in nature, focused in scope, and temporary in duration,” Hegseth said.

There are hundreds of ships waiting to pass through the Strait of Hormuz safely. But as of our last check, traffic through the strait is still moving at a crawl. U.S. forces escorted only two ships out of the Persian Gulf yesterday, and global energy supply remains seriously disrupted.

Still, after a spate of volatility yesterday, Mr. Market absorbed this information as a good thing. Oil futures fell more than 3%, and the benchmark S&P 500 Index and tech-heavy Nasdaq Composite Index traded back toward their highs today.

At the gas pumps this morning, there were new highs, too…

The national average for a gallon of regular gasoline in the U.S. is now $4.48, about $1.70 more than at the start of the year. Diesel is close to $5.66 per gallon, on average, less than 20 cents from its all-time high set in the summer of 2022. And pity the Californians paying $6.13 per gallon of regular gas.

But people are going to work. Trucks are going to jobs. At a gas station north of Baltimore earlier today, there were various folks filling up almost two dozen vehicles around me (Corey McLaughlin). “$4.20 a gallon?” one construction worker asked aloud. He started filling up anyway.

So did I, although I’m thinking it might be wise to start applying an investing concept – dollar-cost averaging – to gas purchases. Filling up regularly could help hedge against potential future higher prices.

As our colleague Mike Barrett wrote in last week’s Select Value Opportunitiesupdate…

After seven weeks of war, energy analytics firm Kpler estimates that the global oil market has lost approximately 500 million barrels worth of oil supply.

That’s roughly equivalent to the amount of fuel all vehicles worldwide consume in 11 days.

Mike noted that various nations – like South Korea, Pakistan, and Slovenia – are already rationing fuel. And “demand destruction” – “a sustained, and possibly permanent, decline in product demand due to changes in market structure” like limited supply resulting in higher prices – might not be limited strictly to oil…

“The Iran war has altered the market for food imports into Iran and the Middle East,” Mike wrote. “That’s destroying demand for the crops grown by American farmers…” In other words, we’ve only just started to see the economic impacts from the war in Iran.

Looking elsewhere, some good news…

In March, sales of newly constructed homes rose to an annual rate of 682,000. That pace is still in the same range of between 600,000 and 700,000 homes that it has been stuck in since 2023, but the rate was up more than 7% from February, and 3% higher than the year before.

This could be a sign that the housing market is thawing (which we’ve written about here), especially because it comes in the face of higher mortgage rates in March. But mortgage rates moved lower again in April.

However, related housing stocks aren’t telling the same story…

The State Street SPDR S&P Homebuilders Fund (XHB) is down more than 1% this year, versus a 6% gain for the S&P 500 Index. And two significant stocks in XHB are down much more than that…

Home Depot (HD) and Lowe’s (LOW) are far and away the two largest housing retailers in the U.S. They’re also two of the top 10 largest retailers in the country by revenue. So you would expect these two companies to thrive as housing sales bounce back.

But so far in 2026, the exact opposite has happened…

Home Depot shares are down more than 8% this year and are 26% lower from their September high. The stock now sits near its lowest level in more than two years.

As for Lowe’s, the stock is down 7% in 2026 and has fallen more than 20% from its most recent high.

Both of those companies will report their first-quarter results in two weeks. So we’ll have to wait until then to see if their businesses saw the same bounce the housing market did in February and March.

But with how the stocks have been performing, investors aren’t optimistic that these companies will ride the tailwinds. So what gives?

It’s a disconnect between the ‘real’ economy and the broader stock market…

This is a theme we’ve frequently covered about various parts of the economy, like mounting consumer debt and the growing cracks in the labor market while headline stock indexes hit new highs…

This isn’t totally unusual behavior. It has often been said that the economy is not the stock market and vice versa.

In other words, the economy and stock market can behave as if they’re living on different timelines. Economic data represents the past, while stock prices are tied to investors’ expectations for how companies will perform (or casino-like speculation in some cases).

We’ve seen markets rebound plenty of times before major risks to the U.S. economy are resolved… most recently, during the COVID-19 pandemic panic and rebound or the Liberation Day panic and rebound.

Today, war volatility aside, AI remains the biggest story for investors. And the strength in the top AI names during a multiyear bull market has allowed many folks to overlook what’s going on elsewhere.

As we wrote last week, AI-related spending accounted for more than 40% of all growth in the first quarter, according to U.S. gross domestic product (“GDP”) data.

But while the broader stock market has been giving the appearance of “all clear” lately, all is not well under the hood.

Housing accounts for about 16% of all economic growth in the U.S., and the housing “freeze” of the past few years has been a headwind for the total economy’s growth. Even with the two-month rebound in new home sales, that’s still the case.

Existing home sales (which make up 90% of all housing sales) hit a nine-month low in March, and related stocks are among the worst performers of the year. You just wouldn’t know it if you only follow the headline indexes.

But you might soon…

A signal of weakening health…

The S&P 500’s advance-decline line – a measure of market breadth – has shown that over the recent three-week surge to new all-time highs, fewer stocks are participating in the rally.

As Ten Stock Trader editor Greg Diamond wrote to subscribers today, the Dow Jones Industrial Average looks weakest of the major U.S. indexes right now and appears to have “topped.” The others could follow.

Home Depot and Lowe’s are perfect examples of large companies not following the market. This isn’t a sign of a healthy rally, but a warning that the market is ripe for another sell-off – especially if shares of the AI leaders powering the market falter in the weeks ahead.

An ‘inflection point’ ahead…

Thanks to the AI boom, semiconductors might also be at an “inflection point,” according to Stansberry Research senior analyst Brett Eversole.

In this morning’s DailyWealth newsletter, Brett noted that semiconductor stocks jumped a massive 47% in just 18 trading days amid the stock market rebound over the past two months.

Looking at this chart, “you might feel incredibly bullish… or fearful,” Brett wrote. “History justifies both reactions.”

This kind of semiconductors performance has happened only 10 other times since 1994. At a broad level, the results look good, showing a roughly 11% average return after six months and around a 19% average return one year later.

However, digging deeper into the 10 prior instances, the sector saw gains one year later only half the time. And you didn’t want to be on the wrong end of the bet if these stocks went lower. As Brett wrote…

In cases where semiconductors rise, they soar an average of 76% over the next year. But when they fall, the sector crashes 38% on average.

That’s why semiconductor stocks are at an inflection point today.

As investors, we should prepare for both possibilities…

Brett’s staying put right now – riding the trend for semiconductors higher but being prepared for the sector to possibly head lower.

We’re not saying it’s time to go “all out” of semiconductors (or the AI boom, for that matter), but it’s certainly not time to go “all in” either. Be selective, as it looks like these stocks (and the bull market) are nearing an important turning point.


Recommended Links:

Until Tomorrow: Will You Be Left Behind?

Two financial legends predict a paradigm shift will reset the market, cause Magnificent Seven stocks to plummet, and define the true winners of the next AI era. Fifty-year Wall Street legend Marc Chaikin and Silicon Valley insider Jeff Brown recently sat down together to share how you can access the names of SIX companies that could get left behind in the next era of AI. Click here for more details.


SpaceX’s ‘Dark Energy’ Could Replace Foreign Oil

For years, we’ve been told that SpaceX is a rocket company. But according to new satellite images from 300 miles above the Earth’s surface, there is something very strange going on at SpaceX right now that has nothing to do with space. It could soon replace our need for foreign oil forever and ignite a $10 trillion boom for the stocks involved. Click here to learn more.


New 52-week highs (as of 5/4/26): Atlas Energy Solutions (AESI), Amazon (AMZN), Alpha Architect 1-3 Month Box Fund (BOXX), CBOE Global Markets (CBOE), Chord Energy (CHRD), Ciena (CIEN), Cisco Systems (CSCO), Simplify Managed Futures Strategy Fund (CTA), DigitalOcean (DOCN), DXP Enterprises (DXPE), Emcor (EME), iShares MSCI Emerging Markets ex China Fund (EMXC), iShares MSCI South Korea Fund (EWY), FirstCash (FCFS), Flex LNG (FLNG), iShares Convertible Bond Fund (ICVT), Liberty Energy (LBRT), Lumentum (LITE), Marathon Petroleum (MPC), Pembina Pipeline (PBA), Roku (ROKU), ProShares Ultra Technology (ROM), USCF SummerHaven Dynamic Commodity Strategy No K-1 Fund (SDCI), and Viper Energy (VNOM).

In today’s mailbag, some replies to a question raised in yesterday’s mail… Do you have a comment or question? As always, e-mail us at feedback@stansberryresearch.com.

“RE: Troy J’s comment, ‘what benefit would YOU like to give up to help the situation?’

“ALL OF THEM! I don’t want any government help; I just want them the hell out of my life (and pocket). I’ve earned my Social Security ‘benefits’ and would have done much better if left to handle my own retirement. Those aren’t really benefits, they’re just returning some of the value they stole from me.

“The problem with this country is that everyone THINKS they can get (or are getting) more OPM (other people’s money) from the government. It can’t work with a behemoth in the middle, consuming a significant portion of the resources. TAKE CARE OF YOURSELVES!” – Subscriber Mike M.

“Since Troy J. asked in Monday’s Digest, here’s a short list of the ‘benefits’ I would like to give up to go back to gold money:

“The Internal Revenue Service… The Federal Reserve… The Ukraine war… Day care benefits for my 75 imaginary adopted Somali children… The social security checks I collect on behalf of my great, great, great, great grandparents… Cryptocurrency (a scramble for sound money that consumes much talent and computing power)… [Editor’s note: Point taken, but we find value in cryptocurrencies too.] Un-affordable housing… Buying industrial production from abroad… Endlessly expanding government bureaucracy that may or may not be able to answer e-mail.

“Thank you for the invitation [for the list].” – Stansberry Alliance member Paul J.

All the best,

Corey McLaughlin and Nick Koziol
Baltimore, Maryland
May 5, 2026


Stansberry Research Top 10 Open Recommendations

Top 10 highest-returning open stock positions across all Stansberry Research portfolios. Returns represent the total return from the initial recommendation.InvestmentBuy DateReturnPublicationMSFT
Microsoft11/11/101,372.0%Retirement MillionaireMSFT
Microsoft02/10/121,335.3%Stansberry’s Investment AdvisoryCIEN
Ciena10/20/22853.4%Stansberry Innovations ReportGOOGL
Alphabet12/15/16844.1%Retirement MillionaireADP
Automatic Data Processing10/09/08817.2%Extreme ValueBRK.B
Berkshire Hathaway04/01/09761.9%Retirement MillionaireALS-T
Altius Minerals03/26/09668.1%Extreme ValueLITE
Lumentum04/15/21616.4%Stansberry Innovations ReportWRB
W.R. Berkley03/15/12616.2%Stansberry’s Investment AdvisorySII
Sprott01/11/18604.9%Extreme Value

Please note: Securities appearing in the Top 10 are not necessarily recommended buys at current prices. The list reflects the best-performing positions currently in the model portfolio of any Stansberry Research publication. The buy date reflects when the editor recommended the investment in the listed publication, and the return shows its performance since that date. To learn if a security is still a recommended buy today, you must be a subscriber to that publication and refer to the most recent portfolio.


Top 10 Totals3Extreme ValueFerris3Retirement MillionaireDoc2Stansberry Innovations ReportEngel2Stansberry’s Investment AdvisoryPorter 


Top 5 Crypto Capital Open Recommendations

Top 5 highest-returning open positions in the Crypto Capital model portfolioInvestmentBuy DateReturnPublicationBTC/USD
Bitcoin11/27/182,023.9%Crypto CapitalWSTETH/USD
Wrapped Staked Ethereum12/07/181,898.2%Crypto CapitalONE/USD
Harmony12/16/191,008.7%Crypto CapitalPOL/USD
Polygon02/26/21642.7%Crypto CapitalQRL/USD
Quantum Resistant Ledger01/19/21448.2%Crypto Capital

Please note: Securities appearing in the Top 5 are not necessarily recommended buys at current prices. The list reflects the best-performing positions currently in the Crypto Capital model portfolio. The buy date reflects when the recommendation was made, and the return shows its performance since that date. To learn if it’s still a recommended buy today, you must be a subscriber and refer to the most recent portfolio.


Stansberry Research Hall of Fame

Top 10 all-time, highest-returning closed positions across all Stansberry portfoliosInvestmentDurationGainPublicationNvidia (NVDA)^*5.96 years1,466%Venture Tech.Microsoft (MSFT)^12.74 years1,185%Retirement MillionaireInovio Pharma. (INO)^1.01 years1,139%Venture Tech.Rocket Lab (RKLB)^2.35 years1,034%Venture Tech.Seabridge Gold (SA)^4.20 years995%Sjug Conf.Berkshire Hathaway (BRK-B)^16.13 years800%Retirement MillionaireIntellia Therapeutics (NTLA)1.95 years775%Amer. MoonshotsRite Aid 8.5% bond4.97 years773%True IncomePNC Warrants (PNC-WS)6.16 years706%True Wealth SystemsMaxar Technologies (MAXR)^1.90 years691%Venture Tech.

^ These gains occurred with a partial position in the respective stocks.
* Editor Dave Lashmet closed the first leg of this Nvidia position in November 2016 for a gain of about 108%. Then, he closed the second leg in July 2020 for a 777% return. And finally, in May 2022, he booked a 1,466% return on the final leg. Subscribers who followed his advice on Nvidia could’ve recorded a total weighted average gain of more than 600%.


Stansberry Research Crypto Hall of Fame

Top 5 highest-returning closed positions in the Crypto Capital model portfolioInvestmentDurationGainAnalystBand Protocol (BAND)0.31 years1,169%Crypto CapitalTerra (LUNA)0.41 years1,166%Crypto CapitalPolymesh (POLYX)3.84 years1,157%Crypto CapitalFrontier (FRONT)0.09 years979%Crypto CapitalBinance Coin (BNB)1.78 years963%Crypto Capital 

You have received this e-mail as part of your subscription to Stansberry Digest. If you no longer want to receive e-mails from Stansberry Digest click here.

Published by Stansberry Research.

You’re receiving this e-mail at pahovis@aol.com. Stansberry Research welcomes comments or suggestions at feedback@stansberryresearch.com. This address is for feedback only. For questions about your account or to speak with customer service, call 888-261-2693 (U.S.) or 443-839-0986 (international) Monday-Friday, 9 a.m.-5 p.m. Eastern time. Or e-mail info@stansberryresearch.com. Please note: The law prohibits us from giving personalized financial advice.

© 2026 Stansberry Research. All rights reserved. Any reproduction, copying, or redistribution, in whole or in part, is prohibited without written permission from Stansberry Research, 1125 N Charles St, Baltimore, MD 21201 or stansberryresearch.com.

Any brokers mentioned constitute a partial list of available brokers and is for your information only. Stansberry Research does not recommend or endorse any brokers, dealers, or investment advisors.

Stansberry Research forbids its writers from having a financial interest in any security they recommend to our subscribers. All employees of Stansberry Research (and affiliated companies) must wait 24 hours after an investment recommendation is published online – or 72 hours after a direct mail publication is sent – before acting on that recommendation.

This work is based on SEC filings, current events, interviews, corporate press releases, and what we’ve learned as financial journalists. It may contain errors, and you shouldn’t make any investment decision based solely on what you read here. It’s your money and your responsibility.